Silicon prices trended lower in December amid weakened demand and capital pressure of cargo holders

เผยแพร่แล้ว: Jan 14, 2021 14:30 (GMT+8)
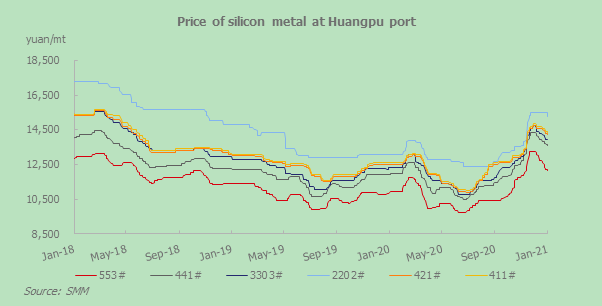
Silicon prices of various grades started to decline after a short period of stability in December 2020. The pressure on the supply side began to appear after the demand fell with high stocks of downstream raw material.

SHANGHAI, Jan 14 (SMM) — Silicon prices of various grades started to decline after a short period of stability in December 2020. The pressure on the supply side began to appear after the demand fell with high stocks of downstream raw material. Traders who stockpiled a large number of low-priced goods continued to cut prices in order to deplete inventories.

In addition, silicon plants were under capital shortage before year-end, and individual large plants were still under pressure to reduce their stocks. Under the combined effects of various negative factors, silicon prices gradually fell.
Operating rates of primary aluminium alloy declined slightly in December due to the decline in end-user automobile demand. Operating rates of secondary aluminium alloy basically maintained, while most aluminium alloy factories actively stockpiled from October to November, so there were only a few orders for rigid demand in December. Most of them are to digest low-priced inventories in the hands of holders, and the overall market turnover weakened significantly.

Secondary aluminium alloy companies in Guangdong, Zhejiang and other regions that rely on imported scrap aluminium as raw materials are facing the dilemma of lack of raw materials in 2021 due to changes in the import of scrap aluminium policies. Sluggish sentiment about future operating rates is also a reason for limiting purchases.

Silicone procurement was relatively stable in December, and two unexpected maintenance companies have not resumed production. Part of the monomer production capacity is planned to be shut down for maintenance before and after Chinese New Year. However, considering the pandemic outbreak and the CNY holiday, most of the organic silicon monomer plants are able meet the production volume of one and a half months to two months in January. Most of chemical-grade silicon is signed in the monthly order, and the price change lags behind that of metallurgical-grade silicon. Therefore, the monthly prices of 421# silicon was basically stable at 14,800-14,900 yuan/mt in early January.

On the export side, large-scale foreign aluminium companies successively restocked in December and released orders for Q2 2021. The number of orders allocated to the Chinese market decreased sharply compared with the previous quarter due to the high domestic silicon prices, the sharp rise in the exchange rate of RMB against the US dollar, and the soaring ocean freight. One of them all transferred to overseas procurement.

The two major downstreams of organic silicon and polysilicon had the willingness to restock in January before CNY. In addition, the overall transaction of the stocks of some aluminium alloy factories was better than that in December. The downstream areas of Hebei, Shandong and other regions were affected by the Covid-19 driven lockdowns in Hebei and completed stockpiling in early January. Inventories plus goods in transit are sufficient until at least the end of February. The pandemic has worsened and CNY is approaching, major Xinjiang manufacturers are worried about shipments, so they continue to cut prices for shipments in January to reduce the inventory pressure caused by the stagnation of transportation.

Domestic transportation vehicles were already less than the same period in previous years in mid-January. It is expected that domestic transactions will basically end around January 20, and the slight downward trend will continue. If the pandemic does not hinder the recovery of domestic automobile transportation after CNY, the inventory pressure accumulated by some small factories during CNY will be gradually released, and it will take time for domestic and overseas demand to recover. Silicon prices are likely to maintain a downward trend in the following weeks.

For more information on the silicon metal sector, please subscribe to China Silicon Metal Monthly database.


คำชี้แจงแหล่งที่มาของข้อมูล: นอกจากข้อมูลที่เปิดเผยต่อสาธารณะแล้ว ข้อมูลอื่นๆ ทั้งหมดได้รับการประมวลผลโดย SMM จากข้อมูลสาธารณะ การสื่อสารกับตลาด และการพึ่งพาแบบจำลองฐานข้อมูลภายในของ SMMข้อมูลเหล่านี้มีไว้เพื่ออ้างอิงเท่านั้น ไม่ถือเป็นข้อเสนอแนะในการตัดสินใจ

หากมีข้อสงสัยหรือต้องการทราบข้อมูลเพิ่มเติม กรุณาติดต่อ: lemonzhao@smm.cn
หากต้องการข้อมูลเพิ่มเติมเกี่ยวกับวิธีการเข้าถึงรายงานการวิจัยของเรา โปรดติดต่อ:service.en@smm.cn
ข่าวที่เกี่ยวข้อง
[SMM โครเมียมแฟลช] คาดการณ์อุปสงค์เหล็กทั่วโลกปี 2026 ทรงตัว เนื่องจากจีนอ่อนแอ คาดฟื้นตัวในปี 2027
21 ชั่วโมงที่แล้ว
[SMM โครเมียมแฟลช] คาดการณ์อุปสงค์เหล็กทั่วโลกปี 2026 ทรงตัว เนื่องจากจีนอ่อนแอ คาดฟื้นตัวในปี 2027
อ่านเพิ่มเติม
[SMM โครเมียมแฟลช] คาดการณ์อุปสงค์เหล็กทั่วโลกปี 2026 ทรงตัว เนื่องจากจีนอ่อนแอ คาดฟื้นตัวในปี 2027
[SMM โครเมียมแฟลช] คาดการณ์อุปสงค์เหล็กทั่วโลกปี 2026 ทรงตัว เนื่องจากจีนอ่อนแอ คาดฟื้นตัวในปี 2027
สมาคมเหล็กกล้าโลก (worldsteel) ได้ปรับแนวโน้มความต้องการเหล็กกล้าโลกเมื่อวันที่ 12 ตุลาคม โดยคาดการณ์ว่าความต้องการจะทรงตัวที่ 1.722 พันล้านตันในปี 2569 ก่อนจะเพิ่มขึ้น 1.7% เป็น 1.752 พันล้านตันในปี 2570 การปรับลดส่วนใหญ่สะท้อนถึงความต้องการที่อ่อนแอกว่าคาดในจีน ซึ่งคาดว่าความต้องการเหล็กกล้าจะหดตัว 2.0% ในปี 2569 และอีก 1.0% ในปี 2570 นอกจีน ความต้องการคาดว่าจะเติบโต 1.5% ในปี 2569 และเร่งขึ้นเป็น 4.0% ในปี 2570 สำหรับตลาดโครเมียม แนวโน้มเหล็กกล้าโลกที่ซบเซาชี้ให้เห็นว่าการฟื้นตัวในวงกว้างของความต้องการที่เกี่ยวข้องกับเหล็กกล้าอาจใช้เวลานานกว่าจะเกิดขึ้นจริง แม้ว่าแนวโน้มจะแตกต่างกันไปตามภูมิภาค ความต้องการเหล็กกล้าของอินเดียคาดว่าจะเติบโต 7.9% ในปี 2569 ขณะที่ความต้องการในสหรัฐอเมริกาคาดว่าจะเพิ่มขึ้น 2.0% แนวโน้มภูมิภาคที่แตกต่างกันเหล่านี้เป็นบริบทสำคัญสำหรับผู้ผลิตแร่โครเมียมและเฟอร์โรโครมในการประเมินสภาวะตลาดปลายทาง อย่างไรก็ตาม การคาดการณ์ครอบคลุมความต้องการเหล็กกล้าโดยรวมมากกว่าเหล็กกล้าไร้สนิมโดยเฉพาะ จึงไม่ได้ระบุปริมาณการใช้โครเมียมในอนาคตโดยตรง
21 ชั่วโมงที่แล้ว
[เอสเอ็มเอ็ม ข่าวด่วนโครเมียม] การส่งออกแร่โครเมียมของแอฟริกาใต้เดือนสิงหาคมลดลง 11% ขณะที่การส่งออกเฟอร์โรโครมฟื้นตัว 20%
21 ชั่วโมงที่แล้ว
[เอสเอ็มเอ็ม ข่าวด่วนโครเมียม] การส่งออกแร่โครเมียมของแอฟริกาใต้เดือนสิงหาคมลดลง 11% ขณะที่การส่งออกเฟอร์โรโครมฟื้นตัว 20%
อ่านเพิ่มเติม
[เอสเอ็มเอ็ม ข่าวด่วนโครเมียม] การส่งออกแร่โครเมียมของแอฟริกาใต้เดือนสิงหาคมลดลง 11% ขณะที่การส่งออกเฟอร์โรโครมฟื้นตัว 20%
[เอสเอ็มเอ็ม ข่าวด่วนโครเมียม] การส่งออกแร่โครเมียมของแอฟริกาใต้เดือนสิงหาคมลดลง 11% ขณะที่การส่งออกเฟอร์โรโครมฟื้นตัว 20%
การส่งออกแร่โครเมียมของแอฟริกาใต้ลดลง 10.75% เมื่อเทียบรายเดือน อยู่ที่ 2.36 ล้านตันในเดือนสิงหาคม 2569 ขณะที่การส่งออกเฟอร์โรโครมคาร์บอนสูงเพิ่มขึ้น 20.0% อยู่ที่ 117,180 ตัน สะท้อนแนวโน้มที่แตกต่างกันในการค้าโครเมียมของประเทศ จีนยังคงเป็นปลายทางหลักของแร่โครเมียม โดยรับไป 1.67 ล้านตัน หรือคิดเป็น 70.8% ของยอดส่งออกทั้งหมด แม้จะลดลง 6.09% เมื่อเทียบรายเดือน ขณะเดียวกันการส่งออกเฟอร์โรโครมได้รับแรงหนุนจากการส่งมอบไปยังอเมริกาเหนือที่เพิ่มขึ้น โดยแคนาดารับไป 26,373 ตัน และสหรัฐอเมริกา 26,029 ตัน รวมกันคิดเป็น 44.7% ของการส่งออกเฟอร์โรโครมของแอฟริกาใต้ การเคลื่อนไหวที่สวนทางกันนี้ชี้ให้เห็นถึงอุปสงค์แร่โครเมียมดิบจากต่างประเทศที่อ่อนตัวลง ควบคู่ไปกับการฟื้นตัวของการส่งออกเฟอร์โรโครม โดยเฉพาะไปยังอเมริกาเหนือ อย่างไรก็ตาม การดีดตัวรายเดือนของการส่งออกเฟอร์โรโครมยังไม่เพียงพอที่จะยืนยันการฟื้นตัวอย่างยั่งยืนของการถลุงในประเทศ ขณะที่สัดส่วนการส่งออกแร่ที่จีนครองเป็นหลักทำให้การส่งออกของแอฟริกาใต้มีความเสี่ยงต่อการเปลี่ยนแปลงของกิจกรรมการจัดซื้อของจีน
21 ชั่วโมงที่แล้ว
[SMM รีวิวโครเมียมรายสัปดาห์] กระแสการส่งออกฟื้นตัว ขณะที่สต็อกท่าเรือจีนเพิ่มขึ้นและราคาแอฟริกาแตกต่าง
21 ชั่วโมงที่แล้ว
[SMM รีวิวโครเมียมรายสัปดาห์] กระแสการส่งออกฟื้นตัว ขณะที่สต็อกท่าเรือจีนเพิ่มขึ้นและราคาแอฟริกาแตกต่าง
อ่านเพิ่มเติม
[SMM รีวิวโครเมียมรายสัปดาห์] กระแสการส่งออกฟื้นตัว ขณะที่สต็อกท่าเรือจีนเพิ่มขึ้นและราคาแอฟริกาแตกต่าง
[SMM รีวิวโครเมียมรายสัปดาห์] กระแสการส่งออกฟื้นตัว ขณะที่สต็อกท่าเรือจีนเพิ่มขึ้นและราคาแอฟริกาแตกต่าง
เผยแพร่: 16 ต.ค. 2569
21 ชั่วโมงที่แล้ว

