

SMM9 March 3: in 2020, due to the impact of the epidemic, superimposed Glencore cut supply and lowered production expectations, hand-held ore supply is also limited, overall, cobalt ore supply is tight. On the consumer side, as the global consumer electronics and power markets pick up, cobalt prices are gradually approaching their highs since the beginning of the year and remain stable.
The performance of cobalt companies has been boosted to some extent by fluctuations in cobalt prices. According to the first-half results of the four cobalt industry giants known by SMM, in addition to the decline in Grimme net profit, the net profit of Luoyang Molybdenum, Huayou Cobalt and Hanrui Cobalt increased year-on-year, of which the net profit of Huayou Cobalt soared 965.28% compared with the same period last year, and the net profit of Hanrui Cobalt Industry soared 180.98% compared with the same period last year.

Huayou cobalt industry
During the reporting period, a total of 13510 tons of cobalt products were produced (including entrusted processing business), which was basically the same as the same period last year; sales of cobalt products were 10360 tons, a decrease compared with the same period last year (due to the conversion of some market demand to entrusted processing business). A total of 13004 tons of precursors were produced, an increase of 95.47 percent over the same period last year; sales of precursors were 12745 tons, an increase of 87.92 percent over the same period last year, excluding 6578 tons of overseas products directly exported by joint ventures, an increase of 215.64 percent over the same period last year.
In terms of capacity expansion, the second phase of the Huajin project of Huayou Cobalt New Energy Plate, the new large-scale R & D line, the spray test line, and the cobalt alloy expansion project of the non-ferrous plate have been basically completed, debugged or put into use; lithium battery recycling material pretreatment, Quzhou Science and Technology Innovation Center, Tongxiang headquarters Central Research Institute and other projects are under construction.
The product line certification of Huahai New Energy Project has been basically completed and has entered large-scale batch supply; affected by the novel coronavirus epidemic, the production line certification and 4m modification of Huajin Project, Huapu Project, Leyou Project and Puhua Project are affected to varying degrees. Huapu Project and Huajin Project are expected to be completed in the first half of next year, and Puhua and Leyou projects are expected to be completed in the second half of this year.
Previously, it was reported that in mid-July, the subsidiary Quzhou Huayou 30,000 tons (metal quantity) high purity ternary power battery grade nickel sulfate project officially started construction, and the completion of the project is of great significance for the company to build an integrated industry chain of lithium and electric materials. During the reporting period, the company also started the preliminary work of projects with an annual production capacity of 50, 000 tons of ternary precursor materials for high-nickel power batteries and 45000 tons of high nickel matte per year in Indonesia.
Cold sharp cobalt industry
As a leading enterprise in the cobalt industry, due to the consumption of high-priced cobalt storage in 2019, the cost of cobalt products in the reporting period decreased by 12.25% compared with the same period last year, so the company's profitability improved during the reporting period. The company achieved revenue of 1.036 billion yuan in the first half, an increase of 12.32% over the same period last year. The net profit belonging to shareholders of listed companies was 61.9711 million yuan, up 180.98% from the same period last year.
The company accelerated the production capacity of Congo Matt and Koluvezi, while the company's revised fundraising project in February 2018 invested 5000 tons of electrolytic cobalt and 20, 000 tons of electrowinning copper, further strengthening the company's competitiveness in production capacity and reducing logistics and transportation costs. With the expansion of the production capacity of cobalt products, the company's electrolytic copper production capacity has been expanded at the same time, and its performance contribution has gradually increased with the increase of the volume of electrolytic copper.
During the reporting period, Ganzhou Hanrui, as the starting point for the company to enter the new energy field, refined the preparation before construction, improved the project construction planning, and helped the company's strategic landing. Simultaneously complete the organizational structure adjustment, system and process construction, management and control system and other supporting construction of the two major projects. On June 4, 2020, the company's non-public offering of A-shares was approved by the Securities Regulatory Commission, and received a total of 1901275999.20 yuan on July 13, 2020 to assist the construction of the Hanrui project in Ganzhou through refinancing. Through the advantages of a complete industrial chain, we will form core business growth and increase new profit points, and further consolidate the main business.
Luoyang molybdenum industry
As the world's second largest cobalt miner, Luoyang molybdenum industry's operating income in the first half of the year was 46.7 billion yuan, up 368% from the same period last year, mainly because the company completed the acquisition of IXM 100% of the world's third largest metal trading company, headquartered in Geneva, Switzerland, on July 24, 2019. This period increased the basic metals trading business compared with the same period last year.
During the reporting period, the production and operation of various business sectors of the company was stable, and the copper metal output of TFM copper and cobalt business in Congo (DRC) increased by 2.80% compared with the same period last year. At the same time, in order to deal with the impact of the epidemic on logistics, especially port closure in South Africa and other countries, the company relied on IXM's developed global logistics network to quickly adjust the transport route and seek alternatives to ensure the overall stability of the transportation of raw materials and finished goods.
Greenmei
During the reporting period, the shipments of ternary precursor materials of Grimme's leading products exceeded 16000 tons. Although the shipment of ternary precursor materials still ranks first in the world industry, accounting for more than 20% of the world market, it is still down 51% compared with the same period last year. On the other hand, in the case of a decline in orders in the global ternary materials market, the company decisively strategically adjusted the new energy business structure, immediately expanded the capacity of cobalt tetroxide materials for consumer batteries, and grabbed global orders for cobalt tetroxide materials. In the first half of the year, the shipment of cobalt tetroxide materials was nearly 6000 tons, an increase of 57% over the same period last year, maximizing the impact of the decline of ternary precursors. In the first half of the year, the new energy materials business achieved sales revenue of 2.7421293 billion yuan, down 33.56% from the same period last year, and contributed gross profit of 626.6714 million yuan, down 33.91% from the same period last year.
At present, the company's high-nickel and low-cobalt 9 series ternary precursors have been mass produced; ultra-low cobalt content Ni98 precursor products have entered the mass production certification stage (ultra-low cobalt high nickel NCM98 containing 0.45% cobalt and ultra-low cobalt high nickel NCA98 precursors containing less than 1.0% cobalt), and have high nickel full series cobalt-free technology and hydrogen energy catalytic material manufacturing technology reserves; NCMA quaternary precursor technology has completely broken through and entered the stage of mass production. At the same time, the company also developed core-shell precursor technology of NCM8 series and 9 series, realized the transformation from second-generation core-shell technology to third-generation and fourth-generation core-shell technology, and successfully developed the latest generation of high-nickel and low-cobalt core-shell precursors with double concentration gradient, marking the company's successful step into the "unmanned zone" of the latest generation of high-nickel and low-cobalt core-shell precursor manufacturing technology in the world.
In addition, Grammy ultrafine cobalt powder has an international and domestic market share of more than 40% and 50% respectively, ranking in the forefront of the world industry.
To sum up, benefiting from the rise in cobalt prices, the leading enterprises in the cobalt industry performed well in the first half of the year, and the late trend of cobalt prices also affected the performance of enterprises in the future.
According to SMM, China's total production of cobalt sulfate in the first half of 2020 was 16900 tons of metal tons, down 24 percent from the same period last year. The decline in the production of cobalt sulfate is mainly due to the influence of novel coronavirus's epidemic situation, the demand for ternary precursors and materials downstream has been greatly reduced, the price of cobalt sulfate has been seriously upside down, and some manufacturers have switched production lines to cobalt chloride, or carried out technical transformation and maintenance, resulting in a reduction in the supply of cobalt sulfate. In the first half of the year, China's total output of cobalt chloride was 17000 tons of metal tons, up 12.3% from the same period last The output of cobalt chloride increased, and under the influence of the epidemic, the demand of digital 3C was less affected than that of power ternary. The water of cobalt chloride is higher than that of cobalt sulfate, and some cobalt salt plants switch production lines to cobalt chloride, and the output of cobalt chloride increases.
In terms of prices, in the first half of 2020, the average price of SMM metal cobalt was 258400 yuan / ton, down 9.5% from the same period last year; the average price of cobalt sulfate was 49000 yuan / ton, down 9.7%; the average price of cobalt chloride was 59000 yuan / ton, down 6% from the same period last year; and the average price of cobalt tetroxide was 187000 yuan / ton, down 7.2% from the same period last year.
Affected by the epidemic, there was only a brief discount of other cobalt products to cobalt sulfate in February, mainly due to the outbreak of the novel coronavirus epidemic in China in February, logistics and workers' rework were blocked, large factories of ternary precursors did not stop work during the Spring Festival, cobalt sulfate was in short supply, and prices went up. However, the production and sales of new energy vehicles have been seriously affected by the epidemic, and overseas epidemics broke out one after another in March. Export orders for ternary precursors have been reduced, demand for cobalt sulfate remains low, prices are upside down, and other cobalt products continue to raise water for cobalt sulfate.
Recently, the price gap at home and abroad has narrowed. Although the overall demand for battery materials downstream increases, it is expected that the fourth quarter will enter the off-season of digital 3C procurement, battery and terminal industry inventory is the highest, cobalt prices will continue to be under pressure or will decline slowly, but the downside space is limited.
"2020 (second) China Automotive New Materials Application Summit Forum"
It was solemnly held in Shanghai from September 17 to 18.
During the reform period of the "four modernizations of the automobile", intelligent network connection, new energy, lightweight and intelligent manufacturing entered the field of the automobile industry, and the automobile era was reinterpreted. The surging changes require the industry to continue to integrate and innovate, and quickly promote the development rate of automobile enterprises. With the emergence of self-driving and intelligent cars, Internet companies, which are not active in the automotive field, have more opportunities to show their talents; the double points policy is becoming an important driving force for the development of China's new energy vehicle industry; in the face of environmental constraints, car companies speed up the application of advanced lightweight components and technologies to achieve vehicle weight loss. With the continuous promotion of the strategies of "Industrial 4.0" and "made in China 2025", intelligent manufacturing has become a new challenge of upgrading and transformation.
Under the guidance of the Shanghai Economic and Informatization Commission and the Shanghai Federation of Industrial economy, in order to accelerate the application of automobile lightweight and product lines, the Shanghai Nonferrous Metals Industry Association, together with Shanghai Automotive Engineering Society, Suzhou Die casting Technology Association and SMM, jointly held the "2020 (second) China Automotive New Materials Application Summit Forum". Jointly discuss material solutions, co-casting automobile industry chain green development closed loop, and strive to build an excellent communication and cooperation platform for the whole automobile industry chain, and lead the creation of advanced automobile industry clusters.
Click to understand and sign up for the 2020 China Automotive New Materials Application Summit Forum.
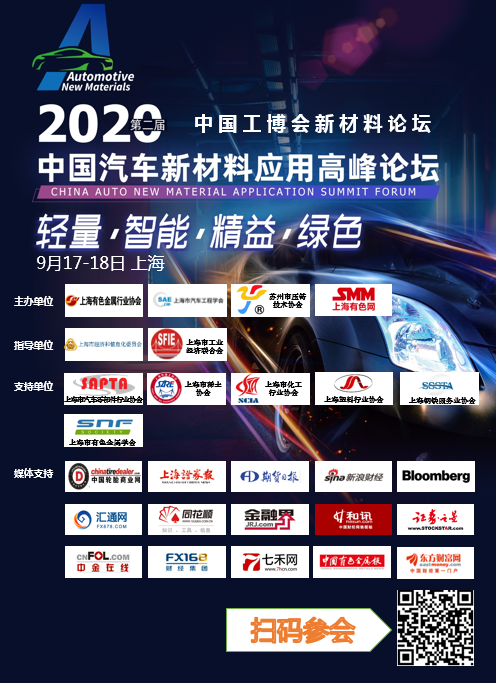
Please fill in your personal information on the last page and the meeting staff will contact you later!
Scan the QR code and apply to join the SMM Automotive Industry Exchange Group.



