[SMM thread] the road of accumulation is not over, and the upward road of steel price is not over.

เผยแพร่แล้ว: Jul 16, 2020 17:47
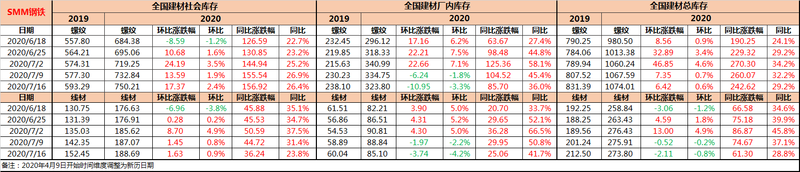
As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current year-on-year increase in inventory continues to narrow. (this week, the year-on-year increase of thread pool narrowed by 3%.


SMM7 March 16:

As of July 16, the country's total inventory of building materials was 10.7401 million tons, with a month-on-month ratio of + 0.6%, compared with the same period last year. Seasonal interference has not faded, central China, East China, southwest and other areas are still shrouded in overcast and rainy weather, terminal demand continues to be suppressed, so the thread inventory is still in a state of accumulation. However, after South China took the lead in "getting rid of difficulties", the strong replenishment of local demand is an important argument to prove the objective existence of the demand for quick work. The urgent demand for work is more urgent than in previous years, and the terminal just needs a good year-on-year performance, which is an important reason why the current inventory growth continues to narrow year-on-year (this week, the thread pool growth rate narrowed by 3 percentage points year-on-year).

Table 1: Overview of thread inventory
Source: SMM


Table 2: comparison of Thread inventory prices from 2018 to 2020
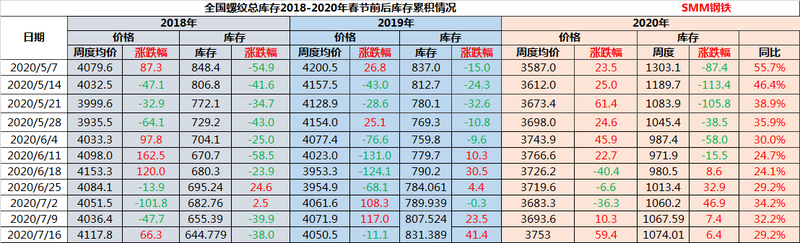
Note: due to the epidemic factors since 2020, due to the different opening times in different places, there is a certain error in the actual spot average price; the time dimension is the Gregorian calendar date.


Source: SMM

Specifically:

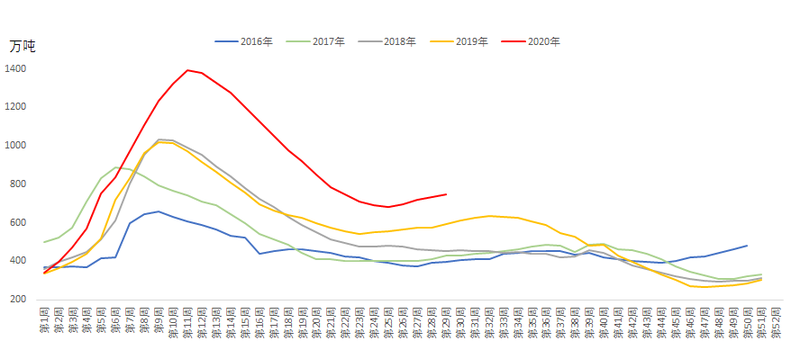
Social inventory of 7.5021 million tons, an increase of 173700 tons this week, + 2.4% month-on-month, + 26.9% year-on-year.

Under the background of a positive situation in the A-share bull market, the raw material side was led by the news side to rise first, driving the period snail to continue the strong situation in the past two weeks. The expectation of the spot market for the future is also improving, and the enthusiasm of traders to take goods has been significantly improved, accelerating the transfer of the factory warehouse to the social warehouse. While the terminal "steel needs" is "serious illness has not been cured", so the speed of accumulation has been accelerated.

Figure 1: an overview of the trend of threaded community library since 2016
Source: SMM

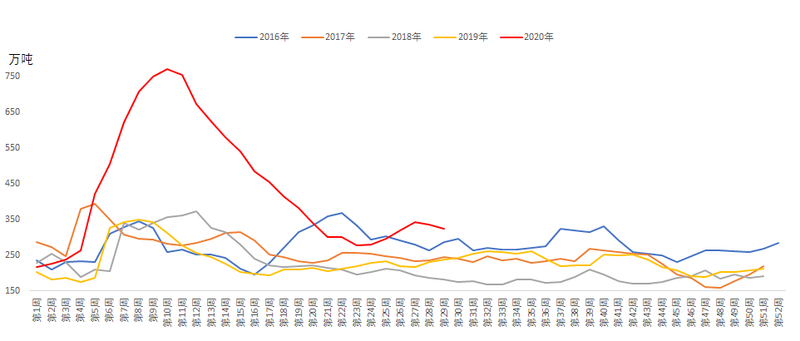
The inventory in the plant is 3.238 million tons, down 109500 tons this week,-3.3% month-on-month, + 36.0% year-on-year.

In addition to the market merchants' enthusiasm for taking goods driven by strong expectations, the decline in the output of steel mills is also an important reason for the decline in the factory warehouse. Under the dual pressure of high plant pressure and poor profitability, the overhaul and production reduction plans of steel mills have increased-according to SMM research, the planned rebar output of blast furnace steel mills in July decreased by 2% compared with the actual output in June, and the operating rate of electric furnace plants also dropped by about 11.52% compared with the same period in June.


Figure 2: an overview of the trend of thread factory warehouse from 2016 to now
Source: SMM

In the short term, the fundamentals of rebar are not unusual-the supply side is likely to maintain a small fluctuation at the current level, the demand side continues to be hit by precipitation, the road to rebar accumulation is not over, and steel prices are still in an awkward position of "neither up nor down". However, as more and more regions out of the "rainy season" haze, rush demand released as scheduled, thread fundamentals regained strong support, steel prices are expected to consolidate and continue to start.




คำชี้แจงแหล่งที่มาของข้อมูล: นอกจากข้อมูลที่เปิดเผยต่อสาธารณะแล้ว ข้อมูลอื่นๆ ทั้งหมดได้รับการประมวลผลโดย SMM จากข้อมูลสาธารณะ การสื่อสารกับตลาด และการพึ่งพาแบบจำลองฐานข้อมูลภายในของ SMMข้อมูลเหล่านี้มีไว้เพื่ออ้างอิงเท่านั้น ไม่ถือเป็นข้อเสนอแนะในการตัดสินใจ

หากมีข้อสงสัยหรือต้องการทราบข้อมูลเพิ่มเติม กรุณาติดต่อ: lemonzhao@smm.cn
หากต้องการข้อมูลเพิ่มเติมเกี่ยวกับวิธีการเข้าถึงรายงานการวิจัยของเรา โปรดติดต่อ:service.en@smm.cn
ข่าวที่เกี่ยวข้อง
ออสเตรเลียทบทวนภาษีตอบโต้การทุ่มตลาดเหล็กชุบสังกะสีจากอินเดีย มาเลเซีย เวียดนาม ท่ามกลางข้อกังวลเรื่องสังกะสี
11 Sep 2026 18:30
ออสเตรเลียทบทวนภาษีตอบโต้การทุ่มตลาดเหล็กชุบสังกะสีจากอินเดีย มาเลเซีย เวียดนาม ท่ามกลางข้อกังวลเรื่องสังกะสี
อ่านเพิ่มเติม
ออสเตรเลียทบทวนภาษีตอบโต้การทุ่มตลาดเหล็กชุบสังกะสีจากอินเดีย มาเลเซีย เวียดนาม ท่ามกลางข้อกังวลเรื่องสังกะสี
เมื่อวันที่ 9 กันยายน 2026 ออสเตรเลียได้เริ่มการทบทวนมาตรการตอบโต้การทุ่มตลาดรอบพระอาทิตย์ตกครั้งที่สองสำหรับเหล็กแผ่นเคลือบสังกะสีจากอินเดีย มาเลเซีย และเวียดนาม และแยกต่างหากได้เริ่มการทบทวนมาตรการตอบโต้การอุดหนุนสำหรับการนำเข้าจากอินเดีย การทบทวนครอบคลุมช่วงเดือนกรกฎาคม 2025 ถึงมิถุนายน 2026 โดยคาดว่ารายงานฉบับสุดท้ายจะออกภายในวันที่ 11 กุมภาพันธ์ 2027 เนื่องจากเหล็กเคลือบสังกะสีเป็นภาคการใช้งานปลายทางที่ใหญ่ที่สุดของสังกะสี มาตรการดังกล่าวจึงส่งผลโดยตรงต่อต้นทุนการส่งออกและความสามารถในการแข่งขัน ซึ่งอาจกระทบต่ออุปสงค์สังกะสีในประเทศและห่วงโซ่อุปทานของออสเตรเลีย การคงภาษีไว้จะช่วยคุ้มครองกำลังการผลิตเหล็กและการเคลือบผิวในประเทศได้ระดับหนึ่ง ขณะที่การยกเลิกอาจทำให้มีการนำเข้าสินค้าราคาต่ำเพิ่มขึ้นและส่งผลต่อการบริโภคสังกะสีในภูมิภาค ผลลัพธ์สุดท้ายยังขึ้นอยู่กับการวินิจฉัยของหน่วยงานผู้มีอำนาจ
11 Sep 2026 18:30
JCC Hongyuan Copper ทุ่มงบขยายกิจการ 200 ล้านดอลลาร์ ตั้งเป้าเพิ่มกำลังการผลิตเป็น 550,000 เมตริกตันภายในปี 2027
7 Sep 2026 15:43
JCC Hongyuan Copper ทุ่มงบขยายกิจการ 200 ล้านดอลลาร์ ตั้งเป้าเพิ่มกำลังการผลิตเป็น 550,000 เมตริกตันภายในปี 2027
อ่านเพิ่มเติม
JCC Hongyuan Copper ทุ่มงบขยายกิจการ 200 ล้านดอลลาร์ ตั้งเป้าเพิ่มกำลังการผลิตเป็น 550,000 เมตริกตันภายในปี 2027
โครงการขยายกำลังการผลิตแคโทดทองแดง 300,000 ตันต่อปี ของบริษัท JCC Hongyuan Copper ซึ่งเป็นบริษัทในเครือ Jiangxi Copper Corporation ได้เข้าสู่ขั้นตอนการประกาศรับฟังความคิดเห็นล่วงหน้าของรายงานการประเมินผลกระทบสิ่งแวดล้อมเมื่อวันที่ 4 กันยายน ด้วยเงินลงทุนรวมประมาณ 1.416 พันล้านหยวน โครงการมีแผนเริ่มก่อสร้างในเดือนกันยายน 2569 และแล้วเสร็จในเดือนธันวาคม 2570 เมื่อแล้วเสร็จ กำลังการผลิตรวมของ JCC Hongyuan จะเพิ่มจาก 250,000 ตัน เป็น 550,000 ตัน
7 Sep 2026 15:43
เงินเยนแข็งค่า USD/JPY ร่วงต่ำกว่า 159 ท่ามกลางกระแสคาดการณ์การแทรกแซงตลาด
3 Sep 2026 19:00
เงินเยนแข็งค่า USD/JPY ร่วงต่ำกว่า 159 ท่ามกลางกระแสคาดการณ์การแทรกแซงตลาด
อ่านเพิ่มเติม
เงินเยนแข็งค่า USD/JPY ร่วงต่ำกว่า 159 ท่ามกลางกระแสคาดการณ์การแทรกแซงตลาด
[SMM รายงานพิเศษโลหะมีค่า] เงินเยนญี่ปุ่นพุ่งขึ้นอย่างรวดเร็วระหว่างการซื้อขายวันพุธ โดย USD/JPY ร่วงลงต่ำกว่า 159 และปิดลดลง 0.92% ที่ 158.69 กระตุ้นการคาดการณ์เรื่องการแทรกแซงค่าเงินของญี่ปุ่น ดัชนีดอลลาร์ก็ร่วงลงอย่างหนักเช่นกัน โดยสภาพแวดล้อมดอลลาร์ที่อ่อนค่าเป็นปัจจัยหนุนโลหะมีค่า
3 Sep 2026 19:00

