by Stuart Burns on OCTOBER 18, 2016
A recent CRU note shined some useful light on how the reporting of aluminum inventory in China has been distorted by changes in the supply chain between smelters and downstream consumers. Our reporting of primary metal inventory generally measures exchange stocks of ingot, sows and t-bars, and adds in an estimate for off-market stocks held by trade buyers and the reported inventory held by smelters.
It is a process that has generally held us in good stead for decades — with the one glaring omission of off-market stock and finance trade inventory running into millions of tons that we have no visibility on, but that’s another matter! Well add to that, says CRU, the changing nature of the Chinese aluminum manufacturing industry.
China’s Shadowy Aluminum Industry
Lured by cheap coal and, as a result, low-cost power, Chinese smelters have relocated in droves to the north and north east provinces, remote from traditional downstream clients on the east coast.
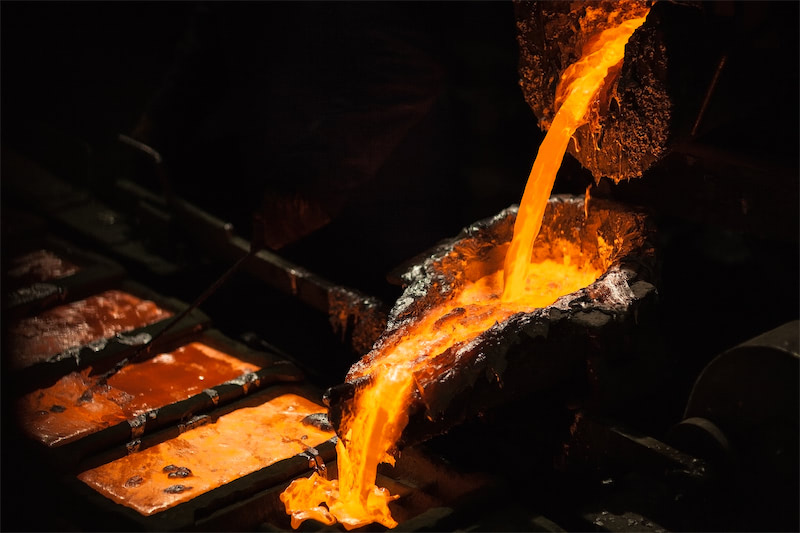
Is the future of aluminum liquid? Source: Adobe Stock/kybele.
Transportation costs are high and can be unreliable, particularly in winter. So, Chinese customers have come to their metal suppliers, relocating cast-house and direct casting facilities adjacent to the smelters. The products they, in turn, produce are higher value and better able to absorb those transportation costs. So far, so good.
The Innovation: Liquid Metal
What’s different about any that? you may ask. Haven’t manufacturers been taking advantage of proximity to suppliers for hundreds of years? Well, taking advantage of that adjacent location supplier and customer dynamic, today, has further cut costs by aligning production so the processors can take liquid metal — from which they make a range of continuously cast (CC) rods, slabs, sheets, and billets — that then go on to be rolled or extruded into downstream products. Indeed, because of the energy savings in not remelting ingot to liquid metal again this production process has direct environmental benefits that Beijing has not been slow to acknowledge and actively support.
According to CRU, liquid metal is expected to become the biggest output form from Chinese smelters in 2016, accounting for 41% of total aluminum production in China. The firm goes on to say other cast-house shape products from Chinese smelters — including billet, slab, foundry alloy, CC rod and CC strip — will account for 21% of total aluminum output in 2016. The proportion of aluminum ingot has decreased significantly over the last 10 years, to 38% from 82% in 2006 and 60% in 2011. Virtually all the new capacity introduced this decade has come in the form of cast-house products and liquid metal rather than ingot.
Inventory That’s Liquid
That makes the measurement of inventory harder if you are only counting ingot, sows and t-bars.
But that is not the only problem. Markets carefully scrutinize national and regional inventory swings, reading into them rises or falls in demand and judgements are made about the relative strength of the markets. CRU warns the shift to more remote smelting locations makes this process less reliable.
For example, in Xinjiang, the smelters have to rely on the railways to ship their metal. However, CRU says the available transport capacity by rail is not always enough. When fruit or cotton needs to be transported to other provinces from Xinjiang, less perishable or lower value products, including aluminum ingot, will simply not get moved. That results in a fall in inventory to consumers in southern or eastern markets, but the inventory drawdown is read by analysts as a rise in demand when, in reality, it is only a transportation bottleneck.
Nowhere has the shortening of the supply chain between smelter and consumer been as widely adopted as it is in China. Large centrally planned smelters such as those in Russia or new, integrated smelter-processor facilities such as those in the Middle East have adopted the same environmentally beneficial and cost-reducing processes but where examples have ranged up to at most one to two hundred thousand tons (and in most case only tens of thousands), in China those numbers are running at some12 million tons. As so often is the case in China, the sheer scale is transformational.