

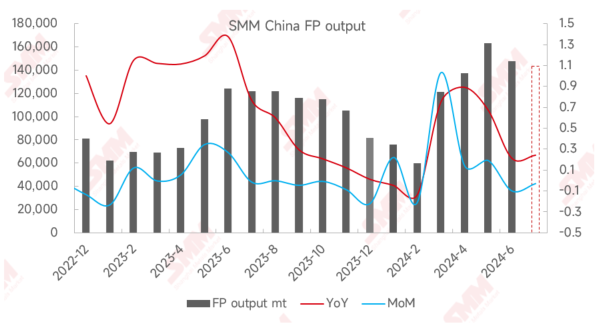
According to the SMM survey, China's iron phosphate output in H1 2024 was 705,200 mt, up 42% YoY. Among them, the output of non-integrated producers was 337,7900 mt, accounting for 47.9% of the total output.
1. The supply-demand pattern in H1 2024 was hard to reverse, with prominent losses
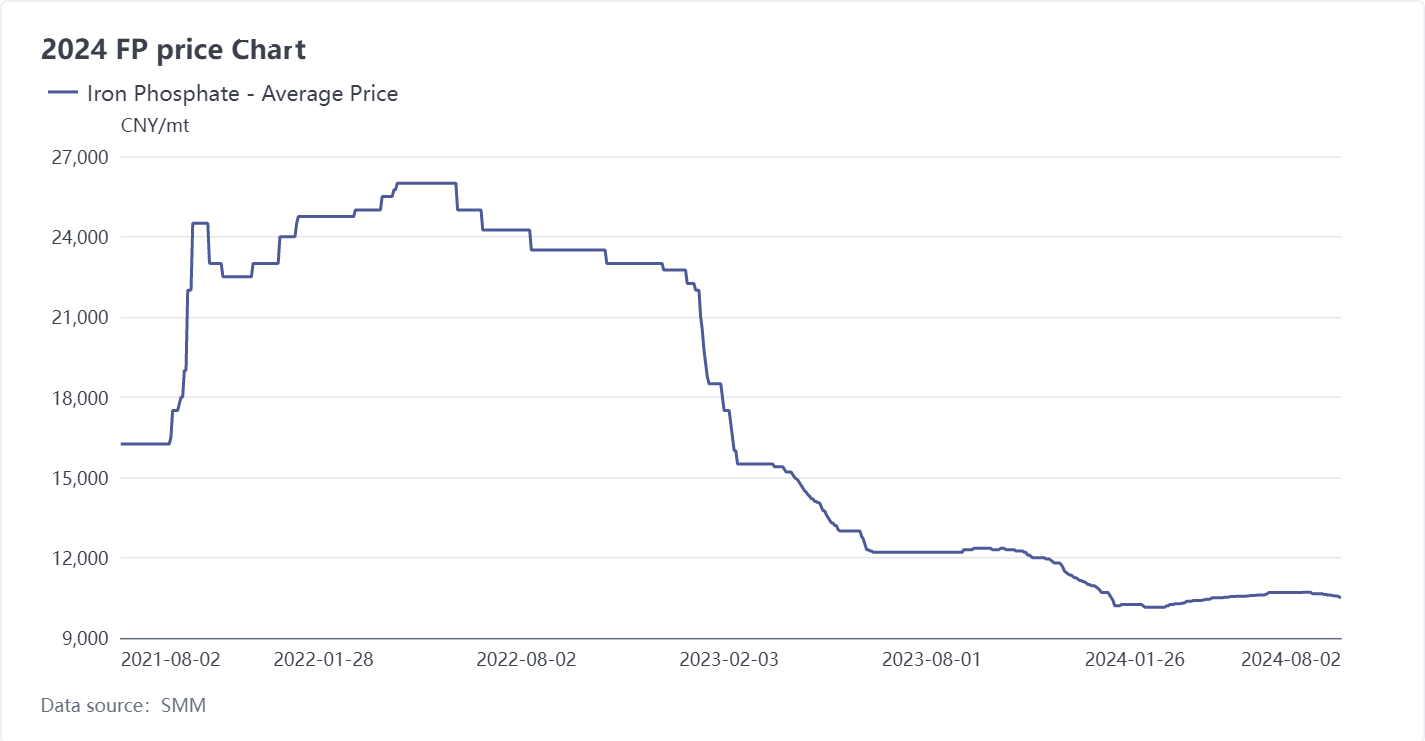
From January to February 2024, in preparation for the CNY holiday in January and the planned holiday in February, some iron phosphate producers advanced their February orders, leading to insufficient production momentum in February. Together with the continuous price suppression by downstream LFP producers, many iron phosphate producers were keen to hold their offers firm, resulting in low production enthusiasm. Although iron phosphate producers tried to negotiate better terms, the results were minimal.
From March to April 2024, the NEV price war began, orders increased, and the operating rate of iron phosphate producers rose, leading to increased market supply. However, during the spring plowing season in March, the demand for phosphate fertiliser surged, driving up the price of phosphate sources. The prices of industrial ammonium and phosphoric acid also rose slightly, and the pressure of rising costs gradually transmitted downstream, but the transmission was still obstructed. Iron phosphate prices only increased slightly, and the loss gap remained. Some iron phosphate producers refused low-price orders to reduce losses, resulting in some idle capacity.
In May 2024, the most unexpected event for iron phosphate producers was the sudden rise in industrial ammonium prices due to a shortage of water-soluble fertiliser supply from Xinjiang. Due to the lack of prior stockpiling, the cost of iron phosphate using the ammonium process soared. Together with good downstream demand, iron phosphate producers were keen to hold their offers firm.
In June 2024, the production and supply of iron phosphate producers significantly decreased, affected by downstream production cuts and destocking at the end of the quarter. Iron phosphate producers reduced production due to cost pressures. The prices of industrial ammonium and phosphoric acid remained stable, keeping the cost of iron phosphate high. However, due to obstructed price transmission, the expected significant price increase did not materialize, and June's production was more conservative compared to April and May.
2. Excess supply of iron phosphate, integrated producers reduce costs through external procurement
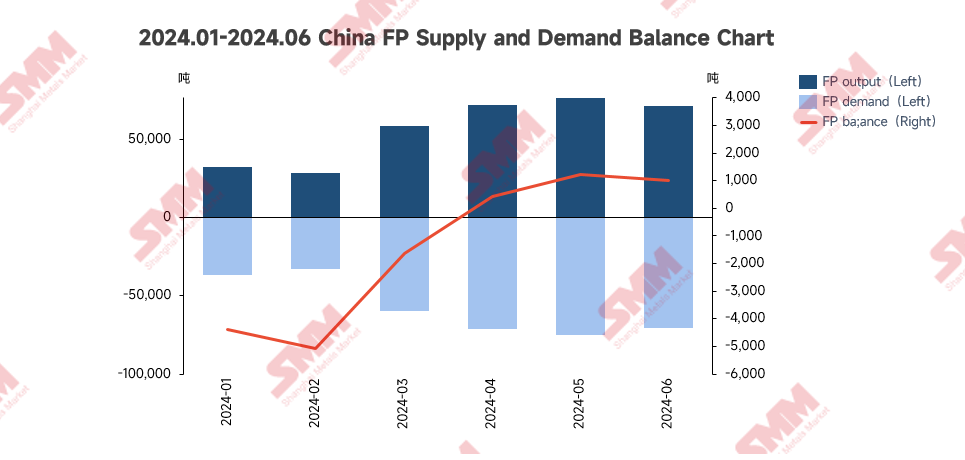
In H1 2024, except for February when production was reduced or halted due to CNY, leading to negative supply-demand balance, the overall supply in other months was excessive, providing conditions for continuous price competition in iron phosphate. Together with high inventory levels, many iron phosphate producers chose to sell at lower prices to increase orders and clear inventory.
Due to the rising prices of phosphoric acid and industrial ammonium in H1, the costs for integrated producers were also high. This led to an increase in the proportion of external procurement by integrated producers, as the cost of externally procured iron phosphate was lower than self-produced, better coping with the low conversion margin of LFP. However, iron phosphate producers became the lowest in the food chain.
3. Market dynamics are ever-changing, only those involved know the true situation

In the iron phosphate market, Hunan Yuneng and Wanrun, as integrated producers, maintained a leading market share, especially Hunan Yuneng, whose dominant position remained unchallenged. Guizhou Deanda operated flexibly, with iron phosphate products available for both internal use and external sale. Tongling Nanyuan made significant progress in production share in H1. Yuntianhua performed outstandingly in H1, leveraging its advantages. Iron phosphate producers selling externally faced a shrinking market, and it was wise to control production, reduce operating rates, and minimize losses.
Iron phosphate, being specifically designed for LFP, has a single downstream flow. The main downstream product of upstream phosphate sources is agricultural fertiliser, with pricing power mainly in the hands of upstream phosphate chemical companies. This puts iron phosphate producers in a difficult position, squeezed by both upstream and downstream. Although the issue of excess supply is hard to resolve, high-quality products are still in demand.
New entrants in the iron phosphate industry often compete with low prices due to their unstable foundation. However, LFP producers consider both cost and product quality, and new iron phosphate producers or models entering the supply system usually require 3-6 months for validation, a relatively long cycle.
Additionally, in H1 2024, a new force entered the iron phosphate sector, with recycling companies gradually focusing on the treatment of waste iron slag and starting to release recycled iron phosphate capacity. However, the quality of recycled iron phosphate is currently uneven and has not yet stood the test of time.
The competition in the iron phosphate market will remain fierce in H2, and profitability has become a luxury in a loss-making market environment. Many iron phosphate producers are considering production cuts or halts. This is common among phosphate chemical companies with resources, as the iron phosphate business is a "side business" for large phosphate chemical groups. If the "side business" continues to lose money, it is better to focus on the main phosphate chemical business to ensure profitability. However, iron phosphate producers without resource advantages and with a single business focus can only choose to fight to the end, striving to break through and persist.
The industry will gradually move towards concentration, with capacity clearing being brutal. Companies will compete in terms of capital, technology, management, and resources, undergoing long-term tests. In the thorny paths, they will find a way out, and looking back, they will realize that they have overcome numerous challenges.



