

On June 26, the 2024 SMM LME Asia Week- Global Metals and New Energy Market Outlook and Supply Trends wrapped up in the Hong Kong Special Administrative Region of China!
This forum invited futures experts and industry leaders to discuss global economic development, a review and outlook of the 2024 metals market, and hot topics such as the NEV supply chain, overcapacity, and resource scarcity.
At the forum, Xu Ying, Chief Macro Strategy Analyst at Dongzheng Futures, stated that the strong rise in precious and base metals prices has ended, and prices are expected to be under pressure in Q3. However, the long-term upward trend in gold has begun, indicating a shift in the commodity price center.
Wang Yancheng, head of SMM's London office, stated that the renewable energy sector, including electric vehicles, Li-ion batteries, solar and wind energy, and related infrastructure investments, will drive demand for base metals. The global economic recovery will support China's export, which may bring more demand. Overseas investments by Chinese companies will also boost some exports.
Ruan Yinan, Managing Director of the Trading Department at Jinli Industrial (Singapore) International Co., Ltd., stated that the fundamentals are not optimistic, and the demand for solar panels is slowing down. Meanwhile, the real estate sector is still recovering. Personally, I am not very confident about the demand for aluminium in H2.
Xu Tianyi, Head of Business Development for China at Open Mineral, stated that there is a shortage of copper concentrate supply, especially with the rapid growth of the smelting sector in China, which may also appear in Indonesia next year. This mismatch has actually led to very low TCs, a situation that will last at least until Q4 unless some smelters cut production to rebalance the market, bringing spot TCs back to $30, $40, or $50, so that they can be in a more favorable position when negotiating TCs next year.
Michelle Leung, Head of Metals, Minerals, and Sustainable Business for Asia at Bloomberg, stated that according to Bloomberg Intelligence, copper prices are at $8,600/mt. As long as this level is maintained, miners may achieve a more promising investment return rate, at least 15%, to justify long-term investments. It is expected that from 2023-2028, secondary aluminium will account for 70% of the new demand for aluminium.
Jack Shang, Co-Head of Metals and Mining Research for Pan-Asia at Citi Research, stated that Citi Bank predicts that LME copper prices will end Q3 close to $9,500/mt. If this price is reached, it will be a window period or buying opportunity.
Albert Miao, Head of Energy Transition and Commodity Research for China at Macquarie, stated that currently, both the battery materials and solar industries are facing similar situations with overcapacity, with solar overcapacity being more severe. Supply side, as companies cannot maintain profits and cash flow for several quarters, supply has decreased.
Damian Pearson, Head of Investment Business at EMR Capital, stated that considering the positive trends in the European and US markets, I believe there are opportunities for overseas expansion, as local governments are keen to establish domestic battery supply chains.
Muchtazar, Head of ESG at Nickel Industries Limited, stated that the Indonesian Ministry of Investment is not entirely focused on the ESG aspects of mineral production, but it requires responsible mining and transparency in the mineral value chain. The EU battery regulations are similar. Personally, I believe that the main raw materials for batteries are minerals, such as nickel. More importantly, the assessment covers the entire mineral production value chain.
Li Zhongning, Director of ESG and Sustainable Development at Huayou Cobalt, stated that when the electric vehicle market uses high-nickel batteries, nickel resources are limited. Finally, companies in Indonesia have adopted new technologies to process waste and low-nickel, high-cobalt waste, producing valuable nickel and cobalt for the electric vehicle industry, thus reducing costs.
Guest Speeches
Speech: Global Economic Reshaping - Addressing Geopolitical Tensions and Supply Chain Disruptions
Speaker: Xu Ying, Chief Macro Strategy Analyst at Dongzheng Derivatives Research Institute

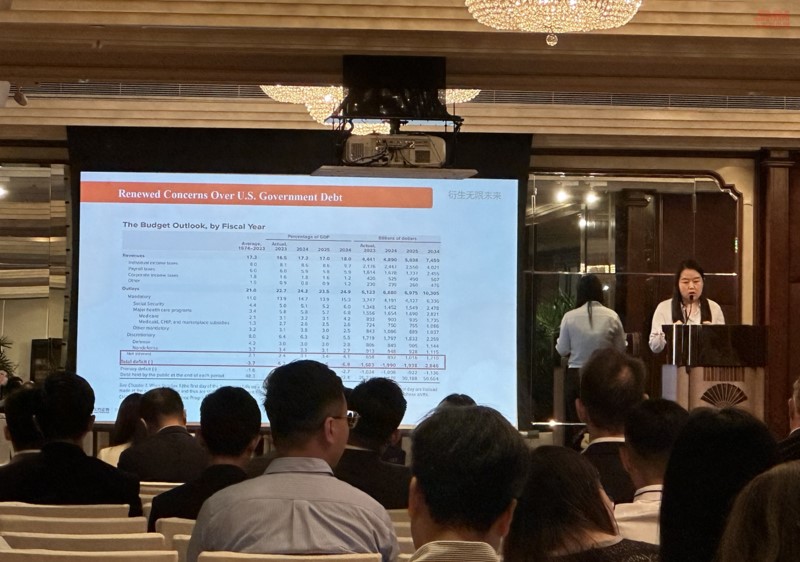
Continuous Improvement in Financial Conditions
• Apart from geopolitical risks and the rise of trade protectionism, the rise in major asset prices is largely due to the current loose liquidity environment.
• After the US Fed slowed the pace of interest rate hikes in Q4 2022, the National Financial Conditions Index (NFCI) in the US remained loose, along with China's continued loose monetary policy, proving this point.
Major Asset Price Outlook
Currency: The US dollar index remains relatively strong, with no turning point in sight. Non-dollar currencies continue to face pressure.
Commodity: The strong rise in precious and base metals prices has ended, and prices are expected to be under pressure in Q3. However, the long-term upward trend in gold has begun, indicating a shift in the commodity price center.
Speech: 2024 Metals Market Review and Outlook
Speaker: Wang Yancheng, Head of SMM's London Office

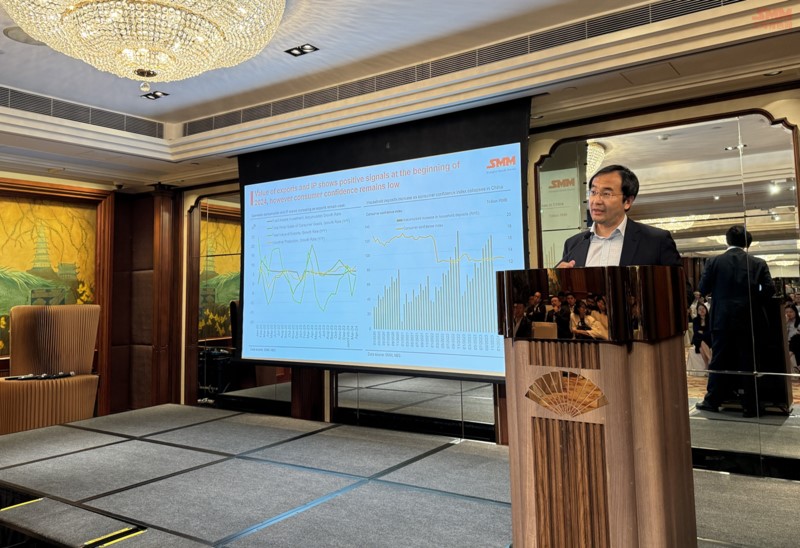
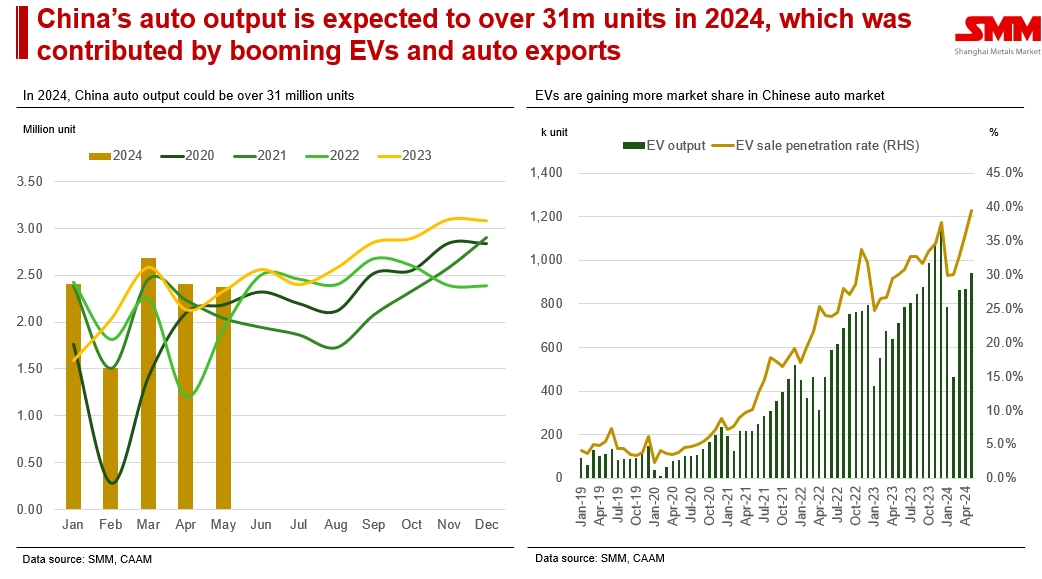
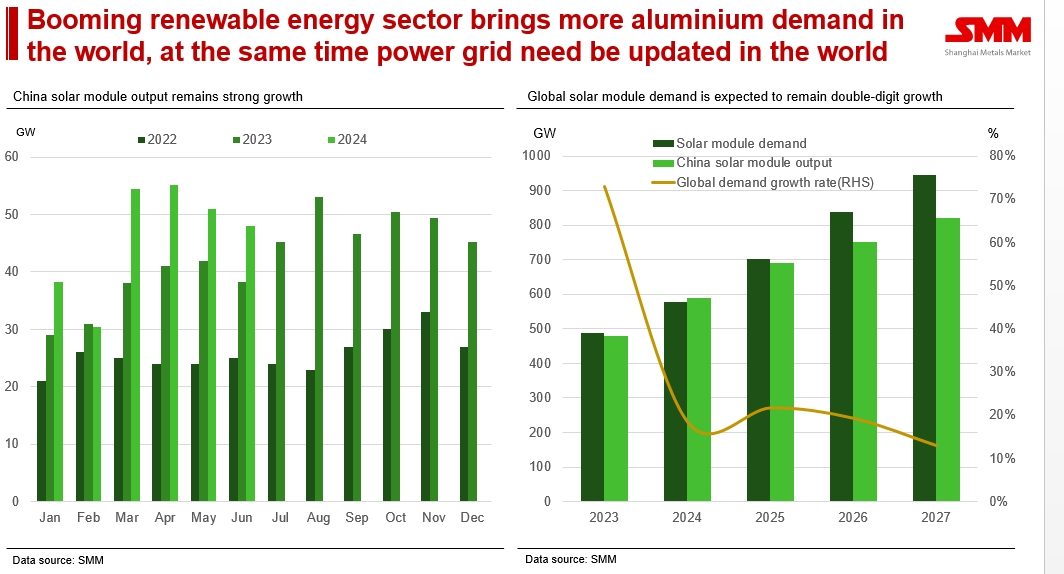
The booming renewable energy sector has brought more demand for aluminium globally, while the global power grid also needs upgrading.
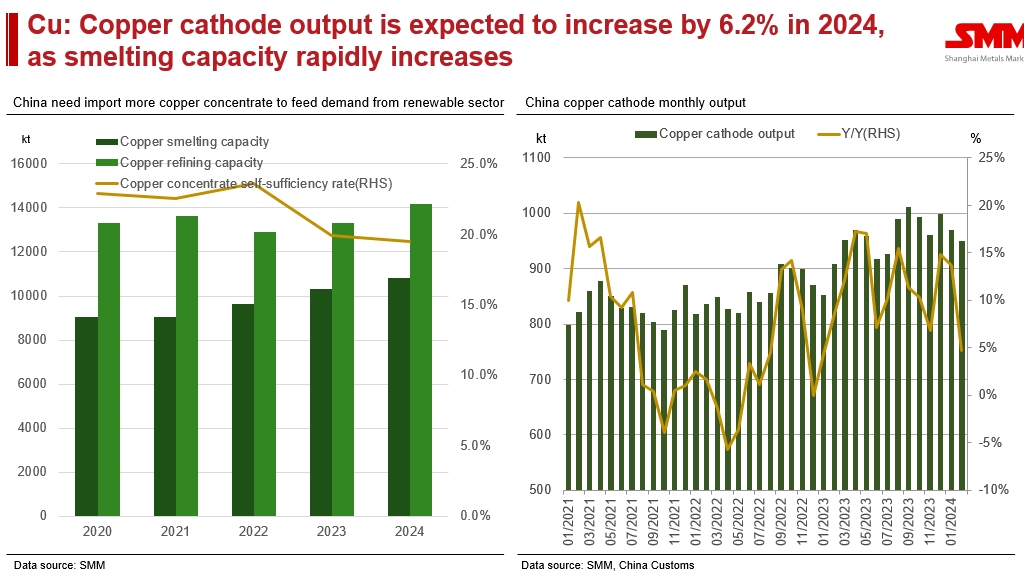
Copper: With the rapid increase in smelting capacity, copper cathode output is expected to grow by 6.2% in 2024.
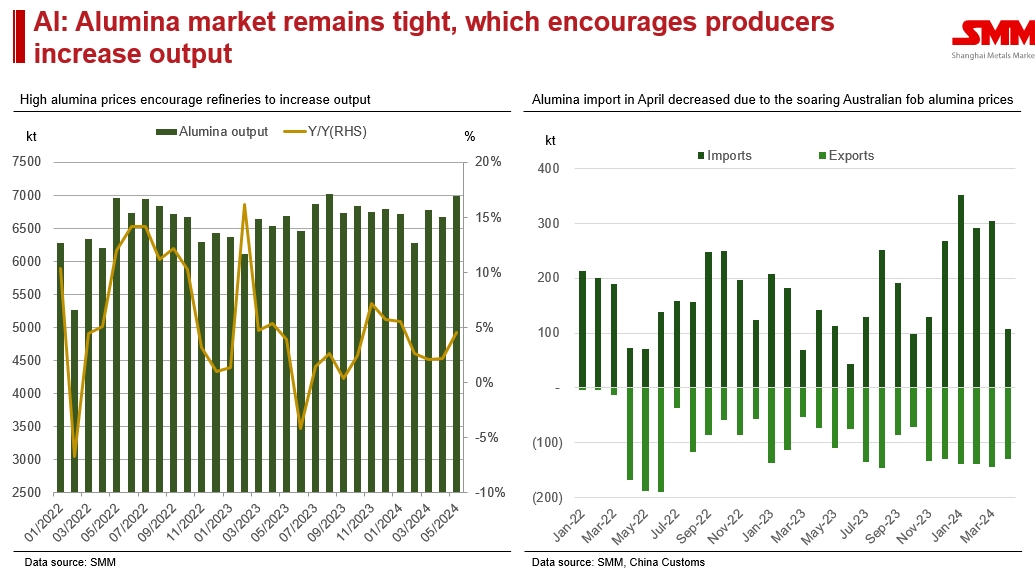
The alumina market remains tight, prompting producers to increase output.
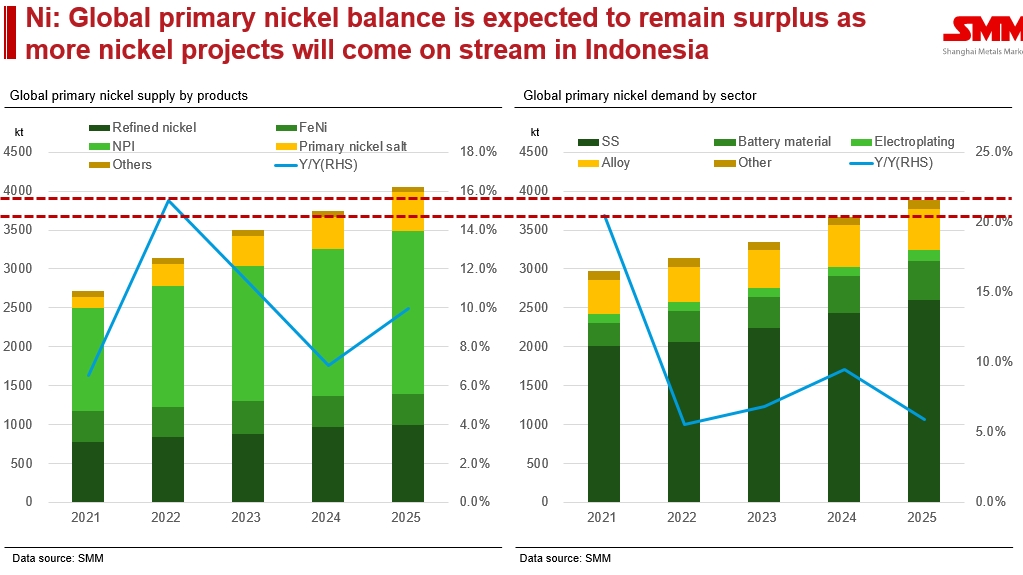
With more nickel projects coming online in Indonesia, global primary nickel is expected to remain in oversupply.
Key Points
China's government has set a GDP growth target of about 5% for 2024. The government has introduced new policies to stimulate economic recovery, such as detailed rules for subsidies on trade-ins. These trade-ins and equipment upgrades require more new policy support. It is believed that the government will introduce more mandatory standards to force the replacement of low-efficiency industrial equipment. More policies may be released after the third plenary session of the CPC Central Committee in July, which may bring more demand for base metals.
The renewable energy sector, including electric vehicles, Li-ion batteries, solar and wind energy, and related infrastructure investments, will drive demand for base metals, which may offset some of the losses from the weakness in the real estate market. The global economic recovery will support China's export, which may bring more demand. Overseas investments by Chinese companies will also boost some exports.
China's economy still faces unfavourable factors, such as geopolitical issues and trade disputes. In recent years, Chinese companies have been striving to explore emerging markets to mitigate the impact of trade wars. With the real estate market expected to remain weak, boosting domestic consumer confidence will be a challenging task.
Panel Discussion
Topic: Overcapacity and Resource Scarcity in a Geopolitically Challenged World
Moderator:
Wang Yancheng, Head of SMM's London Office
Guests:
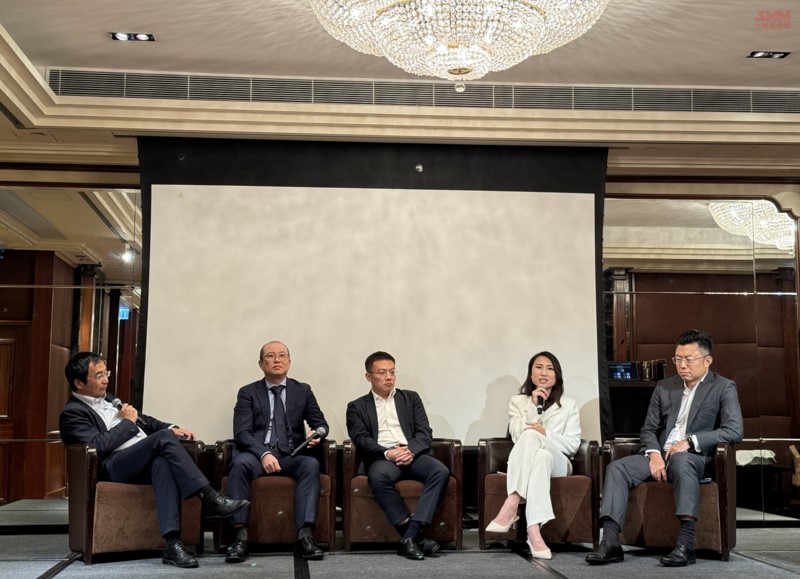
Ruan Yinan, Managing Director of the Trading Department at Jinli Industrial (Singapore) International Co., Ltd.
Xu Tianyi, Head of Business Development for China at Open Mineral
Michelle Leung, Head of Metals, Minerals, and Sustainable Business for Asia at Bloomberg
Jack Shang, Co-Head of Metals and Mining Research for Pan-Asia at Citi Research
Ruan Yinan stated that the fundamentals are not optimistic, and the demand for solar panels is slowing down. Meanwhile, the real estate sector is still recovering. Personally, I am not very confident about the demand for aluminium in H2. The sanctions by the UK and the US on Russia will change the physical flow. Russian metals, which were previously sold in large quantities to Europe, have significantly reduced sales after April. For example, Russian aluminium may be sold at SHFE-based prices, regardless of the price spread between SHFE and LME, and will enter China. Therefore, I believe that the sanctions by the UK and the US on Russia will not have a significant impact on nickel prices but will change the physical flow.
Xu Tianyi stated that there is a shortage of copper concentrate supply, especially with the rapid growth of the smelting sector in China, which may also appear in Indonesia next year. This mismatch has actually led to very low TCs, a situation that will last at least until Q4 unless some smelters cut production to rebalance the market, bringing Spot TCs back to $30, $40, or $50, so that they can be in a more favorable position when negotiating TCs next year. Otherwise, I believe this is disastrous for Chinese smelters. Therefore, some production cuts are expected in Q4. In the foreseeable future, TCs will remain low. Based on the smelters' costs, prices like $40 or $50 are not profitable but also not loss-making.
Michelle Leung stated that according to Bloomberg Intelligence, copper prices are at $8,600/mt. As long as this level is maintained, miners may achieve a more promising investment return rate, at least 15%, to justify long-term investments. It is expected that from 2023-2028, secondary aluminium will account for 70% of the new demand for aluminium. Currently, the proportion of secondary aluminium is very low, only about 20% compared to total demand, but it is expected to rise to 34% in the coming years. Compared to other countries, this proportion is still very low. In the US, this proportion is as high as 65%, and China still has a lot of room for development.
Jack Shang stated that Citi Bank predicts that LME copper prices will end Q3 close to $9,500. If this price is reached, it will be a window period or buying opportunity. Citi Bank stated that they are quite optimistic about the year-end price. For the year-end, next year's Q1, and next year's price forecast, Citi Bank has set it at $12,000, expecting a strong rebound in the next six months.
Topic: Rethinking the 2024 NEV Supply Chain - Balancing China's Position, ESG Concerns, and Aggressive Battery and EV Penetration Rates
Moderator:
Ma Rui, Senior Research Manager for New Energy at SMM
Guests:
Albert Miao, Head of Energy Transition and Commodity Research for China at Macquarie
Damian Pearson, Head of Investment Business at EMR Capital
Muchtazar, Head of ESG at Nickel Industries Limited
Li Zhongning, Director of ESG and Sustainable Development at Huayou Cobalt
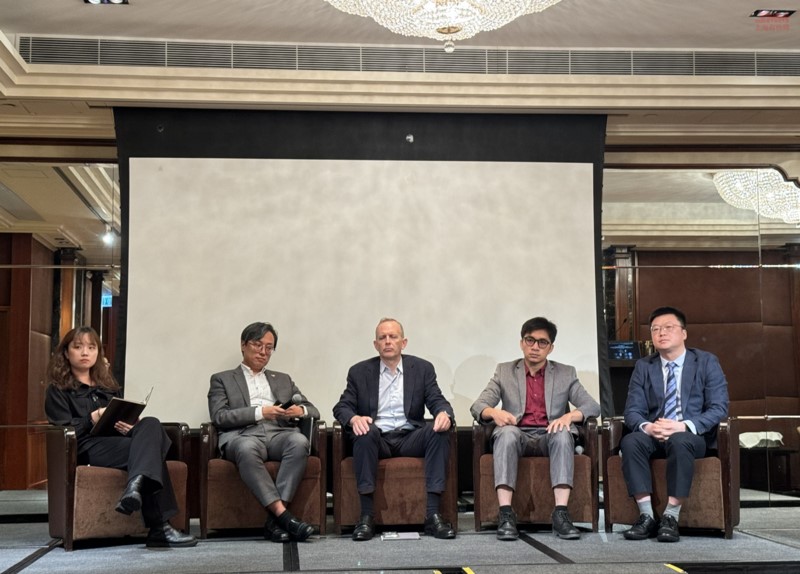
Albert Miao stated that currently, both the battery materials and solar industries are facing similar situations with overcapacity, with solar overcapacity being more severe. Supply side, as companies cannot maintain profits and cash flow for several quarters, supply has decreased; demand side, strong growth is expected in the coming years.Therefore, with the continuous growth in demand, the overcapacity issue in the solar industry may only be temporary. Additionally, technological upgrades can accelerate rebalancing, encouraging most of the industry's supply cuts.
Damian Pearson stated that considering the positive trend in the European and US markets, he believes there are opportunities for overseas expansion. Local governments are keen on establishing domestic battery supply chains. Therefore, there are opportunities to collaborate with Western companies that have technology but lack experience. The US market will be a challenging one, with relatively strict regulations. Europe is more open, but seeking such partners or investments is also challenging.
Muchtazar stated that the Indonesian Ministry of Investment does not entirely focus on the ESG aspects of mineral production, but it requires responsible mining and transparency in the mineral value chain. The EU battery regulations are similar. He believes that the main raw materials for batteries are minerals, such as nickel. More importantly, the assessment covers the entire mineral production value chain. Therefore, they must assure their European customers that their minerals are produced in a low-carbon, sustainable manner.
Li Zhongning stated that when the electric vehicle market uses high-nickel batteries, nickel resources are limited. Finally, Indonesian companies adopted new technologies to process waste and low-nickel, high-cobalt waste, producing valuable nickel and cobalt for the electric vehicle industry, thus reducing costs. The company's RKEF and projects can reduce carbon emissions, using a large number of hydropower facilities to generate electricity, providing 75% of the power for each project. The company also needs to handle tailings and has made progress.
Thank you all for your attention and support to this forum, and see you next time!



