SMIC, a leading semiconductor manufacturing company in mainland China, set off a wave of craze yesterday, especially in Hong Kong stocks. SMIC rose 8% yesterday afternoon. There are two main reasons for this.
First, insiders confirmed that after months of negotiations and efforts, SMIC had been granted permission to buy relatively advanced equipment from US semiconductor equipment manufacturers, which are reported to be used mainly in mature process processes. This was listed as an export restriction enterprise by the US Department of Commerce in October last year (the US Department of Commerce's Bureau of Industry and Security sent a letter to some US suppliers. Some US equipment, accessories and raw materials exported to SMIC will be further restricted by US export controls, and they must apply for an export license beforehand before they can continue to supply SMIC.) A major progress has been made through negotiations.
Secondly, at a press conference held by the Information Office of the State Council yesterday, Tian Yulong, chief engineer and spokesman of the Ministry of Industry and Information Technology, said that the Chinese government attaches great importance to the integrated circuit industry. It has issued policies to promote the high-quality development of the integrated circuit industry and the software industry, and comprehensively optimized and improved the relevant environmental policies for the high-quality development of the chip and integrated circuit industry. Especially in the upper reaches of the industrial chain, such as semiconductor manufacturing, process and equipment, it has been the focus of policy and financial support. This news for the local wafer foundry leader SMIC, is obviously a positive, played a role in promoting the rise of its shares.
SMIC's permission to buy US semiconductor equipment is more noteworthy than the press conference of the State Council Information Office. It was speculated at the end of last year that with the inauguration of the new president of the United States, his policy towards Chinese enterprises in the high-tech field will be partially adjusted, and semiconductor equipment is a very important part of Sino-US high-tech trade. This time, SMIC's approval may reflect previous speculation from one side. There are signs of further easing in semiconductor trade between China and the United States.
In fact, in the past two years, the Sino-US semiconductor industry seems to be "opposing", but with the passage of time and the development and changes of the industrial environment, the meaning of "unification" of the two major semiconductor markets is getting stronger and stronger, and there are many manifestations, such as government policy support and capital investment to the semiconductor industry, the relationship between supply and demand of semiconductor manufacturing equipment, chip manufacturing, especially the characteristics of the process are highly similar. And the dependence of chip supply and demand market.
Convergence of semiconductor support policies
In recent years, the Chinese government has been vigorously supporting the local semiconductor industry, especially for the semiconductor manufacturing and equipment industry in the upper reaches of the industrial chain. Only by laying a solid foundation can the chip industry continue to innovate and develop, and the tax cuts for relevant enterprises will continue to be strengthened. With regard to the reduction of enterprise income tax for integrated circuit enterprises since the profit-making year, these policies have given a great impetus to the development of enterprises; the development of the chip industry also depends on talents, so in terms of talent reserve and personnel training, the government and the state have taken a series of measures, the most eye-catching one is to set the integrated circuit major as a first-tier discipline in relevant colleges and universities. In addition, it is the launch of the "big fund". At present, the first phase has basically completed its mission, and the second phase is playing a role in the local semiconductor market.
Under the circumstances that China's semiconductor industry policy continues to play a role, the United States also sees the necessity of adjusting the government's industrial policy, rather than relying on the single role of the market. Since 2020, SIA has proposed several proposals to the government, suggesting that the corresponding new policies for the semiconductor industry, especially in terms of government funds, need more investment. For example, SIA put forward a $37 billion proposal to support the industry, of which $5 billion is used as federal subsidy to build a new semiconductor factory, which will be jointly owned and operated by the government and private enterprises. In addition, 15 billion US dollars will be set aside as comprehensive subsidies for the states, mainly as subsidies to attract investment and set up factories, and 17 billion US dollars for research and development. Last year, SIA hoped to win bipartisan support for the bill, when Republican and Democratic senators also enacted a bill that would allocate $110 billion for technology spending, including semiconductor research. Recently, the new president of the United States, Joe Biden, signed an executive order seeking 37 billion dollars for legislation to strengthen the chip manufacturing industry in the United States.
High dependence of semiconductor equipment
In the past year, due to the increasing imbalance between global chip supply and demand and a serious shortage of production capacity, the pace of global wafer expansion has been accelerated and transferred to the upper reaches of the industrial chain, mainly manifested in the popularity of the semiconductor equipment sales market, especially in the North American semiconductor equipment market, where sales have repeatedly reached record highs on a monthly basis, reaching a peak in January this year. According to the January equipment market data released by SEMI, North American-based semiconductor equipment manufacturers achieved sales of $3.04 billion in January 2021, with monthly revenue of $3 billion for the first time, up 13.4% from $2.68 billion in December 2020 and 29.9% higher than $2.34 billion in January 2020. It can be seen that the current semiconductor equipment market environment is very good, no manufacturer is willing to miss this money-making outlet.
The above equipment is mainly sold to three major markets, namely, Taiwan, mainland China and South Korea. In the face of such a huge market demand, especially in mainland China, the demand for equipment is increasing year by year, and there is still a lot of room for expansion in the future. At the same time, the export restrictions on semiconductor equipment in the United States are obviously something that major equipment manufacturers in North America do not want to see, and for a long time last year, they submitted supply applications one after another to seize this period of global chip capacity shortage.
At the same time, while seeking permission to buy semiconductor equipment in the United States, wafer factories in mainland China are also in need of other options. Japan, the world's second largest supplier of semiconductor equipment, has naturally become the main target. Chinese wafer makers are snapping up second-hand chip manufacturing equipment, pushing up equipment prices in Japan's secondary market, Nikkei reported. Japanese second-hand equipment dealers say the price of equipment is up 20% from last year. All of China's doing this is mainly because these older devices are not subject to the restrictions of the United States. A source from Mitsubishi UFJ Leasing Finance said: "nearly 90 per cent of the second-hand equipment will be shipped to China."
A market source said that some Chinese wafer factories are buying the equipment even if they are not using it immediately.
The pursuit of Japanese semiconductor equipment is also stimulating American semiconductor equipment manufacturers. This time, SMIC has obtained permission to purchase US-related equipment, which also reflects the pragmatic side of the relevant US policy, that is, in the face of the huge demand of the Chinese mainland market, it is more in line with commercial interests to adapt to the dependence of the two major markets of supply and demand. Of course, this is just the beginning, for both supply and demand, there is still a lot of work to be done in the future. after all, advanced process equipment is still prohibited from being sold to wafer factories in mainland China.
Chip manufacturing is similar
The chip manufacturing industry in the United States is very developed and has a relatively long history, while the chip manufacturing industry in mainland China is still in the stage of growth and relatively young, and there seems to be a big difference between the two. But if you take a closer look, there is a high degree of similarity between the two markets.
The IDM industry in the United States is very developed and has a long history, but the wafer industry is not very strong. In addition to the lattice core, there are few other foundry factories with limited scale and little market influence. Whether it is IDM, or wafer foundry, most American companies are good at mature processes, but seldom dabble in advanced processes. Especially manufacturers such as TI, ADI, Skyworks and Qorvo, whose products are mainly analog chips, rarely use advanced processes. Intel is one of the few manufacturers in the United States to mass-produce more advanced process chips on a large scale, but compared with several major fabs in Taiwan and South Korea, Intel's advanced process also lags behind.
The wafer factories in mainland China, which are in the growth stage, are also based on mature processes. In this regard, the two major markets of China and the United States have a high degree of similarity, as shown in the following figure.
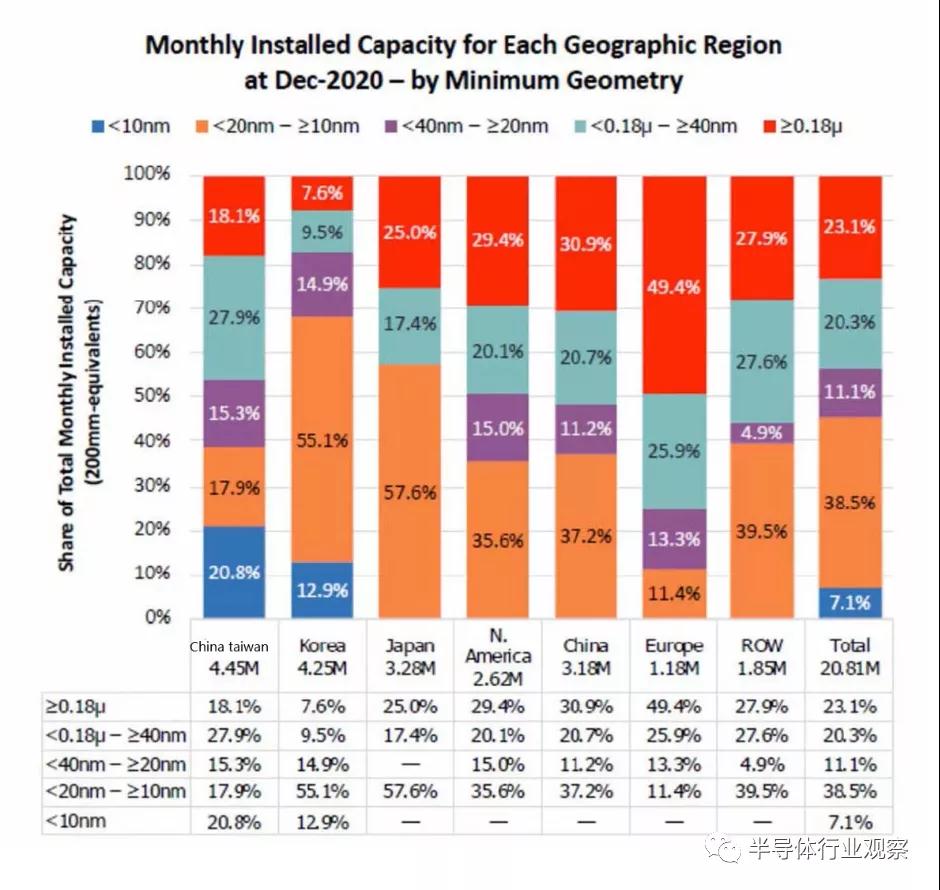
As can be seen from the picture, among the seven regions in the world, the proportion of five types of processes in the United States and mainland China is the most similar, or even the same, while the differences in other regions are obvious.
Because of this, there are more similarities in the industrial chain of chip manufacturing in the United States and mainland China, as well as similar or the same needs, such as similar demand for semiconductor materials and equipment, similar chips manufactured and similar applications. Based on this, the two major chip manufacturing markets in China and the United States will reflect a more and more "close" relationship, and there may be more and more similarities in the demand for each link of the industrial chain and the coordinated development of the industry.
Conclusion
From the aspects of semiconductor industry policy, supply and demand of semiconductor equipment, and chip manufacturing process, this paper introduces the similarity and close relationship between Chinese and American semiconductors. This increasingly "unified" state adds more and more imaginative space to the original "opposing" relationship. With the growth and growth of China's chip manufacturing industry, and the gradual maturity and improvement of the local supply chain, the relationship between the semiconductor industry policy, supply and demand of semiconductor equipment, and chip process technology in the two major markets of China and the United States may become closer.