

SMM Steel May 19, this week's mainstream market resources are expected to arrive at 96000 tons, 22000 tons less than last week.
Table 1: comparison of arrival in mainstream markets
Source: SMM Steel
Shipments continued to decline this week, mainly affected by the price difference between the north and the south and strong terminal demand in the north. According to SMM statistics, recently, the price of Lecong is only 60mur80 yuan / ton higher than that of Tangshan, while the price in Shanghai is 20 yuan / ton lower than that of Tangshan, the price difference between the north and the south has not yet been opened, and the resources in the north do not have the conditions to go south, so that the volume of goods from Shanghai and Lecong from the market continues to be on the low side. At the same time, the terminal demand in the north is strong, and most steel mills have increased the amount of terminal direct supply, resulting in a reduction in circulation resources in northern markets such as Tianjin.
Shanghai market: since the end of March, the arrival volume has remained low, the overall supply is tight, and with the recovery of demand, regional inventory is gradually reduced, coupled with a larger part of the resources in the market, the market negotiable resources are relatively limited, so traders are more willing to sell and push up the price, and the spot price rises accordingly.
In addition, it was expected that the delivery resources of Hengrun and Shagang and Angang would greatly suppress the market, but at present, Hengrun's resources are not entirely invested in the East China market, and some of them flow to the north and other regions. In addition, with regard to the delivery resources of Shagang and Angang, the early stage has been reflected in the price, and the subsequent impact on the market price is very limited, so it is expected that under the support of the continued lack of delivery and strong demand, the overall price still shows an upward trend. However, due to the recent pull up too fast, terminal procurement wait-and-see impact, short-term spot prices will be slightly adjusted.
Figure 1: comparison of arrival volume and spot price in Shanghai market
Source: SMM Steel
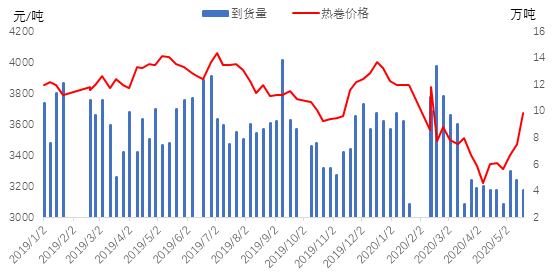
Lecong market: similarly, as can be seen from the chart below, since the end of March, the arrival volume of the market has been on the low side, coupled with the decline in the production of hot coils at Wangang, and the relative reduction of resources sent to Lecong, so the overall market supply continues to be tight. At the same time, the terminal demand has warmed up, the purchase volume has increased, and the regional inventory has gradually declined. Under the influence of the superimposed price difference between the north and the south, it is difficult for traders to get the goods, so their willingness to sell price increases gradually, and the spot price rises accordingly.
In addition, the risk point for South China now is that there is already a small profit space for selling volumes, and some traders with high inventories and tight funds may choose to sell some goods at low prices, somewhat suppressing spot prices in the market. But at present, it is understood that the total amount of this part is not expected to be large, the number of goods sold by superimposed traders is less, and the shipment at low prices is also more cautious, so there is only a small correction in the short term. The follow-up is expected to show an upward trend under the support of less arrival, until the price difference between the north and the south opens and the amount of resources arriving increases.
Figure 2: comparison between the volume of goods from the market and the spot price
Source: SMM Steel
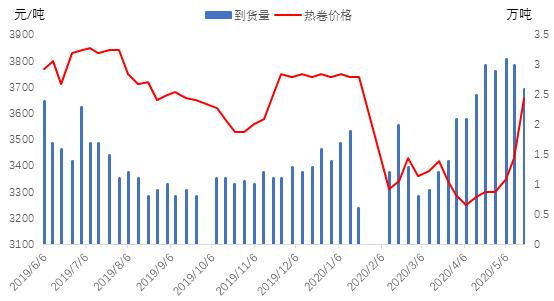
Tianjin market: the volume of goods in this market is still on the high side compared with the normal level. At the same time, according to SMM, the follow-up steel mills such as Baotou Steel and Shougang will gradually reach the market, at which time the pressure on the supply side of the market will further increase, and the spot price will be suppressed accordingly. As a result, the view of the market's anaemic late rally remains the same.
Figure 3: comparison of arrival volume and spot price in Tianjin market
Source: SMM Steel



