

Summary of key points:
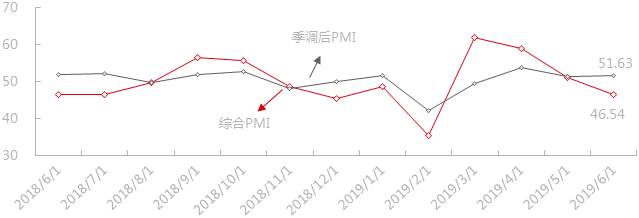
In June 2019, the PMI composite index was 46.54, down 4.56 from the previous month and 0.03 from a year earlier. After the quarterly adjustment, the composite index was 51.63, up 0.25 from the previous month and down 0.38 from the same period last year.
Generally speaking, this month's PMI composite index before the quarter adjustment is lower than 50, after the quarter adjustment is higher than the 50 withered glory line, the downstream industry as a whole into the off-season, affected by seasonal factors in some industries showed a significant decline. This month's composite production index was 44.20, down 7.61 from the previous month, up 0.46 from the same period last year, with the exception of transportation infrastructure and shipbuilding industries, showing varying degrees of decline this month. The new orders index was 43.90, down 8.26 from the previous month and up 0.19 from a year earlier. Machinery, cars and household appliances in the manufacturing industry are affected by the off-season and show a downward trend, while the construction industry is seriously affected by Rain Water, high temperature and other factors. The transport infrastructure industry continues to improve and is optimistic about the future affected by government policies. Orders for new ships in the shipbuilding industry have increased, which is not affected by trade frictions between China and the United States.
SMM Purchasing Manager Index for downstream Iron and Steel Industry
The PMI index of iron and steel in June looked at the following points:
The PMI composite index of the construction industry was 46.56, down 5.66 from the previous month and 1.07 from the same period last year. After the quarterly adjustment, the composite index was 50.33, down 0.77 from the previous month and 1.35 from the same period last year. This month, the industry as a whole weakened, production and orders have declined to varying degrees, the arrival of the off-season superimposed high temperature, Rain Water, resulting in a reduction in engineering volume in parts of North and South China. Seasonal factors affect the procurement enthusiasm of downstream enterprises, raw material procurement volume and inventory are significantly reduced.
The PMI composite index of the machinery industry was 43.85, down 5.24 from the previous month and up 0.29 from the same period last year. After the quarterly adjustment, the composite index was 53.67, up 2.01 from the previous month and down 0.18 from the same period last year. This month, the industry as a whole weakened, production and new orders are affected by the off-season, of which the decline of agricultural machinery is the most obvious, 6, 7, August is the off-season of agricultural machinery, most agricultural machinery plants have a certain psychological preparation, the market mentality is more peaceful. Construction machinery and heavy machinery are affected by the off-season shrinkage, individual enterprises continue to be affected by Sino-US trade frictions, the loss of a small number of overseas customers, but the proportion is not high. Machinery manufacturers are pessimistic about the overall expectation of follow-up market demand. Affected by the off-season, most enterprises choose to purchase on demand, raw material inventory is low.
The PMI composite index of the automobile industry was 46.39, down 1.74 from the previous month and up 0.27 from the same period last year. After the quarterly adjustment, the composite index was 53.45, up 0.56 from the previous month and down 0.93 from the same period last year. The weakening of new orders is obvious, in addition to the reasons for the downturn in the domestic market, on the one hand, affected by the sixth emission standards, on the other hand, affected by the reduction in export orders. Due to continued poor sales, the pressure on commodity inventory has increased. Most enterprises are pessimistic about future expectations and purchase on demand according to the quantity of orders and production to avoid risks.
The PMI index of the shipbuilding industry was 53.30, up 0.16 from the previous month and down 1.89 from the same period last year. After the quarterly adjustment, the composite index was 51.88, down 0.2 from the previous month and 2.10 from the same period last year. This month, the shipbuilding industry continued to maintain a good trend of new ship orders increased, bulk carriers mainly, large ships slightly reduced. The purchase volume and inventory of raw materials have been affected by production and orders, while the industry has been less affected by trade frictions between China and the United States.
The PMI composite index of the home appliance industry was 47.59, down 2.46 from the previous month and up 1.19% from the same period last year. After the quarterly adjustment, the composite index was 53.24, up 1.92 from the previous month and 0.36 from the same period last year. Affected by the off-season as a whole, production and new orders have declined in varying degrees, and export orders of some enterprises have continued to shrink due to trade frictions between China and the United States. This month's poor sales continued, finished goods inventory rose, the industry is generally pessimistic about next month's market expectations, procurement volume decreased, raw material inventory decreased significantly.
The PMI composite index of the transportation infrastructure industry was 54.36, up 3.04 from the previous month and 8.32 from the same period last year. After the quarterly adjustment, the composite index was 56.44, up 4.56 from the previous month and 7.85 from the same period last year. The industry as a whole continued to improve, production and new orders showed a certain degree of growth. The purchase quantity and inventory of raw materials have increased. Stimulated by government policy, project financing is unbound, most enterprises are optimistic about the follow-up market. [SMM Steel]
For more information, please contact Li Tian, SMM Iron and Steel Industry Research Department.
Contact: + 86 21 51666875
Contact email: tannli@smm.cn



