[SMM Annual Report] Global Nickel Likely to be Oversupplied in 2023-2026E

Publicado: Jan 10, 2023 17:33 (GMT+8)
In 2023, in addition to the impact of the aforementioned delays in the commissioning of some capacity, the demand from the new energy industry will stimulate the production and ramp-up of the upstream producers.

SHANGHAI, Jan 10 (SMM) - 2022 is another year that has witnesses the nickel price turmoil. In March 2022, nickel prices soared to a record high. In the second quarter, the prices were on a downward trend and returned to the fundamentals due to COVID-19 outbreak and the macro factors. In the middle and late third quarter, steel mills were expected to resume their production owing to the sharp drop in stainless steel supply earlier, pushing up the short-term stainless steel output and the nickel demand. In addition, the new energy industry mushroomed in the third quarter. The operating rates of battery companies grew amid the improvement of orders, the low inventory of precursor companies, the rapid expansion of the leading battery producers, etc. Nickel demand gained strong support from the new energy industry. As a result, the prices rallied from lows.

In terms of the fundamentals in 2022, the US Fed continued to raise the interest rates to temper inflation. The global economy showed signs of recession from time to time, and overseas consumption, especially in European countries, slumped, while nickel consumption performed relatively well. The two major downstream markets, the stainless steel and new energy industries both maintained positive growth, and the nickel demand in the latter burgeoned by more than 30% year-on-year. Nickel demand from the military alloy sector grew apace, while that from the electroplating sector performed poorly during the year.

In 2023, the market may witness a significant supply surplus of primary nickel, especially the NPI.  Besides, the refined nickel supply will also be in surplus. Nonetheless, the same scenario is unlikely happen to nickel sulphate in 2023 because of its capacity mismatch. The Indonesian government’s potential export tax hike on nickel products may, on the other hand, affect the rhythm of NPI production and cause oversupply. The global economy will not be optimistic in 2023. Under the influence of factors on the fundamentals and macro front, nickel prices will fluctuate wildly with a high probability and will trend lower amid the expected supply surplus.
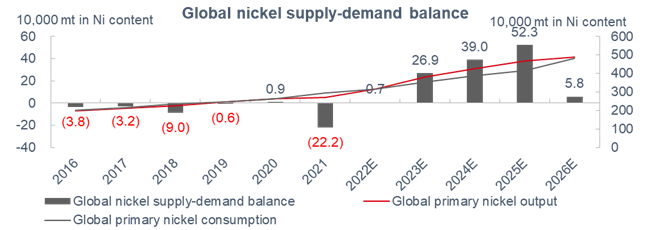
In 2022, the global primary nickel consumption is expected to be 3.14 million mt in Ni content, up 6.9% YoY. The supply will add 15.9% YoY to 3.148 million mt in Ni content. The global primary nickel surplus will reach 8,000 mt in Ni content. The market should see no supply surplus if the downstream restocking demand had been taken into account. In 2022, nickel supply has been relatively tight, which is mainly caused by the lower-than-expected growth of supply.  The commissioning of Indonesia NPI slowed down, and some production lines were switched to produce high-grade nickel matte, reducing the expectations of NPI oversupply to some extent. Meanwhile, the nickel salt output, restricted by the mismatch between converted battery-grade nickel sulphate capacity and the raw material types, failed to surge, thus the market supply was in deficit for most of the year.

In 2023, the surplus is expected to expand further. In addition to the impact of the aforementioned delays in the commissioning of some capacity, the demand from the new energy industry will stimulate the production and ramp-up of the upstream producers. In 2023, the total supply will reach 3.808 million mt in Ni content while the demand will be 3.54 million mt in Ni content, resulting in a supply surplus of 269,000 mt in Ni content, which is mainly contributed by NPI supply since there will be multiple new NPI production lines put into production. SMM predicts that SMM #1 refined nickel prices will move between 143,000-178,000 yuan/mt, with an average of 160,500 yuan/mt.


Declaração sobre a Fonte de Dados: Com exceção das informações publicamente disponíveis, todos os demais dados são processados pela SMM com base em informações publicamente disponíveis, comunicação de mercado e com base no modelo de base de dados interna da SMM. São apenas para referência e não constituem recomendações para a tomada de decisão.

Para quaisquer perguntas ou para obter mais informações, entre em contato: lemonzhao@smm.cn
Para mais informações sobre como aceder aos nossos relatórios de investigação, entre em contato:service.en@smm.cn
Notícias Relacionadas
【Flash | Sobretaxas de tubos com molibdênio da Tubacex em outubro são mistas】
02 Oct 2026 10:52 (GMT+8)
【Flash | Sobretaxas de tubos com molibdênio da Tubacex em outubro são mistas】
Leia mais
【Flash | Sobretaxas de tubos com molibdênio da Tubacex em outubro são mistas】
A Tubacex divulgou suas sobretaxas de liga para tubos de outubro. Em euros, o 316/316L acabado a quente/frio caiu de €5,07/€5,59 por kg (€5.070/€5.590 por tonelada) para €5,05/€5,56 por kg (€5.050/€5.560 por tonelada). Materiais com alto teor de Mo, acima de 2,5%, recuaram de €5,26/€5,79 para €5,23/€5,76 por kg. As sobretaxas para 2205 e 2507 permaneceram inalteradas, enquanto o 254 SMO subiu de €9,64/€10,62 para €9,67/€10,65 por kg. Análise da SMM: a maioria dos tubos com Mo ficou estável ou ligeiramente em baixa, enquanto o 254 SMO avançou, indicando repasse de custos diferenciado entre as classes.
02 Oct 2026 10:52 (GMT+8)
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
02 Oct 2026 10:50 (GMT+8)
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
Leia mais
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
O mercado de sucata de aço inoxidável da Índia seguiu direções distintas na semana encerrada em 1º de outubro. Os preços domésticos da sucata 304 recuaram ligeiramente, acompanhados pelas ofertas de importação, enquanto os preços da 316 permaneceram estáveis tanto no mercado interno quanto no de importação. A queda dos preços do níquel na LME pesou sobre o sentimento para a 304, e os compradores limitaram-se às necessidades imediatas, com o ritmo de negociações desacelerando durante o período festivo. A oferta restrita limitou o potencial de queda para a 316. Nas aquisições, os prazos de processamento reduzidos após a flexibilização, pelo governo, das exigências do Certificado de Inspeção Pré-Embarque (PSIC), somados aos custos adicionais de importação, continuaram a limitar a flexibilidade das usinas. Algumas usinas estão avaliando tarugos, placas e ferro-gusa níquel (NPI) como alternativas à sucata para gerenciar os custos de insumos. Em uma perspectiva mais ampla, a proposta da UE de restringir as exportações de resíduos metálicos para a Índia sob seu novo Regulamento de Transferências de Resíduos (WSR), se adotada, reduziria ainda mais as opções de importação de sucata da Índia. No curto prazo, a sucata 304 enfrenta leve pressão de baixa caso o níquel permaneça fraco, enquanto a 316 deve se manter firme enquanto a oferta continuar restrita. Os desdobramentos do PSIC e a economia relativa de tarugos e NPI serão fatores-chave a observar.
02 Oct 2026 10:50 (GMT+8)
【Flash | Metallus aumenta componente de sobretaxa de molibdênio de outubro para aço 300M】
02 Oct 2026 10:47 (GMT+8)
【Flash | Metallus aumenta componente de sobretaxa de molibdênio de outubro para aço 300M】
Leia mais
【Flash | Metallus aumenta componente de sobretaxa de molibdênio de outubro para aço 300M】
Metallus definiu suas sobretaxas de matéria-prima de outubro para o período de 1º a 30 de outubro. O componente de molibdênio para o aço 300M subiu 0,52%, para US$ 15,176/cwt, cerca de US$ 334,57/t de aço, ante US$ 15,098/cwt, ou US$ 332,85/t. A sobretaxa total listada aumentou 1,03%, para US$ 45,054/cwt. A sucata subiu para US$ 17,750/cwt, enquanto a sobretaxa de energia separada para barras e tubos caiu de US$ 1,296/cwt, cerca de US$ 28,57/t, para US$ 0,050/cwt, ou US$ 1,10/t.
02 Oct 2026 10:47 (GMT+8)

