[ni-Co-Li Summit] there are four major results of the extensive development of the new energy industry chain. Investment needs to be considered from these aspects.

Publicado: Jul 13, 2020 17:24 (GMT+8)

SMM7 March 13: at the 2020 (Fifth) China International Nickel-Cobalt-Lithium Summit Forum and China International Conference on New Energy Lithium Materials held by SMM, Hu Jian, vice president of SMM, explained the opportunities and challenges faced by the new energy industry. He said that China has completed overtaking around the corner in the context of lack of resources and has become a pearl in the global new energy industry chain. The global new energy industry chain is characterized by medium concentration of ore and battery end, relatively scattered smelting and material end industries in the middle position, low gross margin, overcapacity and so on.

At present, the results of the extensive development of China's new energy industry chain include four aspects:

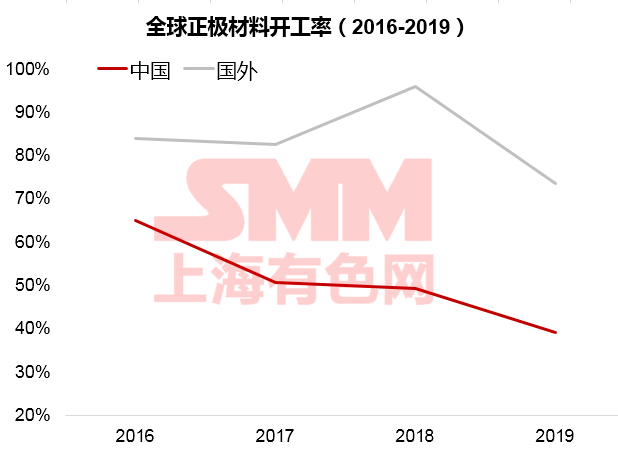
1. Capacity expands quickly and there is a rapid surplus. With the rapid expansion of production capacity, China has rapidly become a major producer of smelting products and battery materials in the world, but the capacity utilization rate has been much lower than that of foreign countries for a long time.
2. The capital investment is large but the return is not high. Take the nickel sulfate industry as an example, except for a few head companies, many companies invest a large amount of money, but their operating income is low.

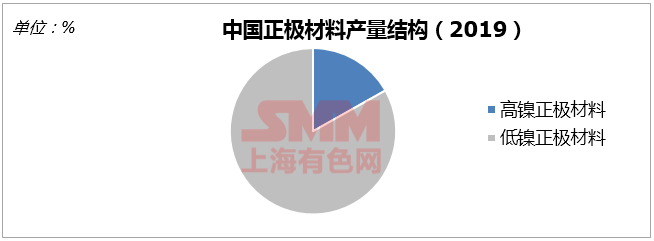
3. The product range is complete but the structure is not excellent. Although China has a wide variety of cathode materials, the proportion of high-nickel materials with higher technical barriers is still much lower than that of Japan and South Korea.
4. Get into trouble because of a weak sense of crisis. Some enterprises ignore the law of market development, invest blindly and expand production, resulting in economic losses.

The direction of cautious investment

Cost leadership to gain competitive advantage: enterprises can reduce the overall cash cost by investing in raw materials and forming large-scale.
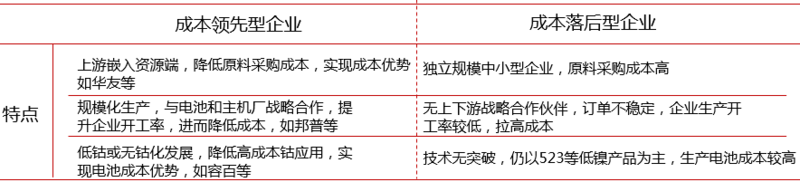
The integration of industrial chain has become a trend: the development trend of ternary materials and ternary precursors is obvious. In order to enhance their own competitiveness, manufacturers prefer the integrated cooperation of industrial chain.
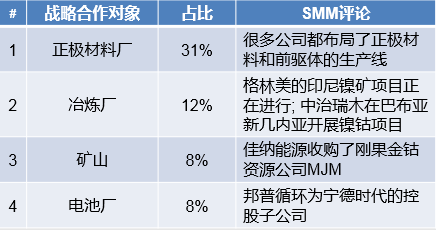
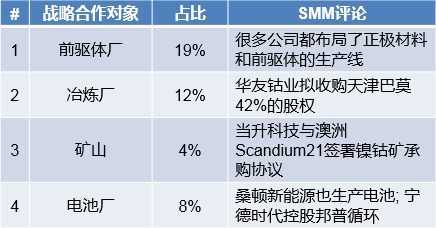
The future will be the competition between the industrial chain and the industrial chain: the future competition is not the competition between enterprises, but the competition between the industrial chains.

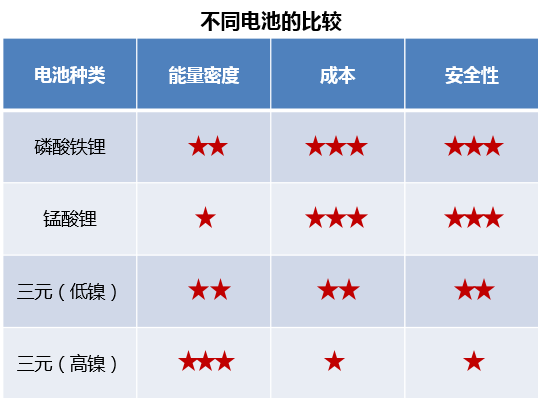
Technology drive leads the development direction: take the power battery as an example, the current ternary and lithium iron phosphate compete with each other, give play to their respective advantages in their respective areas of expertise, and occupy a certain market share respectively. The high nickelization of ternary materials can not only reduce the application of high-cost cobalt, reduce the cost and increase the energy density, but also make great progress after solving the safety problem. solid-state batteries and other batteries such as manganese-rich lithium-based batteries have better energy density and safety performance, which will lead the new direction of power batteries after the realization of large-scale commercial production.
R & D expenses are an important guarantee for the long-term operating advantages of materials enterprises. Ternary precursors and materials enterprises usually invest 3% of their business income in the year. 6% of their operating income is invested in R & D expenses.

Usually, the output of the enterprise is proportional to the R & D cost. Among the precursor enterprises, Greenmei has the highest R & D cost and the largest output; Xiamen tungsten and Hunan fir have higher R & D costs and smaller output, mainly because there are many kinds of products, and the precursors are not their main products.

The investment requirement of ternary materials on R & D cost is slightly higher than that of precursors. Greenmei, Xiamen Tungsten and Hunan Cunninghamia lanceolata have the highest R & D investment, and these enterprises operate at least two kinds of cathode materials.

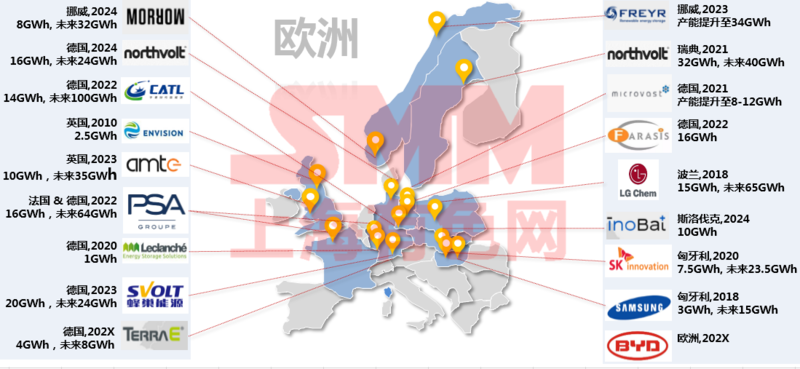
Homeopathic layout wins future opportunities: according to incomplete statistics, the future project of European lithium battery plant is expected to put into production of 250GWH in 2020tel 2025, and its long-term production capacity will further reach near 500Gwh. At present, the production capacity of ternary and precursors in Europe is only less than 100000 tons, which is far from enough to meet the needs of expanding the production of a large number of batteries. will they go to Europe for investment or export in the future?
Scan the code to apply to join the SMM industry communication group:

Declaração sobre a Fonte de Dados: Com exceção das informações publicamente disponíveis, todos os demais dados são processados pela SMM com base em informações publicamente disponíveis, comunicação de mercado e com base no modelo de base de dados interna da SMM. São apenas para referência e não constituem recomendações para a tomada de decisão.

Para quaisquer perguntas ou para obter mais informações, entre em contato: lemonzhao@smm.cn
Para mais informações sobre como aceder aos nossos relatórios de investigação, entre em contato:service.en@smm.cn
Notícias Relacionadas
【Flash | Sobretaxas de tubos com molibdênio da Tubacex em outubro são mistas】
02 Oct 2026 10:52 (GMT+8)
【Flash | Sobretaxas de tubos com molibdênio da Tubacex em outubro são mistas】
Leia mais
【Flash | Sobretaxas de tubos com molibdênio da Tubacex em outubro são mistas】
A Tubacex divulgou suas sobretaxas de liga para tubos de outubro. Em euros, o 316/316L acabado a quente/frio caiu de €5,07/€5,59 por kg (€5.070/€5.590 por tonelada) para €5,05/€5,56 por kg (€5.050/€5.560 por tonelada). Materiais com alto teor de Mo, acima de 2,5%, recuaram de €5,26/€5,79 para €5,23/€5,76 por kg. As sobretaxas para 2205 e 2507 permaneceram inalteradas, enquanto o 254 SMO subiu de €9,64/€10,62 para €9,67/€10,65 por kg. Análise da SMM: a maioria dos tubos com Mo ficou estável ou ligeiramente em baixa, enquanto o 254 SMO avançou, indicando repasse de custos diferenciado entre as classes.
02 Oct 2026 10:52 (GMT+8)
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
02 Oct 2026 10:50 (GMT+8)
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
Leia mais
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
[SMM Flash de Aço Inoxidável] Preços de sucata de aço inoxidável na Índia divergem: 304 recua com o níquel, enquanto o 316, escasso, se mantém firme
O mercado de sucata de aço inoxidável da Índia seguiu direções distintas na semana encerrada em 1º de outubro. Os preços domésticos da sucata 304 recuaram ligeiramente, acompanhados pelas ofertas de importação, enquanto os preços da 316 permaneceram estáveis tanto no mercado interno quanto no de importação. A queda dos preços do níquel na LME pesou sobre o sentimento para a 304, e os compradores limitaram-se às necessidades imediatas, com o ritmo de negociações desacelerando durante o período festivo. A oferta restrita limitou o potencial de queda para a 316. Nas aquisições, os prazos de processamento reduzidos após a flexibilização, pelo governo, das exigências do Certificado de Inspeção Pré-Embarque (PSIC), somados aos custos adicionais de importação, continuaram a limitar a flexibilidade das usinas. Algumas usinas estão avaliando tarugos, placas e ferro-gusa níquel (NPI) como alternativas à sucata para gerenciar os custos de insumos. Em uma perspectiva mais ampla, a proposta da UE de restringir as exportações de resíduos metálicos para a Índia sob seu novo Regulamento de Transferências de Resíduos (WSR), se adotada, reduziria ainda mais as opções de importação de sucata da Índia. No curto prazo, a sucata 304 enfrenta leve pressão de baixa caso o níquel permaneça fraco, enquanto a 316 deve se manter firme enquanto a oferta continuar restrita. Os desdobramentos do PSIC e a economia relativa de tarugos e NPI serão fatores-chave a observar.
02 Oct 2026 10:50 (GMT+8)
【Flash | Metallus aumenta componente de sobretaxa de molibdênio de outubro para aço 300M】
02 Oct 2026 10:47 (GMT+8)
【Flash | Metallus aumenta componente de sobretaxa de molibdênio de outubro para aço 300M】
Leia mais
【Flash | Metallus aumenta componente de sobretaxa de molibdênio de outubro para aço 300M】
Metallus definiu suas sobretaxas de matéria-prima de outubro para o período de 1º a 30 de outubro. O componente de molibdênio para o aço 300M subiu 0,52%, para US$ 15,176/cwt, cerca de US$ 334,57/t de aço, ante US$ 15,098/cwt, ou US$ 332,85/t. A sobretaxa total listada aumentou 1,03%, para US$ 45,054/cwt. A sucata subiu para US$ 17,750/cwt, enquanto a sobretaxa de energia separada para barras e tubos caiu de US$ 1,296/cwt, cerca de US$ 28,57/t, para US$ 0,050/cwt, ou US$ 1,10/t.
02 Oct 2026 10:47 (GMT+8)


