SMM4 28: the morning non-ferrous market fell, only Shanghai aluminum rose. Crude oil prices tumbled again yesterday as global storage space shrank further. WTI futures for June delivery tumbled 24.56 per cent to close at $12.78 a barrel. Copper mines are still affected by the outbreak, with news that Freeport company (Freeport) 's El Abra copper mine in Chile said on Monday that it would cut copper processing by 40 per cent and cut jobs as global copper prices plummeted during the coronavirus pandemic. The mine said it would reduce the amount of copper ore processed from 110000 tonnes a day to 65000 tonnes a day. The El Abra copper mine, owned by Freeport, produced a total of 180 million pounds of copper in 2019. Shanghai nickel low open shock, although the current steel plant production remains normal, the fundamentals are OK, but the improvement in downstream demand is limited, the good news is not obvious, in the long run, if the stainless steel price is not effective, for the raw material Nife to continue to push the price will also have greater difficulties, and consumption continues to be lacklustre, nickel prices are still stimulated by macro news.
Black followed by falling oil prices, iron ore fell relatively large, down 1.16%. Thread demand continues to improve, the market shipment condition is obviously better than the previous situation, the steel plant production thread power is full. However, the current East China market for the late demand rise space is small, and the supply side is still increasing expectations, the overall market mentality is more rigorous. Some steel mills in East China and North China have replenishment demand, which provides some support for the spot market price. And the mainstream low-grade ore prices are relatively strong, steel mills prefer high performance-to-price ratio of raw materials.
Crude oil fell 3.41% in the previous period. Us crude oil futures extended the previous session's decline on Tuesday on fears of a global shortage of crude oil storage space and concerns among investors that demand would only slowly pick up after controls on Xinguan pneumonia were gradually relaxed. Us crude oil futures fell 8.37 per cent, or $1.07, to $11.71 a barrel. The contract tumbled 25% on Monday. Brent crude oil futures fell 2.45 percent, or 49 cents, to $19.50 a barrel. The contract fell 6.8% on Monday.
Close at noon

As of 11:30, HKEx had added US dollar-denominated small metal contracts:

Today's stock
Copper: today, Guangdong electrolytic copper spot contract rose 250 ~ 260, the average price fell 40%; wet copper rose 200 ~ 210, the average price fell 40%. The average price of electrolytic copper fell 410 yuan / ton to 42545 yuan / ton, and the average price of wet copper fell 410 yuan / ton to 42495 yuan / ton. In the spot market, the demand for stock before the downstream festival is weak, coupled with the fact that the holders generally want to cash before the festival, they have taken the initiative to reduce the delivery of rising water one after another. As a result, the rising water continued to decline today, from good copper and flat water copper from 290300 yuan / ton in early trading to 250260 yuan / ton at about 11:00. Although the rate of reduction is relatively large, there are still not many recipients, and the overall transaction is not good. We expect that with the completion of stock, there will be an oversupply the day after tomorrow, and the rising water is expected to continue to decline.
"the second China (Yingtan) Copper Industry Summit and the 15th China International Copper Industry chain Summit"
Lead: Shanghai market Jinsha lead 1448014500 yuan / ton, Shanghai lead 2005 contract price 380400-400 yuan / ton, Wuxi market south 14400-14450 yuan / ton, Shanghai lead 2005 contract 300-350 yuan / ton quotation. Pre-festival spot market circulation supply is still few, part of the quotation for pre-sale, while the downstream pre-holiday stock is limited, the holder quotation rising water slightly down, bulk market transaction activity is not high.
Zinc: the mainstream transaction in Ningbo was 16280-16360 yuan / ton, the ordinary brand rose 170-200 yuan / ton to the 2005 contract, and the price difference between Ningbo and Shanghai ordinary brand narrowed from 60 yuan / ton to 50 yuan / ton yesterday. Today, some of the goods from Guangdong arrived, and the circulation of goods in the Ningbo market increased. In the first period of the morning, the quotation of the holder was basically concentrated around 170 yuan / ton for the May contract, Kirin reported the rising water for the May contract at 170-180 yuan / ton, and in the morning quoted 210 yuan / ton for the rising water in May. However, few transactions were concluded, and Kirin's quotation was quickly reduced to 180 yuan / ton. Huize newspaper raised water by 200 yuan / ton in May, and Yongchang newspaper raised water by 140 yuan / ton in May contract. Overall, the market turnover in the first period was better than yesterday, while the transaction in the second period was higher and worse. Overall, market trading has picked up from yesterday.
The mainstream transaction of zinc ingots in Tianjin market was 16430-17500 yuan / ton, and that of ordinary brands was 16430-16540 yuan / ton. The contract for 2005 rose by 300 yuan / ton to 400 yuan / ton. Compared with Shanghai stock market, Tianjin market rose from 180 yuan / ton to 190 yuan / ton. Today, the Shanghai zinc high shock, the spot market maintains the promotion discount quotation, the quotation is more unified, the ordinary brand lark newspaper in the 05 contract quotation 300 yuan / ton, the red gold newspaper in the 05 contract quotation water 340 yuan / ton, the car macro newspaper in the 05 contract quotes the water 300 yuan / ton, the import KZ quotes in the 05 contract quotes the water 350 yuan / ton, the high price brand Zijin quotes the water 400 yuan / ton to the May contract. Today, zinc prices fluctuate, the spot market to maintain a discount quotation, some zinc ingots in Guangdong have arrived in Tianjin today, but the impact on the overall market is limited, the discount is still high; downstream, prices fell today compared with yesterday, downstream willingness to receive better, some enterprises have pre-festival reserve behavior. On the whole, today's deal is better than yesterday's. The transaction of zinc ingot is near 16380-16490 yuan / ton.
"2020 (15th) lead and Zinc Summit
Updating.
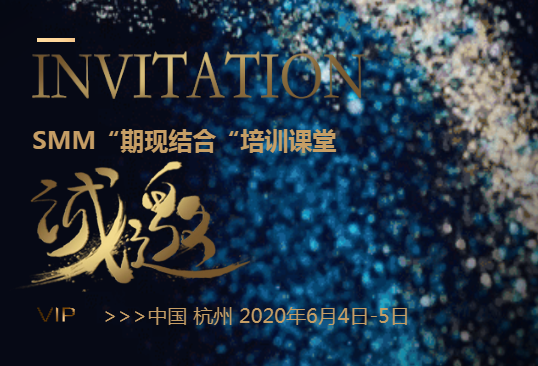
SMM "current combination" training class
Registration contact: Lu Qingping, SMM Iron and Steel Division
Tel: 021-51595781 / 187-1777-4590