SMM Copper Morning Briefing | Wednesday, November 11, 2026
US inflation data came in above expectations, fueling expectations for US Fed interest rate hikes and putting copper prices under pressure. With increased arrivals of imported copper and active selling by suppliers, spot premiums are expected to continue pulling back. Copper prices are likely to consolidate on a subdued note in a narrow range today.
1. Overnight Futures
LME copper opened at $13,860/mt, hit a high of $13,863.5/mt and a low of $13,660/mt, and settled at $13,712/mt, down 1.27%. Trading volume was 19,000 lots and open interest stood at 248,000 lots, down 664 lots, reflecting long liquidation.
The most-traded SHFE copper 2612 contract opened at 105,200 yuan/mt, hit a high of 105,250 yuan/mt and a low of 104,500 yuan/mt, and settled at 104,510 yuan/mt, down 1.29%. Trading volume was 43,000 lots and open interest stood at 192,000 lots, up 75 lots, reflecting short accumulation.
2. News
The Tovaku copper mine project, jointly developed by Codelco and Pucobre, has received environmental approval, clearing a key hurdle for the project's planned start of construction in 2027.
Located in the Antofagasta Region of northern Chile, the project has a total investment of $870 million, a designed mine life of 21 years, and is planned to produce 46,000 mt of copper cathode per year. Construction is expected to begin in H2 2027, with a construction period of three years and production expected to commence in 2030.
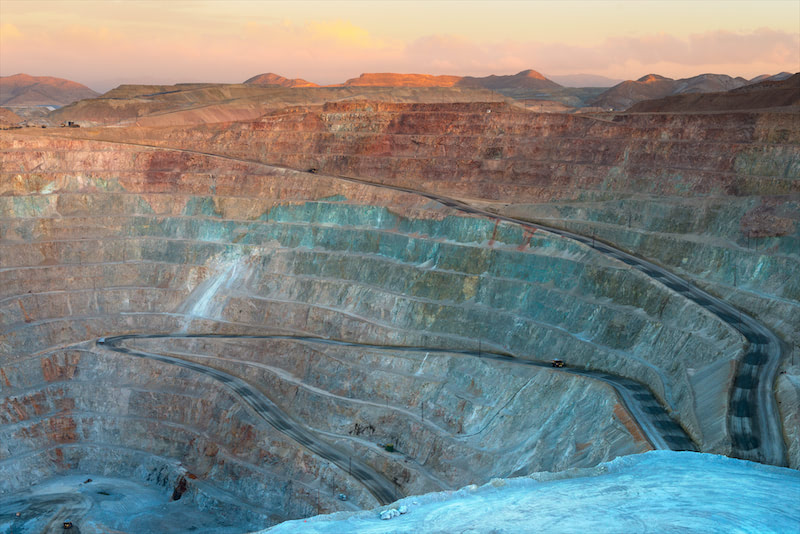
Tovaku is an open-pit copper mine, with Pucobre holding a 60% stake and Codelco holding 40%. The project will use crushing, acid leaching pretreatment, heap leaching, and solvent extraction-electrodeposition processes to produce copper cathode. The project will also include a 193-megawatt (MW) PV power station and a 72.5-km seawater pipeline.
Codelco also said it is considering bringing in more private capital to fund investment projects totaling approximately $34 billion. The company believes that, given current production trends, its 2026 copper production target of 1.34 million mt faces significant challenges.
3. Spot Market
1) Shanghai
Purchasing sentiment was 2.71, down 0.04 MoM; selling sentiment was 3.89, up 0.44 MoM.
On November 10, SMM #1 copper cathode spot prices against the SHFE copper 2611 contract were quoted at premiums of 1,400-2,000 yuan/mt, with an average premium of 1,700 yuan/mt, down 675 yuan/mt from the previous trading day.
The SHFE copper 2611 contract closed the morning session at 107,600 yuan/mt, with the month-to-month Back spread at 1,520-1,690 yuan/mt. The current-month import profit margin ranged from a loss of 50 yuan/mt to a profit of 120 yuan/mt.
The month-to-month Back spread narrowed somewhat but remained at elevated levels overall. Some suppliers showed significantly stronger willingness to sell, continuously lowering quotes to facilitate transactions. As lower-priced cargoes entered the market, the center of spot premiums shifted down rapidly.
Supply side, some imported copper arrived successively, and available market supply increased from earlier periods. Combined with suppliers selling intensively, the tightness in spot supply eased marginally.
Demand side, high copper prices, high premiums, and a high backwardation structure continued to curb downstream purchases. Some processing enterprises adopted measures such as furnace shutdowns for insulation and reduced production line operating rates. New orders were limited, and market trading was sluggish. Shanghai spot premiums are expected to remain under downward pressure today.
2) Guangdong
Procurement sentiment was 2.39, down 0.02 WoW; sales sentiment was 2.47, down 0.03 WoW.
High-quality copper was quoted at a premium of 1,750 yuan/mt, standard-quality copper at 1,500 yuan/mt, and SX-EW copper at 1,440 yuan/mt, all down 100 yuan/mt from the previous trading day.
The average price of #1 copper cathode in Guangdong was 109,465 yuan/mt, and the average price of SX-EW copper was 109,280 yuan/mt, both up 240 yuan/mt from the previous trading day.
Downstream consumption remained weak. Suppliers cut prices for sales promotions, but actual transactions were still poor.
3) Imported copper
The average warrant price was $230/mt, flat from the previous trading day, with a quotation range of $210-250/mt.
The average B/L price was 220 yuan/mt, flat from the previous trading day, with a quotation range of 200-240 yuan/mt.
The average price of EQ copper (CIF B/L) was $125/mt, up $7/mt from the previous trading day, with a quotation range of $120-130/mt. Quotations referenced cargoes arriving from November to mid-December.
4) Secondary copper
At 11:30 on November 10, the futures closing price was 107,600 yuan/mt, down 50 yuan/mt from the previous trading day; the average spot premium was 1,700 yuan/mt, down 675 yuan/mt WoW.
Secondary copper raw material prices rose 100 yuan/mt WoW. The sales sentiment index fell to 2.26, and the procurement sentiment index rose to 1.96. The price difference between copper cathode and copper scrap was 2,576 yuan/mt, narrowing 840 yuan/mt WoW; the price difference between copper cathode rod and secondary copper rod was 1,850 yuan/mt.
As copper cathode premiums pulled back, premiums for tax-inclusive copper scrap raw materials declined in tandem. Secondary copper rod enterprises actively inquired for prices driven by order demand, but traders held back from selling as copper prices pulled back. Transactions were mainly concentrated in the pricing of previously deposited raw materials. In the afternoon, copper prices continued to fall, and some traders stopped taking orders, limiting market transactions.
IV. Inventories
As of November 9, SMM copper inventories in major regions across China fell by about 10 kt WoW from the previous Monday, dropping to slightly above 50,000 mt; compared to about 200,000 mt in the same period last year, inventories decreased by about 140,000 mt.
V. Market summary
Macro: US October CPI rose more than expected. US Fed officials successively released hawkish signals, and market expectations for a 25 bp or even 50 bp rate hike in December strengthened, exerting bearish pressure on copper prices. Qatar has secured at least two weeks of negotiation time, and geopolitical risks between the US and Iran continue to ease.
Supply: Imported copper is arriving successively, suppliers' willingness to sell has increased significantly, available supply has grown, and the tight spot supply situation is easing at the margin.
Demand: High copper prices, high premiums, and wide price spreads between futures contracts continue to curb downstream purchases. Some enterprises have reduced operating rates or halted furnaces to maintain temperature, and both new orders and actual procurement demand remain weak.
Inventory: Copper inventories in major regions nationwide remain at historical lows, providing some support for spot prices, but attention should be paid to a potential inventory inflection point as import replenishment increases.
Price outlook: Rising inflation and expectations for US Fed interest rate hikes are weighing on copper prices. With supply improving at the margin and demand remaining persistently weak, copper prices are expected to consolidate on a subdued note within a narrow range today; spot premiums still have room to pull back further.
This material is for reference only and does not constitute investment advice. Markets involve risk, and decisions should be made with caution.