SMM, November 3: Lead prices fell sharply today. As of the 15:00 close, the most-traded SHFE lead 2612 contract settled at 15,765 yuan/mt, down 345 yuan/mt, or 2.12%, after hitting an intraday low of 15,760 yuan/mt, the lowest level in nearly three months. The futures showed a pattern of declines on position building, with bearish sentiment released in a concentrated manner. However, the spot market was constrained by low inventory, with smelters holding prices firm and holding back from selling, resulting in a clear divergence between futures and spot trends.
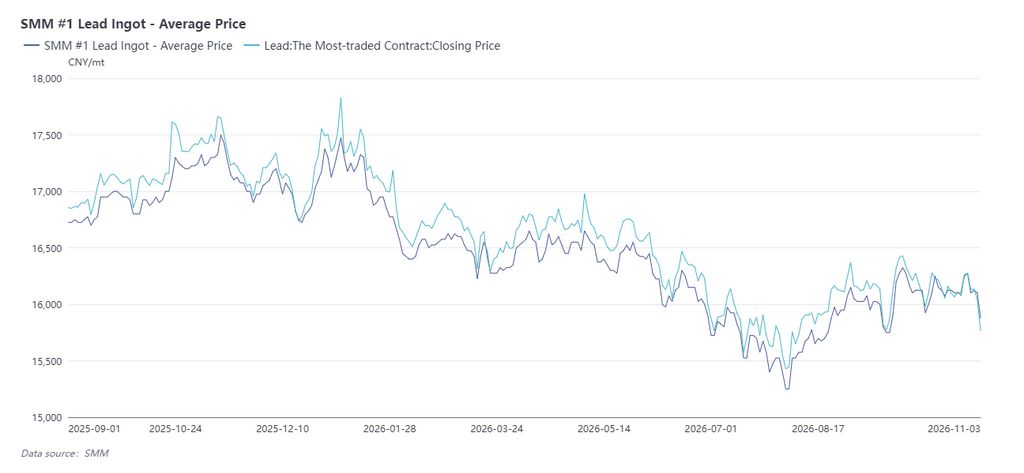
1. Demand Side: Lead-Acid Battery Consumption Weakens, Downstream Operating Rates Pull Back
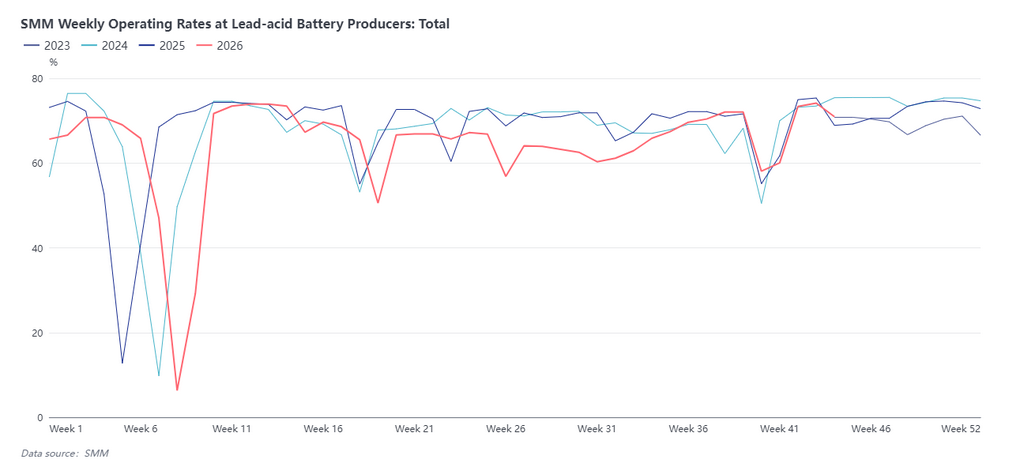
The lead-acid battery market is showing signs of the peak season winding down, with end-user orders weakening. In particular, since October, the suspension of 3C certification for e-bikes has weighed on complete vehicle supporting orders, and some lead-acid battery enterprises have implemented production cuts or holidays. As of October 29, the SMM weekly composite operating rate across lead-acid battery enterprises in five provinces was 70.93%, down 3.22 percentage points WoW. Downstream enterprises have slowed their procurement pace, weakening the rigid demand pull for lead ingot, which has become one of the core factors putting SHFE lead under pressure. However, downstream players have not yet taken extreme measures such as large-scale production cuts or inventory clearing, and demand is experiencing a phased slowdown rather than a cliff-like contraction.
II. Supply side: Imported cargoes continued to flow in, limiting primary lead supply
In late October, imported lead arrived successively and entered the domestic spot market, supplementing market supply to some extent. The latest imported lead quotations against the SHFE 2612 contract were at discounts of 350-300 yuan/mt, ex-warehouse at the port. In addition, customs data showed that China's lead ingot imports (including refined lead, crude lead, alloys, etc.) in September totaled 33,000 mt, and October imports are expected to increase further, with external cargo replenishment bringing potential supply growth.
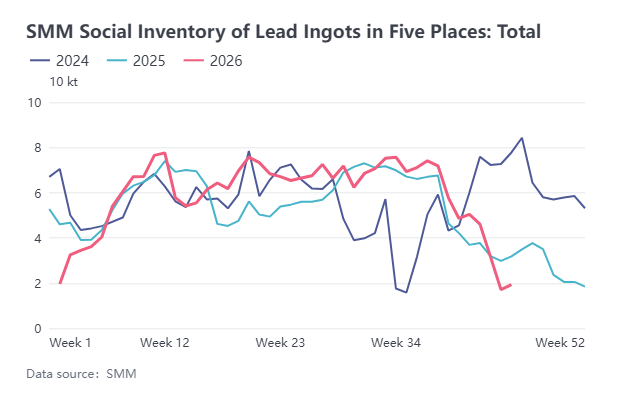
However, lead ingot inventory currently remains at a relatively low level. As of November 2, total SMM lead ingot social inventory across five regions was only 19,300 mt, at a low point over the past 10 months. On the supply side, smelters of major primary lead delivery brands remain under maintenance, and lead ingot output and market circulation resources are subject to certain limitations. Although imported lead replenishment has increased, with primary lead supply recovery still insufficient, the lead ingot market does not yet have the conditions for significant inventory buildup in the short term.
3. Spot market: Sharp futures decline drove spot premiums higher, smelters held back from selling at low prices
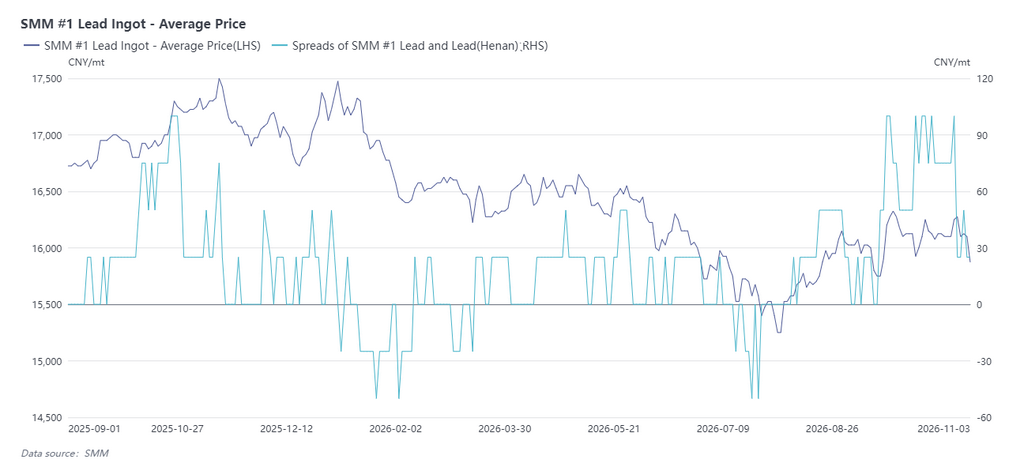
Unlike the continued weakness in futures, the spot market showed some resilience. After SHFE lead prices fell sharply, suppliers' quotations remained relatively firm, and spot premiums actually widened. In Henan, for example, today (November 3), ex-works primary lead quotations against the SHFE 2612 contract were at premiums of 80-100 yuan/mt, a notable increase from premiums of 0-50 yuan/mt yesterday.
Meanwhile, some lead smelters held back from selling at low prices after the rapid pullback in lead prices, with some even temporarily suspending shipments, further restricting spot market supply. This shows that although imported lead arrivals and weakening downstream consumption have put some pressure on lead prices, spot supply has not yet become notably ample given low inventory levels, and the widening of spot premiums also reflects suppliers' limited acceptance of current prices.
IV. Market Outlook: Watch for Bearish Sentiment Release, Low Inventory Still Supports Lead Prices
From the futures performance, SHFE lead is currently in a downtrend with increasing open interest, as bearish funds continue to exert pressure, and short-term market sentiment remains bearish. Going forward, attention should be paid to the release of bearish sentiment and changes in open interest. Once selling pressure on the futures gradually eases, lead price movements may return to fundamental logic. At that point, low inventory, the progress of production resumptions at lead smelters, and changes in spot premiums will become important bases for judging whether lead prices can stabilize.
Data source statement: Except for public information, all other data are processed by SMM based on public information, market communication, and SMM's internal database models, for reference only and not constituting decision-making advice.