At theShanghai Metals Market Information & Technology Co., Ltd. (SMM)SMM Senior Analyst Chen Chichang shared insights on the "order explosion logic" in the aluminum plate/sheet, strip and foil market—from export dividends to endogenous growth.Supply-Demand Balance of Aluminum Plate/Sheet, Strip and Foil
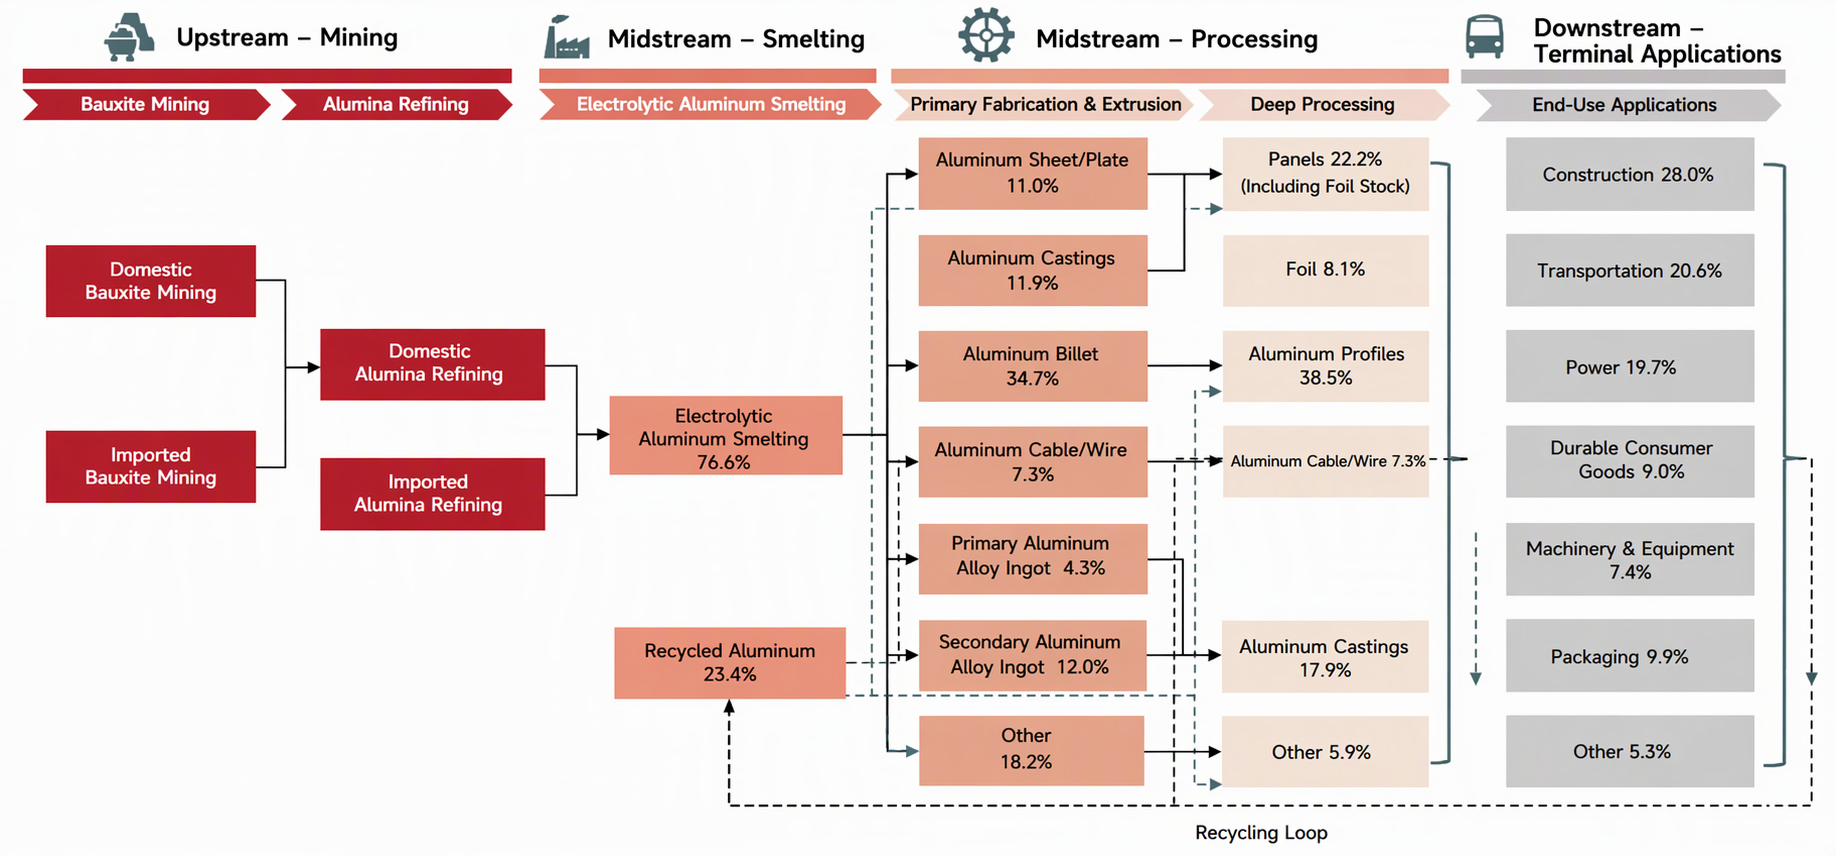
Aluminum plate/sheet, strip and foil is a key part of the aluminum industry chain
New energy and packaging sectors drive growth, supply and demand for aluminum plate/sheet, strip and foil trend toward balance
Supply & Demand Analysis of Aluminum Plate/Sheet, Strip and Foil
Supply side—H1 operating rate weakened YoY, H2 recovery began from a low base, supply release remains limited
According to SMM data, China's aluminum plate/sheet and strip production totaled 11.56 million mt in January-September 2026, up 7.9% YoY; aluminum foil production totaled 4.224 million mt, up 6.6% YoY.
The operating rate of the aluminum plate/sheet, strip and foil industry showed a pullback trend of "stable first, then declining." The support from external demand extended into Q3, with export orders limiting the downside for operating rates; however, as the order transfer effect from North American plant production resumptions faded, the ex-China restocking cycle came to an end, and the traditional domestic off-season arrived, downward pressure on operating rates will intensify significantly. Notably, the supply structure shift caused by accelerated capacity conversion from double zero foil to battery foil will push packaging foil supply and demand toward a tight balance, keeping processing fees high; meanwhile, air-conditioner foil, pressured by sluggish property completions and high channel inventory, will enter a period of deep adjustment, with some capacity facing exit from the market. H2 operating rates for aluminum plate/sheet and strip are expected to range between 65%-70%, and for aluminum foil between 67%-72%.
The contraction of transferred export orders will test domestic demand absorption capacity. The can stock market, having lost transferred orders and facing disruption from new national standards, will face severe challenges in filling the demand gap in H2. Although energy storage consumption remains highly prosperous, it is difficult to fully offset the slowdown in traditional sectors (home appliances, construction). The overall supply-demand pattern in H2 will trend looser, with operating rates under pressure and pulling back, and the industry will enter an active destocking cycle.
Export side—"export boom" impulse peaks, SHFE/LME price ratio recovery pressures H2 plate/sheet, strip and foil exports
For many years, thanks to policy incentives and the product advantages of Chinese aluminum semis, Chinese aluminum semis have maintained a competitive edge of superiority plus low prices in ex-China markets. The cancellation of the aluminum semis export tax rebate at the end of 2024 has, to some extent, increased export costs for aluminum semis export enterprises and dampened the export enthusiasm of Chinese aluminum processing enterprises. The aluminum processing industry is facing a "pain period" lasting about one year.
In the medium and long term, China is a major global exporter of aluminum semis, and ex-China markets face a certain supply-demand gap for aluminum semis, allowing China's aluminum semis to retain certain advantages.
Since late June 2026, the SHFE/LME price ratio has rapidly recovered, quickly closing the arbitrage window that had driven large-scale exports of aluminum semis. With the gradual fading of the order diversion effect, new orders in some segments have already declined, but previously accepted fixed-price orders are still being executed as planned. Since July, exports of aluminum plate/sheet, strip and foil have gradually pulled back, though full-year exports of aluminum plate/sheet and strip are still expected to rebound to 3.4-3.5 million mt.
Export side - In January-September 2026, aluminum plate/sheet and strip exports rose 19.5% YoY, and aluminum foil exports rose 13.2% YoY
Customs data show that in January-September 2026, China's cumulative exports of aluminum plate/sheet and strip reached 2.7373 million mt, up 19.5% YoY, while aluminum foil exports rose 13.2% YoY. By destination, the main export market for aluminum plate/sheet and strip was Mexico, followed by the US, Vietnam, and South Korea. For aluminum foil, the main export markets were Thailand, with India, Indonesia, South Korea, and Mexico holding comparable shares.
Imports and exports - Price spread advantage between China and ex-China markets combined with tight ex-China supply-demand conditions drove exports to a record high for the same period in recent years
Changes in the share of aluminum plate/sheet, strip and foil exports by trade mode in 2025 and 2026
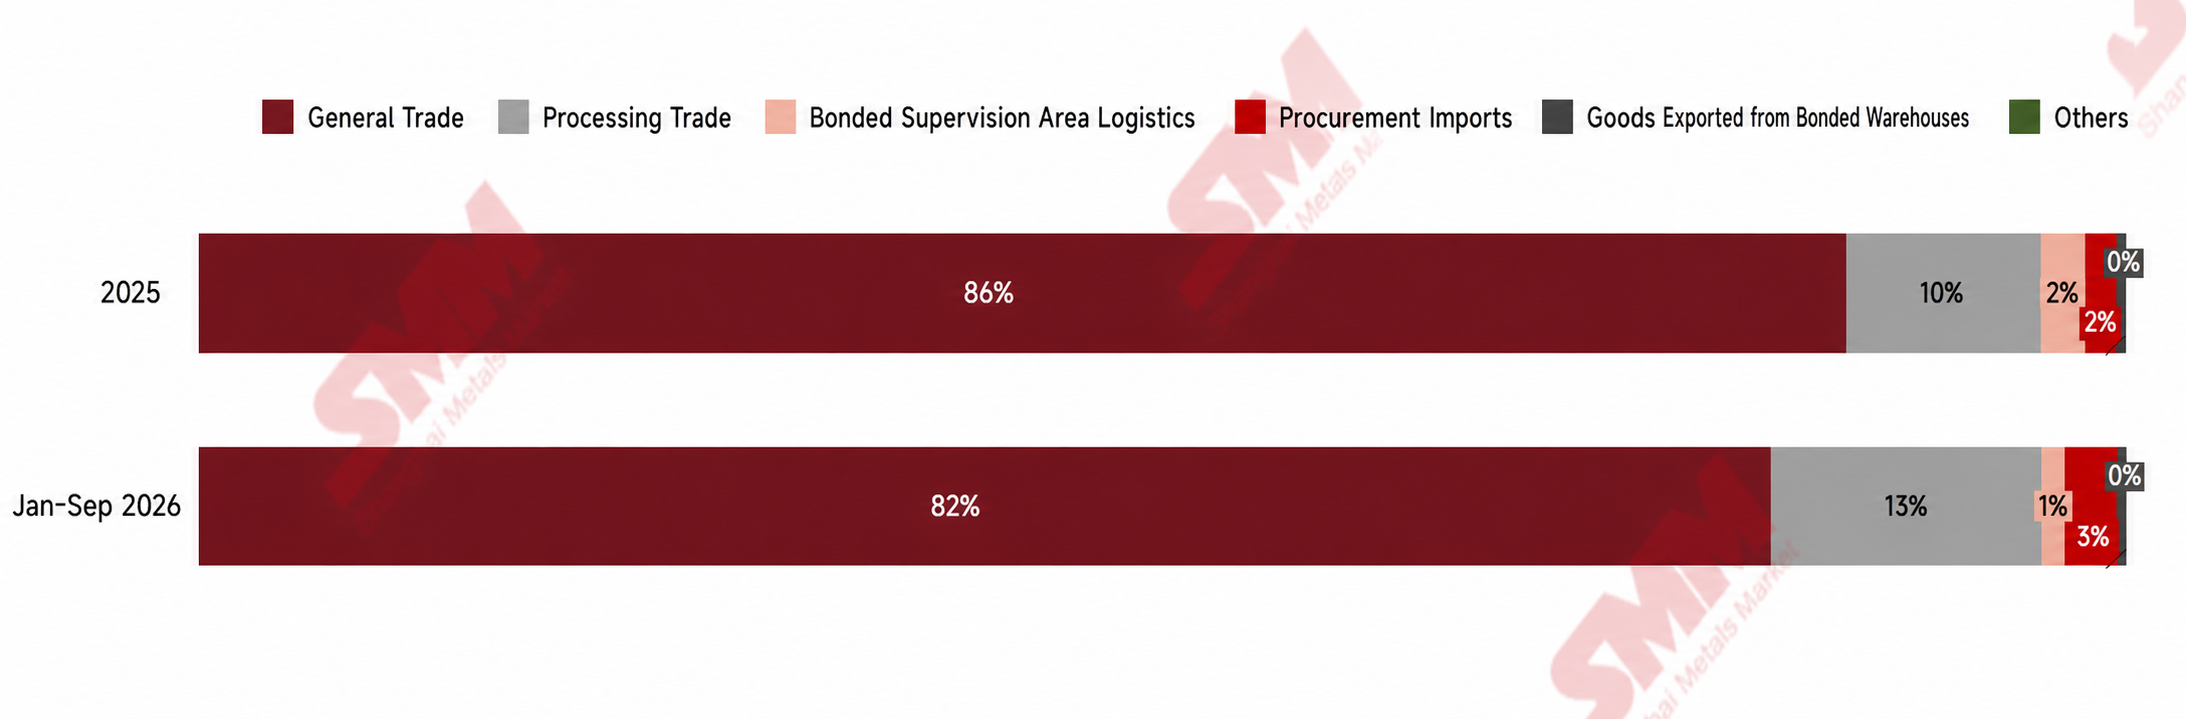
By trade mode, Ordinary Trade remained dominant, but its share fell from 86% to 82%, with the entire lost share shifting to processing trade: processing trade with imported materials rose from 10% to 13%, and processing trade with supplied materials rose from 2% to 3%, lifting the combined share from 12% to 16%. The export surge driven by the price spread advantage between China and ex-China markets and tight ex-China supply-demand conditions, and the shift toward toll processing in trade modes, are two sides of the same coin - ex-China buyers increasingly prefer processing trade to lock in raw materials and prices while avoiding tariff and origin risks.
By export registration location: Henan 20.4%, Shandong 17.5%, Jiangsu 13.0%, Zhejiang 8.5%, and Shanghai 8.2%, with these five provinces and cities accounting for 67.5% in total. The regional pattern of aluminum plate/sheet, strip and foil is closely aligned with downstream processing clusters: Henan and Shandong rely on integrated aluminum smelting and hot-rolling/casting-rolling to produce plate/sheet and strip, while Jiangsu, Zhejiang, and Shanghai focus on foil and high-end plate/sheet and strip exports.
In 2027, the export share of processing trade with imported materials is expected to continue growing. Ex-China new capacity is being gradually released, and LME faces notably greater downward pressure than the domestic market, meaning the SHFE/LME price ratio is expected to keep widening, and the arbitrage window for processing trade with imported materials will likely remain at favorable levels.
Structural divergence in the aluminum plate/sheet, strip and foil market intensifies, with export orders becoming a standout growth driver for the industry
Looking back at H1 2026, China's aluminum plate/sheet, strip and foil market showed a notable pattern of domestic divergence and strong ex-China performance. On one hand, traditional domestic consumption sectors such as building curtain walls and ordinary civil sheets & plates are constrained by high aluminum prices, with downstream procurement extremely cautious and maintaining just-in-time stockpiling year-round, causing the operating rate recovery of related products to fall short of expectations. On the other hand, high value-added products such as can stock, battery casings, and brazing materials for energy storage are seeing robust demand, becoming the core force underpinning domestic demand. Most critically, thanks to the global aluminum supply deficit and strong LME aluminum performance,
export orders became a standout growth driver for the industry in H1, with export schedules for can stock, single and double zero foil, and some sheets & plates generally extended into Q3, effectively hedging against the risk of domestic demand pullback.
From a longer-term perspective, the automotive sheet industry is shifting from "scale expansion" to "quality breakthroughs." Inner panels have largely achieved domestic substitution, but outer panels still lag foreign enterprises in yield and surface quality. Production is expected to grow mildly to around 550,000-600,000 mt by 2030.
In battery foil, 2025 production rose 19% YoY to 573,000 mt, but more than 500,000 mt of new capacity is still pending commissioning. Although processing fees saw some upward adjustments during the year, enterprises remain under operational pressure, and an industry reshuffle remains inevitable going forward.
Air-conditioner foil has entered a phase of cyclical adjustment. While the "aluminum as a substitute for copper" policy provides long-term support, in the short term, affected by high inventory and demand overextension, some enterprises on the supply side have already initiated voluntary production cuts or shifted production, and the industry is set to enter a period of deep adjustment.
Air-Conditioner Aluminum Foil Faces High Inventory Woes, Seeking High-End Course Under Policy Guidance
According to an SMM survey, China's air-conditioner aluminum foil production experienced a notable fluctuation cycle from 2021 to 2025. In 2021, with the post-pandemic economic recovery, China's home appliance exports showed strong performance, and aluminum foil production grew steadily to approximately 980,000 mt. In 2022-2023, driven by positive expectations from China's 14th Five-Year Plan and extreme summer heat, air-conditioner production activity was robust, with aluminum foil production reaching 1.04 million mt in 2023. Production continued to grow to 1.06 million mt in 2024, mainly due to stockpiling by air-conditioner enterprises to meet peak-season demand. However, entering 2026, as end-user air-conditioner social inventory continues to climb, aluminum foil production is expected to pull back to around 900,000 mt, a decline of about 8% from 2025.
With the gradual implementation of the Implementation Plan for High-Quality Development of the Aluminum Industry, the "aluminum as a substitute for copper" policy will continue to advance, providing policy support for expanding the application of air-conditioner aluminum foil in residential and commercial air-conditioning sectors.
Expansion Wave Meets "Demand Gap": Domestic Substitution Accelerates but High-End Breakthroughs Remain Under Pressure
Looking back at 2021 to 2025, from the supply side, as of end-2025, the number of domestic automotive sheet enterprises with stable production capacity had reached 8, with total operating capacity of approximately 1 million mt per year, marking the establishment of a large-scale supply system in China. However, nearly 400,000 mt of additional capacity is still under construction or commissioning, signaling that supply pressure will persist in the future.
At this stage, the industry as a whole exhibits the characteristics of a "buyer's market," with cost reduction pressure from OEMs taking top priority, which limits the bargaining power of material suppliers and makes it difficult to implement strategies similar to the joint efforts to hold prices firm seen in the can stock and battery foil sectors. On the policy front, while the national "dual carbon" goals are favorable for automotive lightweighting and aluminum semis applications in the long term, cost considerations often take precedence over lightweighting demands in the micro-level operations of enterprises in the short term.
Based on the current capacity layout and demand assessment, China's automotive sheet production is expected to reach approximately 550,000-600,000 mt per year by 2030, with a compound annual growth rate remaining in the single digits, and the industry holds a cautiously optimistic attitude toward medium and long-term consumption.
NEV and Energy Storage Dual Drivers Battery Foil Ushers in a Second Wave of High-Speed Growth
According to SMM statistics, China's battery foil production in 2025 was 573,000 mt, an increase of about 92,000 mt from 2024, up 19% YoY, with the growth rate still far ahead among many aluminum foil products. In 2025, the number of enterprises capable of large-scale stable battery foil production was about 27, and thanks to the high-speed growth of NEV and energy storage end-users, most battery foil producers were directly driven to increase production.
SMM believes that a large amount of new battery foil capacity is still about to come online. Although battery aluminum foil has barriers such as technical thresholds and long certification cycles, a large number of new battery foil projects still exist, with over 280,000 mt of new battery foil capacity set to be commissioned in 2026 alone, and competition in the battery foil market remains fierce. Among the more than 20 producers currently operating, most enterprises' battery foil processing fees continue to run close to the cost line. Under the supply-demand mismatch in the market, future actions may include production cuts in battery foil, suspension of new production line plans, or even exit from the battery foil market.
Aluminum Plate/Sheet, Strip and Foil Price Analysis and Long-Term Outlook
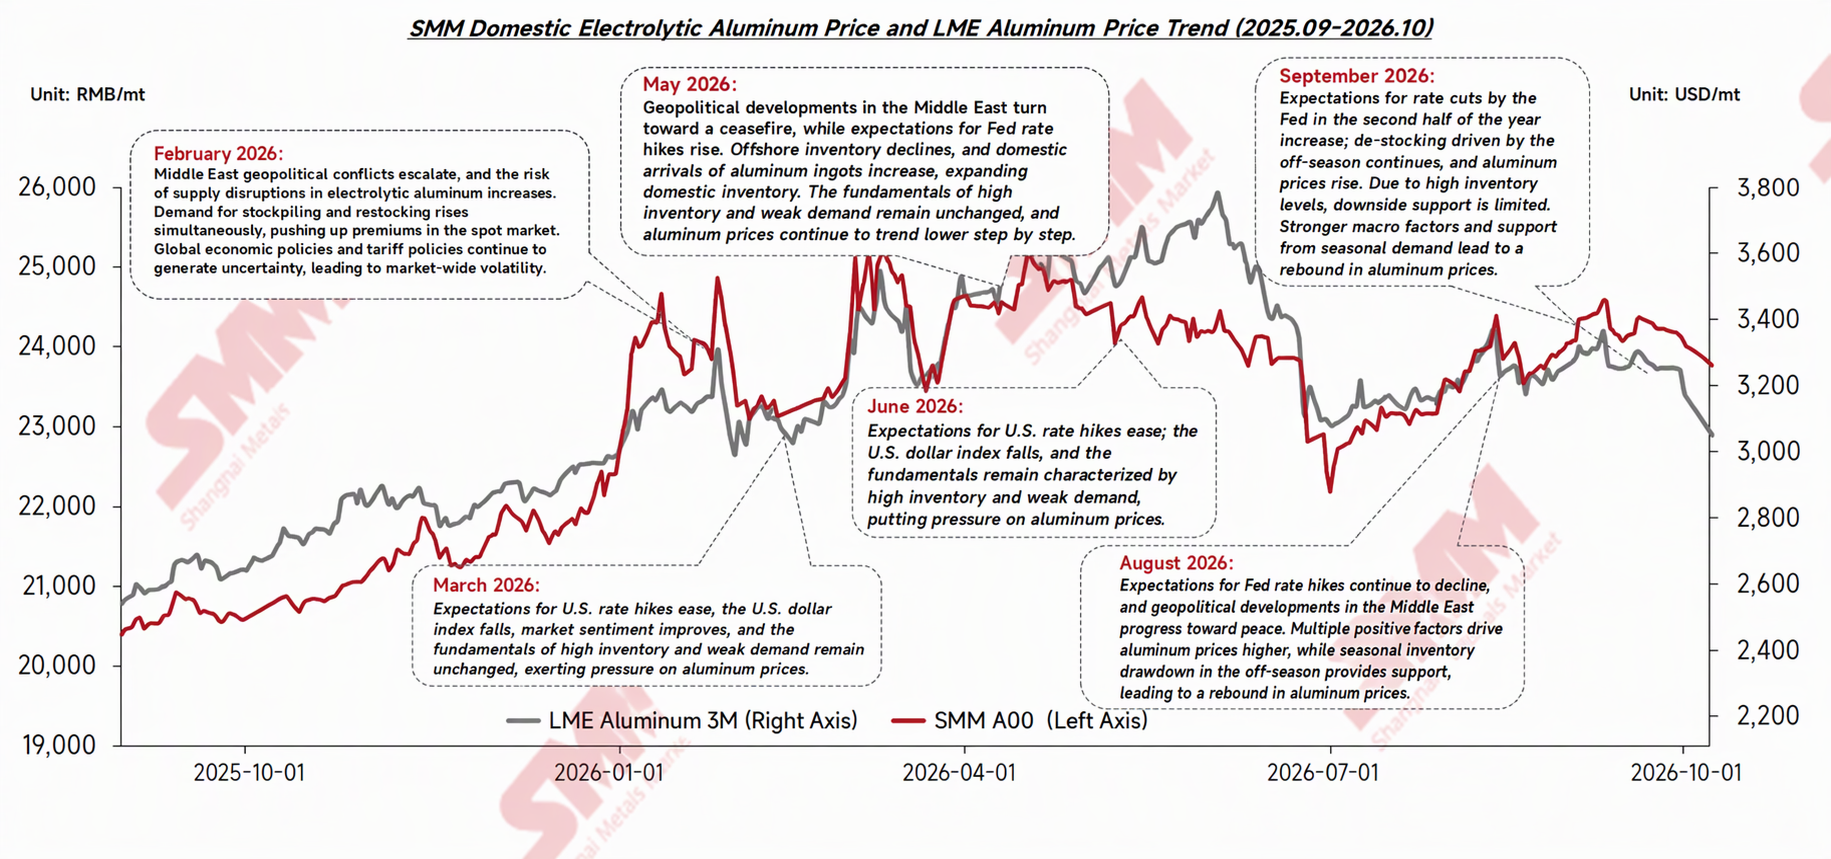
A00 Price - Global Aluminum Surplus Expectations Rise Aluminum Prices Under Long-Term Pressure