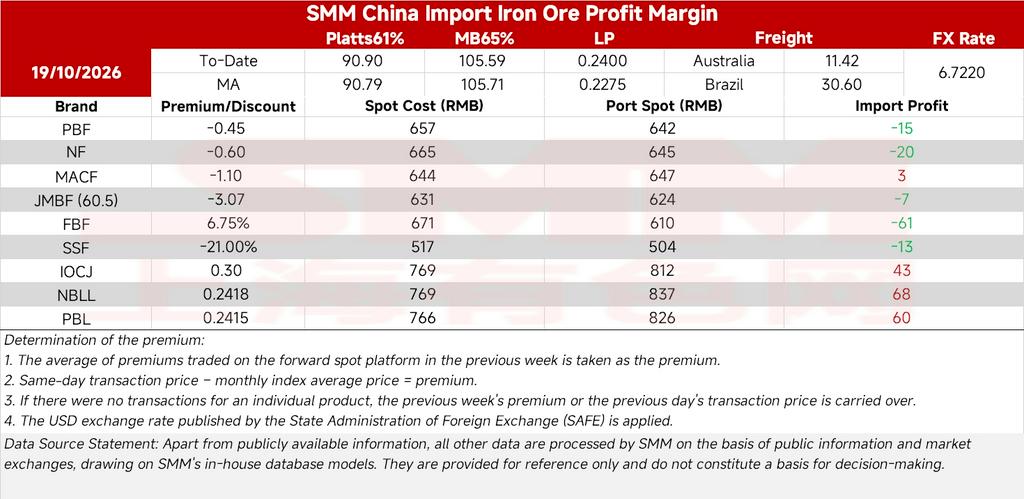
The average imported iron ore margin widened slightly from 6.01 yuan/mt to 6.38 yuan/mt this period. Lower seaborne premiums for some brands and lower freight rates were the main drivers.
Port inventory data this week point to gradually weakening spot demand. Iron ore stocks at 35 major Chinese ports rose 2.85 million mt week-on-week to 148.30 million mt as of 16 October, according to the latest SMM data. Average daily port outbound volume fell 50,000 mt week-on-week to 3.185 million mt. Steel mills are posting clear losses, and whether the recovery in hot metal output can be sustained remains to be confirmed. Mills are buying on an as-needed basis, with little appetite for restocking. Supply remains relatively ample, and port stocks are likely to keep building. Barring unexpected news, iron ore prices are expected to trade soft within a narrow range in the near term, with imported iron ore margins holding in slightly positive territory.