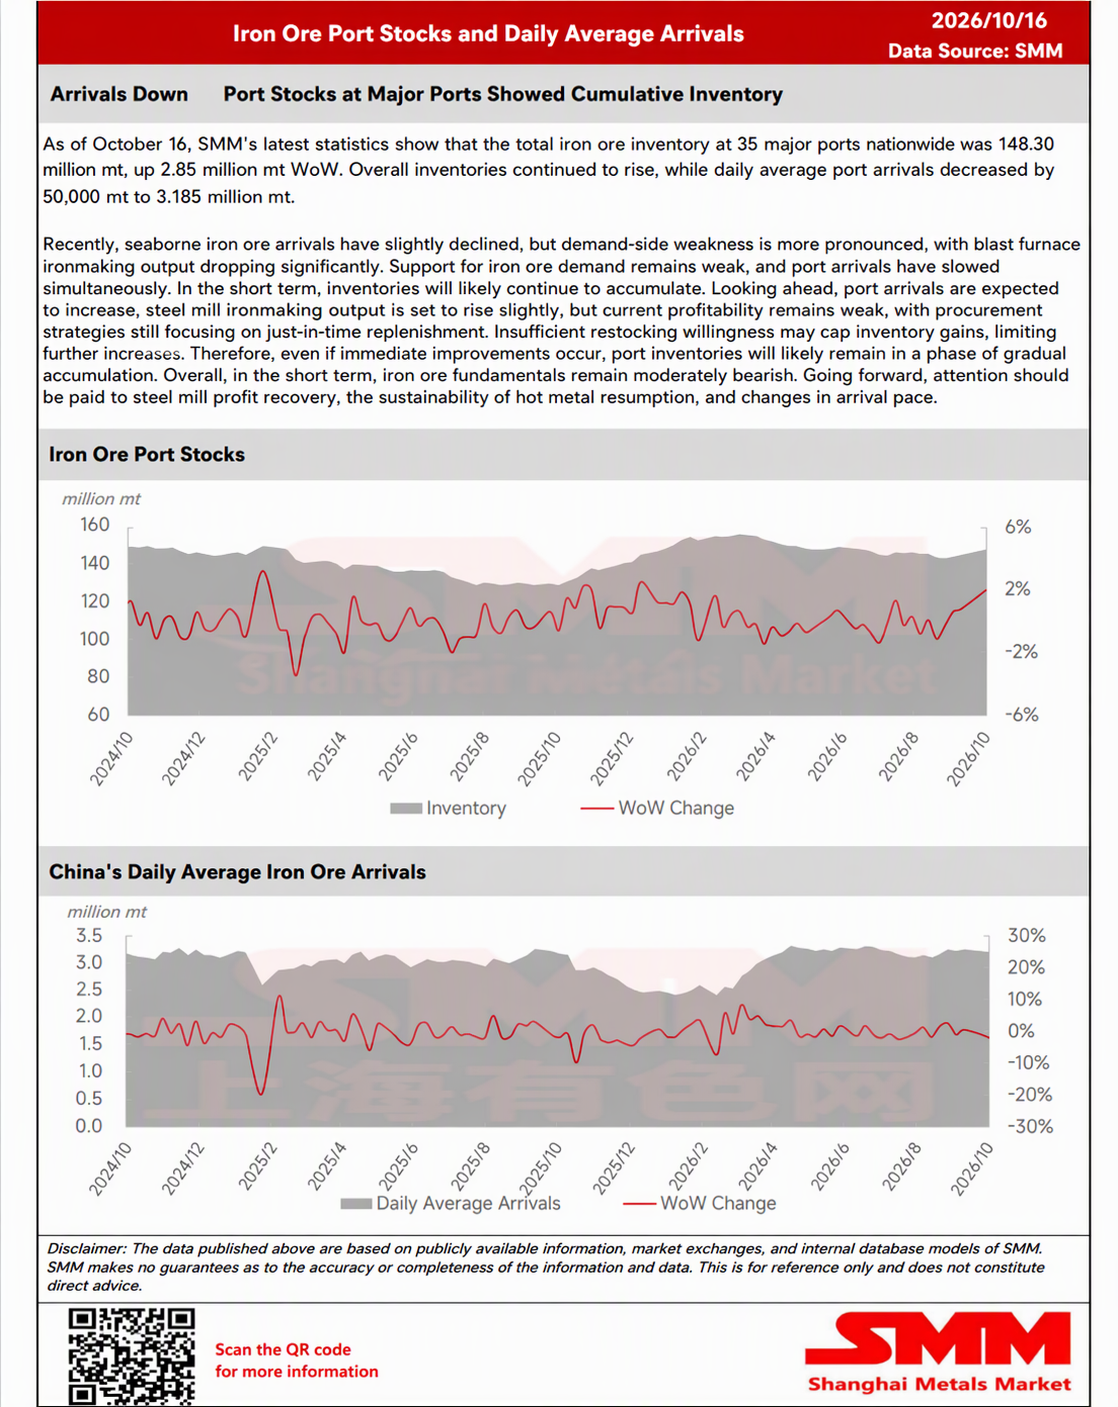
As of October 16, SMM's latest statistics show that total iron ore inventory across 35 main ports nationwide stood at 148.3 million mt, up 2.85 million mt MoM, with overall inventory on an upward trend. Daily average port pick-up volume edged down 50,000 mt to 3.185 million mt.
Recent iron ore port arrivals pulled back slightly, but demand-side performance was even weaker. Hot metal production of steel mill blast furnaces declined notably, further weakening support for iron ore concentrates demand and dragging port pick-up volume lower in tandem. With arrivals declining while port pick-up fell more sharply, port inventory continued to accumulate overall. Looking ahead to next week, port arrivals are expected to increase, and hot metal production of steel mill blast furnaces may rebound slightly. However, steel mill profits are currently in significant losses, and procurement strategies remain largely need-based, with limited restocking willingness, so the boost to port pick-up volume is expected to be limited. Therefore, even if demand shows marginal improvement, the supply-demand pace remains loose, and port inventory is highly likely to continue accumulating. Overall, iron ore fundamentals remain weak in the short term, and port inventory pressure is unlikely to ease soon. Attention should be paid to steel mill profit recovery, the sustainability of hot metal production resumptions, and changes in the pace of port arrivals.