SMM, October 16:
This week, the sharp rise and fall in copper prices caused market sentiment to swing repeatedly, with the price difference between copper cathode and copper scrap narrowing from 3,979 yuan/mt to 2,794 yuan/mt. Coinciding with this week's futures contract rollover and delivery, the price spread between copper futures contracts widened. Many secondary copper rod enterprises saw a significant decline in spot procurement demand, preferring to have copper scrap traders hold inventory on consignment first and settle pricing after the contract rollover. However, traders were unwilling to consign all material, with most requiring spot cash settlement and only a small portion accepting consignment. The two sides disagreed on settlement methods, resulting in low overall transaction volumes. As the "reverse invoicing" policy enforcement tightened and relevant authorities significantly increased inspection frequency on scrap utilization enterprises, secondary copper rod and scrap-derived copper anode enterprises were forced to continuously raise the proportion of tax-inclusive copper scrap purchases to mitigate tax risks, ensure compliance of input and output invoices, and avoid input invoices being red-flagged. Meanwhile, non-tax-inclusive copper scrap, unable to provide compliant deduction vouchers and facing inspection risks, saw downstream scrap utilization enterprises' purchase willingness plunge to a freezing point. Market demand nearly vanished and circulation essentially stalled, leaving non-tax-inclusive supply in the awkward position of "having a price but no market, unable to sell."
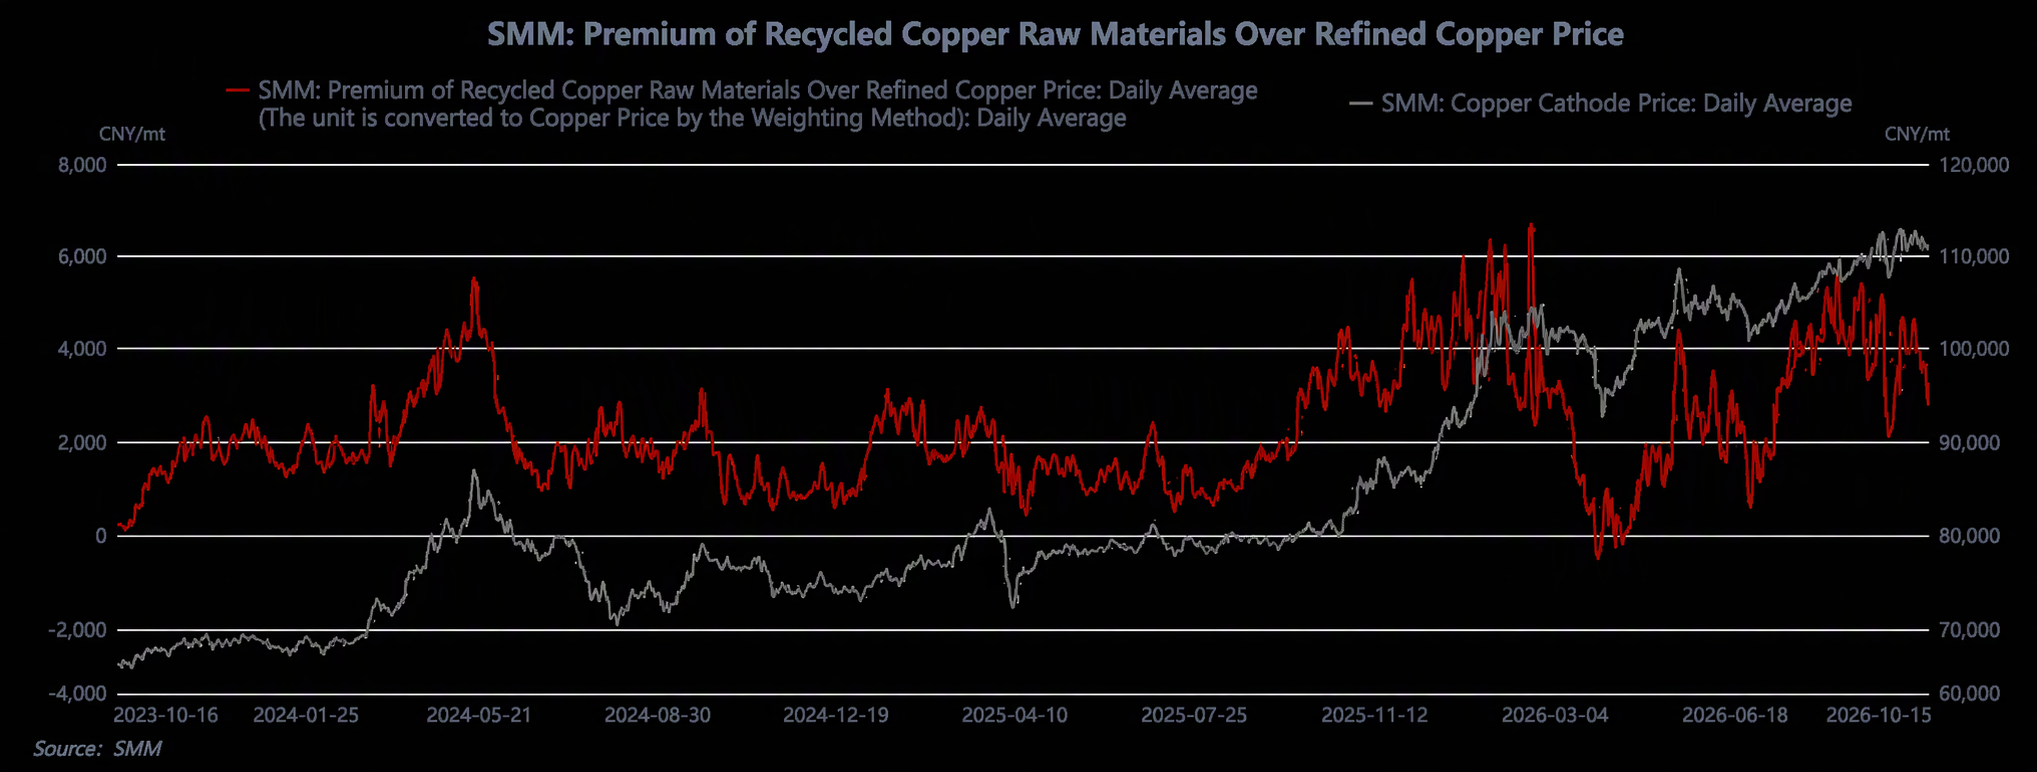
Looking ahead, if relevant authorities maintain high inspection frequency and the implementation standards for reverse invoicing are not further optimized, the structural mismatch between tight tax-inclusive raw material supply and unsalable non-tax-inclusive supply will persist. Copper scrap market transactions are unlikely to see substantive improvement, and secondary copper rod enterprises will find it difficult to ease pressure from production cuts and suspensions. At the same time, the dilemma of "tax-inclusive material being impossible to secure, non-tax-inclusive material being impossible to sell" will continue, further reinforcing the industry's low operating rates and capacity rationalization among small and medium-sized producers.