In September 2026, China's LiPF6 production continued to edge up, with monthly production up about 3.4% MoM from August and up about 59% YoY. Overall supply release remained slow, and the supply-demand tight balance persisted.
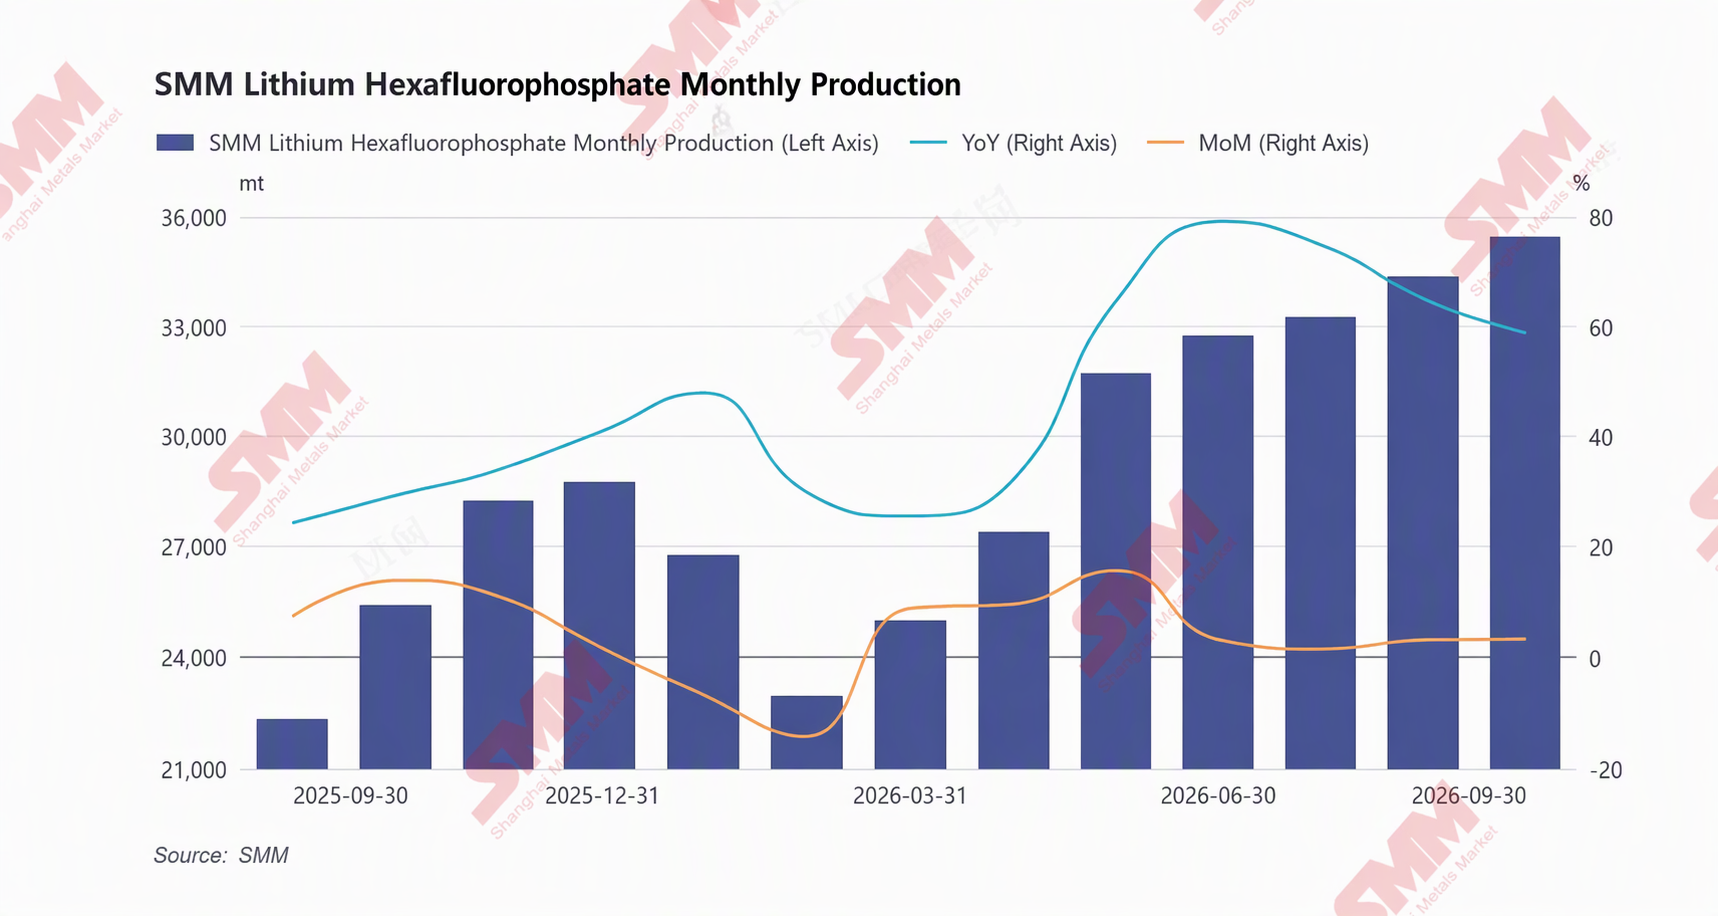
On the demand side, end-use lithium battery demand continued to improve in September. Additionally, electrolyte producers stocked up on raw materials in advance ahead of the National Day holiday, boosting downstream LiPF6 purchasing demand and providing core support for the current market strength. On the supply side, however, despite the continued rise in LiPF6 prices, overall production growth remained relatively limited, constrained mainly by two factors.
First, capacity is limited. Most LiPF6 producers in the industry are currently operating at full capacity. Some new capacity is in the ramp-up stage, but given the high technical barriers in LiPF6 production processes and stringent requirements for production environment and quality control, the actual ramp-up progress of some new production lines has fallen short of expectations, making it difficult to quickly release growth.
Second, producers have limited willingness to increase production. This month, prices of the key raw material lithium carbonate continued to decline, while end-use demand growth fell short of earlier market expectations for the September peak season. Although LiPF6 producers themselves have pricing demands, the cost pressure from earlier LiPF6 price increases has not yet been fully passed on by electrolyte enterprises to downstream battery clients. Downstream acceptance of further LiPF6 price hikes remains low, and actual market price increases have been limited. Against this backdrop, even enterprises with spare capacity are reluctant to rapidly raise operating rates.
Looking ahead, the October peak season is expected to further boost demand. The energy storage sector continues to show improving demand. The EV sector is expected to benefit from the implementation of export restrictions on hybrid car models to Europe on December 1, which may trigger a phased rush to export and boost LiPF6 demand. However, in September, electrolyte enterprises' earlier optimism led to advance stockpiling, but actual end-use production fell short of expectations. Combined with the continued decline in lithium carbonate prices, electrolyte enterprises have become more cautious in purchasing, with weaker willingness to buy. LiPF6 producers, sensing weaker downstream demand, are similarly reluctant to proactively increase production. Overall, China's LiPF6 production growth is expected to remain slow in October.
Note: If you have any additions or corrections regarding the details mentioned in this article, please feel free to contact us at:
Tel: 021-20707858 Hu Xuejie. Thank you!
SMM New Energy Research Team
Wang Cong 021-51666838
Ma Rui 021-51595780
Feng Disheng 021-51666714
Lyu Yanlin 021-20707875
Zhang Haohan 021-51666752
Wang Zihan 021-51666914
Wang Jie 021-51595902
Xu Yang 021-51666760
Xu Mengqi 021-20707868
Hu Xuejie 021-20707858