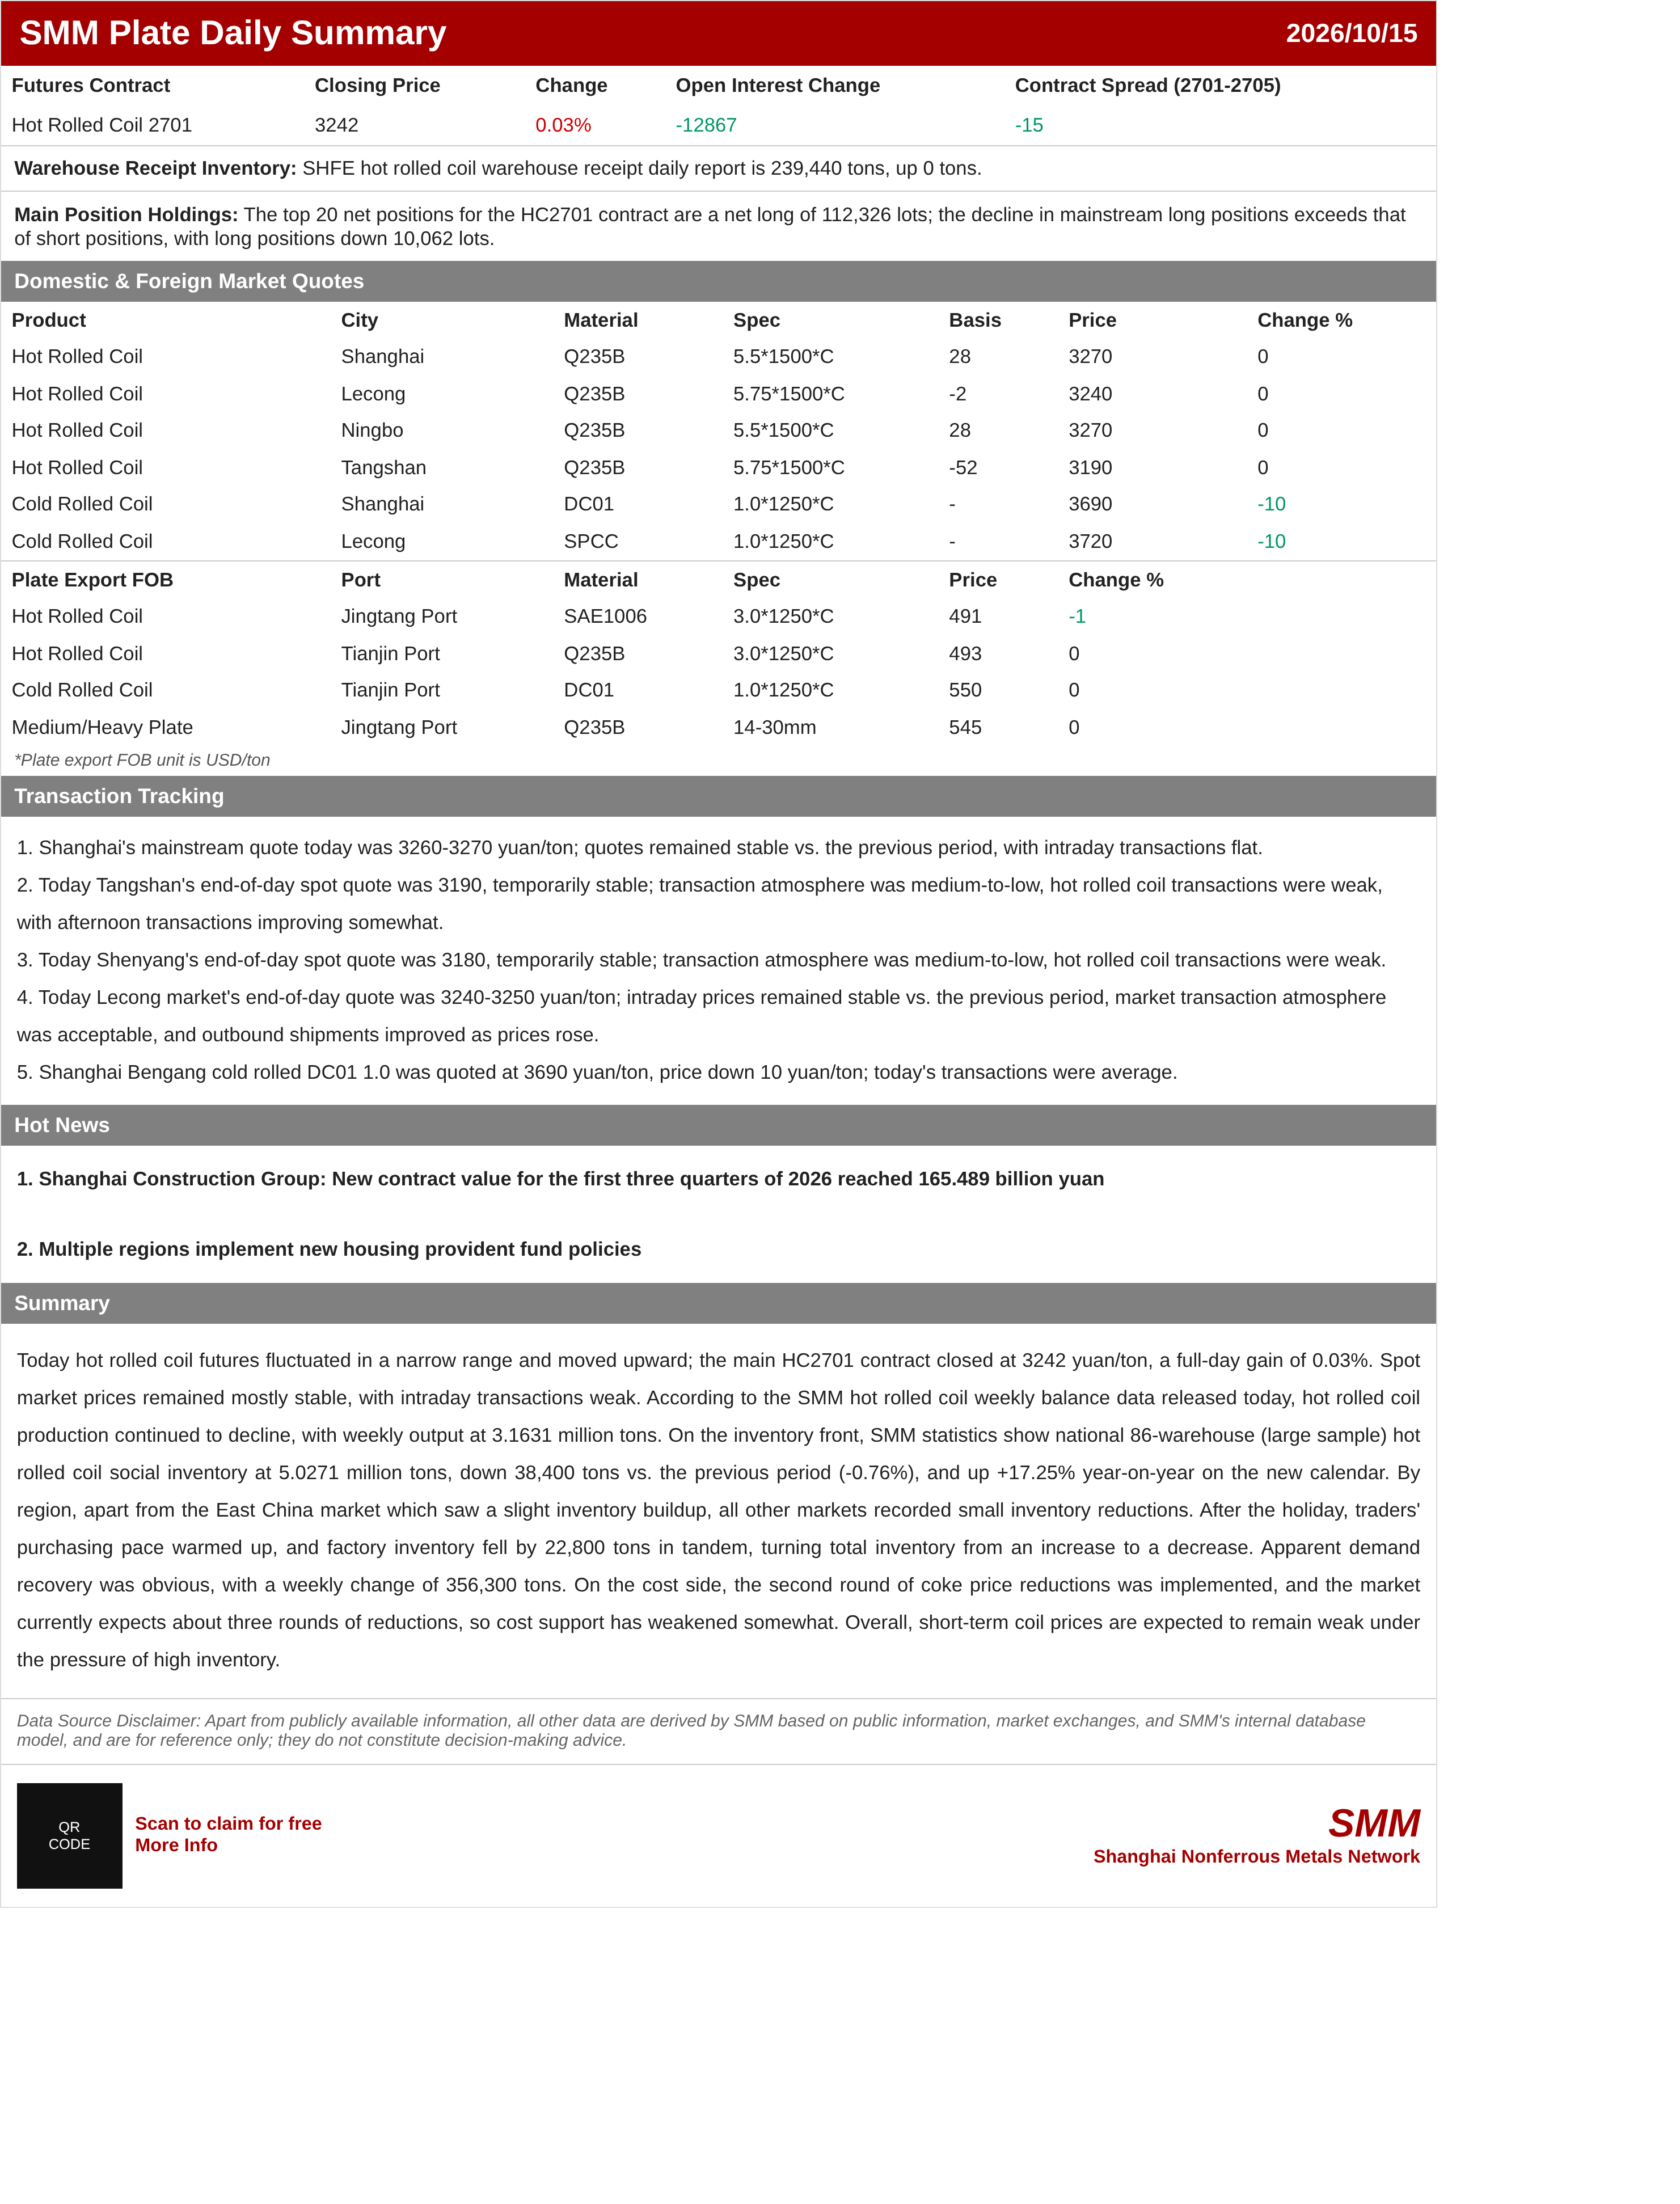
HRC futures consolidated slightly higher today, with the most-traded HC2701 contract closing at 3,242 yuan/mt, up 0.03% for the day. Spot market prices were mostly stable, with intraday trading subdued. According to the SMM weekly HRC balance data released today, HRC production continued to pull back, with weekly production at 3.1631 million mt. On the inventory side, HRC social inventory across 86 warehouses nationwide (large sample) tracked by SMM stood at 5.0271 million mt, down 38,400 mt WoW, or -0.76% WoW, and up 17.25% YoY on a calendar-year basis. By region, apart from a slight inventory buildup in east China, other markets all saw modest inventory declines. After the holiday, traders' purchasing pace warmed up again, and mill inventory fell by 22,800 mt over the same period, with total inventory shifting from an increase to a decrease. Apparent demand recovered notably, up 356,300 mt WoW. On the cost side, the second round of coke price cuts took effect, and the market currently expects around three rounds of cuts, weakening support somewhat. Overall, HRC prices are expected to remain in the doldrums in the near term, pressured by high inventory.