Overseas primary aluminum premiums remained weak this week, but the pace of decline slowed across several Asian markets. Downstream demand has not shown a clear improvement, although current premium levels are beginning to approach ranges where sellers are less willing to make further concessions.
I. Review of Spot Premiums by Region
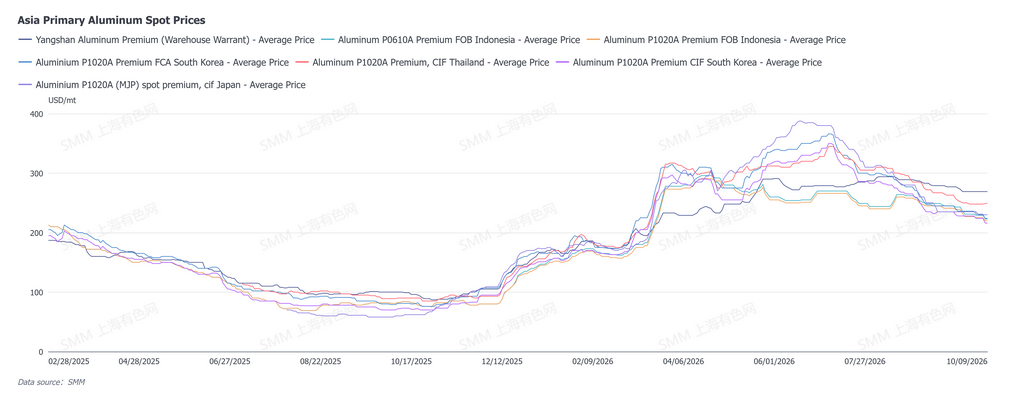
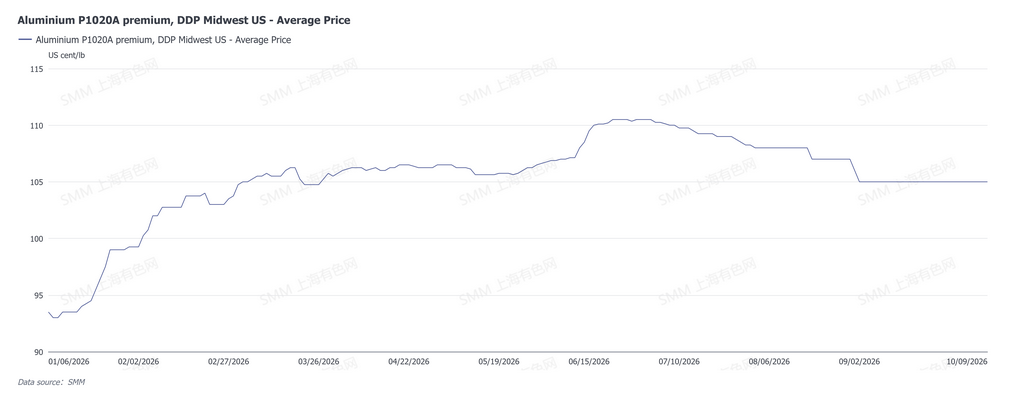
As of October 9, the CIF Thailand P1020A premium stood at USD 249/mt, FCA South Korea at USD 223/mt, CIF South Korea at USD 216/mt, and CIF Japan MJP spot at USD 230/mt. The Japan warehouse-warrant premium was USD 269/mt, while the US Midwest DDP premium remained at 105 US cents/lb.
Across Asia, premiums remained under pressure, although the pace of decline was less pronounced than in previous weeks. Demand was still subdued, but sellers in several markets showed less willingness to make further sizeable concessions, suggesting that prices may be moving closer to a short-term floor.
Southeast Asia
Thailand: Downward Momentum Slows
Thailand remained quiet this week, with downstream consumers continuing to purchase mainly for immediate production needs.
The main change was on the offer side. After several weeks of declining premiums, sellers showed less willingness to make further sizeable reductions. With the CIF Thailand premium at USD 249/mt, the market appears to be moving closer to a level where additional downside becomes more limited.
Demand itself has not strengthened, so a sharp rebound is unlikely in the near term. However, the market could gradually stabilize if buying interest improves from current levels.
South Korea: Seller Competitions Begins to Ease
The South Korean market continued to face relatively comfortable supply, while downstream purchasing remained selective.
Earlier weakness was largely driven by sellers competing for limited demand. This pressure has started to moderate as premiums move lower, with the FCA South Korea premium at USD 223/mt and the CIF premium at USD 216/mt.
Buyers are still seeking lower prices, but sellers have become less responsive to aggressive bids. This has helped slow the decline and may allow premiums to move within a narrower range in the near term.
Japan
CIF Japan MJP Primary Aluminum Spot
Japan’s spot MJP market remained slow this week, with limited transactions and no clear improvement in downstream demand.
As of October 9, the CIF Japan MJP spot premium stood at USD 230/mt, while the warehouse-warrant premium was USD 269/mt.
Market attention is increasingly shifting toward where Q4 values may find support. Current market discussions are centered around approximately USD 255/mt as an indicative Q4 offer level. Some recent transactions have also been reported around this level; however, transaction volumes remain limited and are not yet representative of the broader market.
This does not reflect stronger demand. Rather, current price levels are moving closer to a range where sellers are less willing to offer further discounts. If this continues, spot MJP could begin to stabilize even before downstream demand shows a visible recovery.
United States
US Midwest DDP Premium Holds Steady
The US Midwest DDP premium remained at 105 US cents/lb this week.
Trading conditions changed little, with no significant shift in either downstream demand or supply availability. Compared with Asian markets, where premiums are still finding a floor, the Midwest market has remained relatively stable.
Without a major change in regional fundamentals, the premium is expected to stay broadly steady in the near term.
Market Outlook
The outlook for overseas primary aluminum premiums has become less bearish.
Downstream demand remains subdued, but premiums have already moved to relatively low levels, making further reductions less attractive for sellers. This change in offer behavior may provide support for several Asian markets in the coming weeks.
In the near term, premiums may stabilize or recover modestly from current levels. A stronger rebound, however, would still require a clearer improvement in downstream orders and restocking demand.