Lead Market Review During the Holiday
The SHFE lead market was closed during China's National Day holiday, while LME lead fluctuated in a down-then-up pattern as the macroeconomic backdrop shifted.
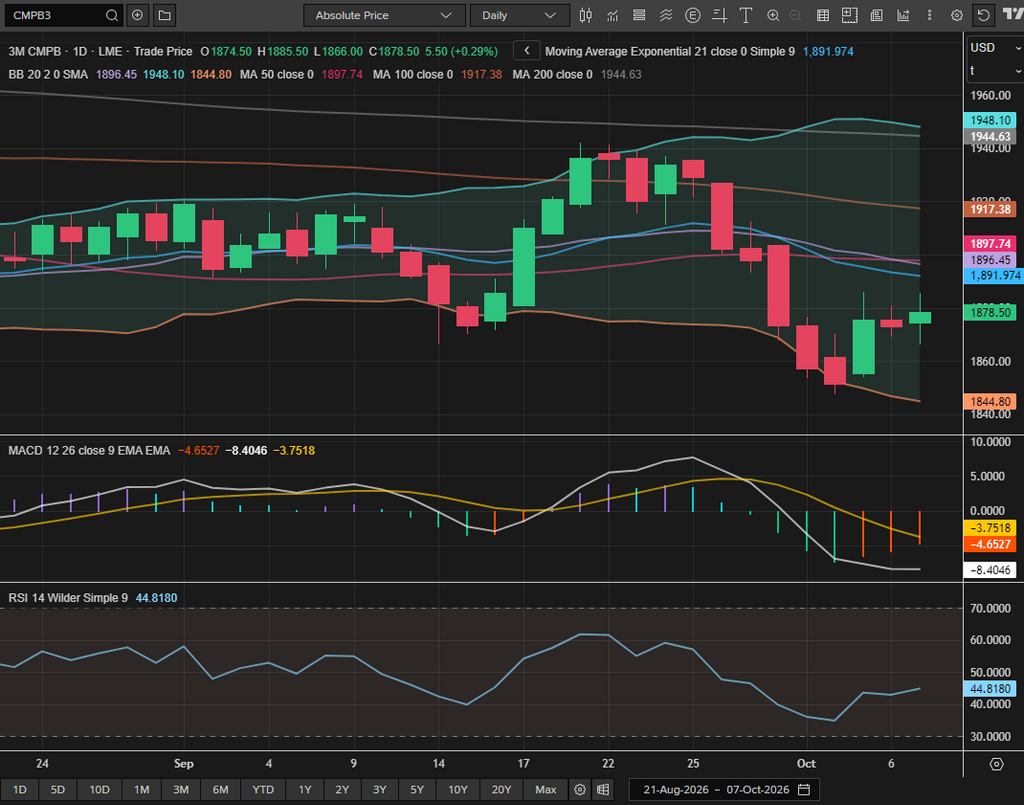
After closing at $1,871.5/mt on September 30, LME lead fell further to $1,860/mt on October 1, marking its lowest level since mid-July. Following the release of US NFP data on October 2, lead prices gradually stabilised and closed at around $1,853.5/mt. After the market reopened on October 5, LME lead rebounded rapidly to $1,869.5/mt before edging up further to $1,871.5/mt on October 6.
During Asian trading hours on October 7, LME lead opened at $1,874.5/mt and initially fell to an intraday low of $1,866/mt before trending higher. As of 18:00 Beijing time, the contract had risen to $1,881.5/mt. Overall, LME lead recorded only a marginal decline of 0.5% during the holiday period.
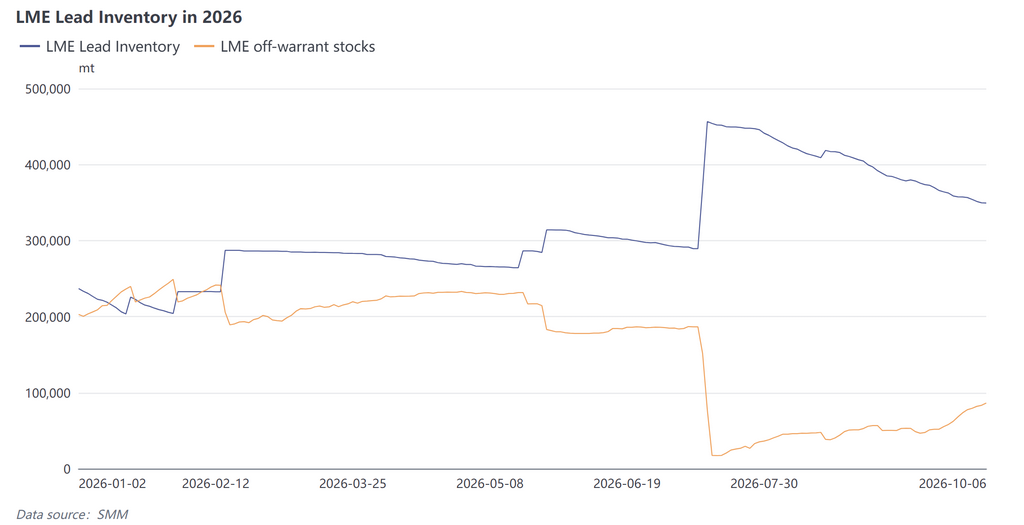
LME lead inventories continued their previous downward trend, falling gradually from 356,600 mt on September 30 to 349,400 mt on October 6, a decline of 7,200 mt. Meanwhile, cancelled warrants increased by approximately 8,600 mt on October 6, lifting the cancelled-warrant ratio to 10.3%. Off-warrant stocks also rose from 77,500 mt to 86,300 mt, representing a net increase of 8,800 mt. Most of the increases and decreases were concentrated in Singapore warehouses.
The recent decline in LME inventories has consistently been accompanied by an increase in off-warrant stocks. Much of the metal under cancelled warrants has not actually left the warehouse system but has merely shifted from registered to off-warrant inventory. Given the currently elevated absolute level of LME stocks, the decline in headline inventories is insufficient to support expectations of tightening overseas supply. In the forward market, the Cash-to-three-month contango widened from $36.49/mt on September 30 to $40.91/mt on October 6, further confirming that the overseas market is not currently experiencing a physical shortage.
On the macroeconomic front, the main theme in overseas markets during the holiday was a reversal in expectations for a US Federal Reserve rate hike. LME lead consequently followed a "correction–stabilisation–rebound" trajectory.
Strong US economic data at the end of September, including a rise in the PMI to a multi-year high, together with hawkish comments from Federal Reserve officials, briefly pushed the market-implied probability of an October rate hike to 70–80%. US Treasury yields rose across the curve, with the five-year yield climbing above 5% for the first time since 2007 and the ten-year yield reaching 5.344%, its highest level since 2002. The US dollar index also advanced to a 17-month high. Under combined pressure from a stronger dollar and rising Treasury yields, base metals weakened broadly. LME lead declined for several consecutive sessions and closed at around $1,853.5/mt on October 2, its lowest level in nearly three months.
Sentiment changed midway through the holiday after US NFP data delivered a significant downside surprise, rapidly cooling expectations of further monetary tightening. Data released on the evening of October 2 Beijing time showed that the US economy added only 29,000 jobs in September, less than one-third of market expectations. The previous month’s reading was revised down from 162,000 to 133,000, while the July figure was revised to a contraction of 10,000. The combined downward revision for the two months reached 60,000. The unemployment rate rose to 4.2%, while average hourly earnings increased by only 0.1% month on month.
Following the weak employment report, the implied probability of an October rate hike plunged from 70–80% a week earlier to 15–28%. The US dollar retreated from its 17-month high, while Treasury yields also moved lower. LME base metals rebounded across the board after trading resumed on October 5, with LME lead gaining 0.86% to close at $1,869.5/mt.
Although the weak payroll data eased near-term tightening pressure, the market continued to price in an approximately 60% probability of a December rate hike. "Wait until December to reassess" became the prevailing market expectation. The US dollar index still closed at 102.29 on October 5, indicating that macroeconomic pressure had only eased at the margin rather than fundamentally reversed.
In terms of positioning, the LME COTR published on October 6 showed that LME lead prices fell approximately 4.0% in the week ended October 2. During the same period, investment funds reduced long positions by around 4,600 lots and added approximately 7,000 lots of short positions, contributing to the price decline during the holiday. Funds had already shifted into a net-short position in LME lead, with their net-long position as a percentage of open interest falling further from -8.22% in the previous week to -12.42%.
Although lead outperformed zinc during the holiday and subsequently staged a strong rebound, speculative funds remained comparatively bearish on lead from a fundamental perspective.
Review of China's Domestic Fundamentals
Domestic supply is expected to increase in October, although the initial release may be relatively gradual.
In the primary lead market, smelters in central and northern China resumed operations in late September following maintenance. However, production remained unstable during the initial restart phase, leaving scope for further output growth once operations stabilise in October.
In the secondary lead market, some producers planned to reduce output during the National Day holiday, which could result in a slight decline in operating rates. However, with market trading largely suspended, finished-product inventories were expected to rise modestly.
Overall, the restart of primary lead smelters following maintenance and the post-holiday resumption of secondary lead production will form the two main sources of additional supply in October. The actual pace of output growth after the holiday will depend on the progress of individual smelter restarts.
On the demand side, consumption weakened temporarily during the holiday after pre-holiday stockpiling came to an end. With the Mid-Autumn Festival and National Day holidays occurring close together, the combined weekly operating rate of lead-acid battery producers across five major provinces fell by 13.98 percentage points week on week between September 25 and October 1.
Lead-acid battery producers had already completed their pre-holiday restocking of lead ingots. In the final week before the holiday, companies purchased only according to immediate production needs, while spot-market transactions weakened further. Some distributors planned promotional sales during the National Day holiday. In the early post-holiday period, downstream consumers are therefore likely to prioritise drawing down their own inventories, resulting in a relatively slow recovery in purchasing demand.
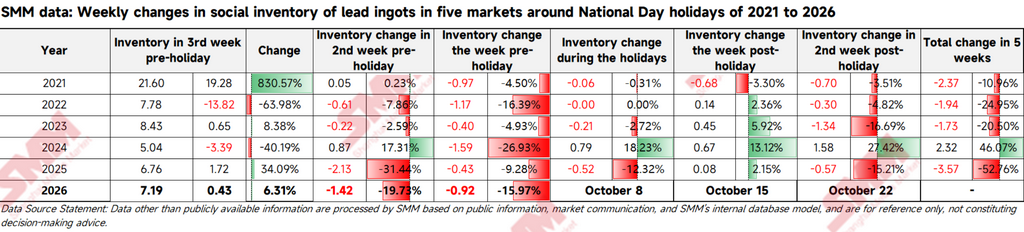
In terms of inventories, primary and secondary lead smelters held relatively low finished-product stocks after actively preselling October cargoes and completing pre-holiday deliveries to downstream buyers. During the final week before the National Day holiday, SMM social inventories of lead ingots across five major regions declined by approximately 9,200 mt. As of September 30, five-region social inventories had fallen to 48,600 mt. Although some inventory accumulation is expected after the holiday, the upside is likely to remain limited.
Post-Holiday Outlook
Looking ahead, external uncertainty surrounding the lead market remains elevated. Although the unexpectedly weak September nonfarm payroll report sharply reduced the probability of an October rate hike and prompted a rebound in LME lead on October 5, the market has not completely abandoned expectations of a December rate hike. The US dollar index and Treasury yields remain at elevated levels, leaving overseas markets under continued pressure and limiting the upside of the LME lead rebound.
Results of University of Michigan Surveys of Consumers are due on Friday, October 9, and the release of September US CPI data on October 14 will test whether the cooling labour market can meaningfully alter inflation expectations. These will be the key macroeconomic events to monitor during the first week after the holiday.
LME lead inventories remain on a downward trend and had fallen to approximately 349,000 mt as of October 6. However, the spread remains in contango, which has gradually widened to around $40/mt, indicating that the overseas physical market is not tight.
LME lead fell by 0.5% over the holiday period. As macroeconomic pressure pushed overseas prices lower, China's lead import window reopened. Market participants should closely monitor the pace at which overseas lead ingots are transferred into the Chinese market after the holiday.
Domestically, the expected increase in primary lead production and arrivals of imported lead are likely to result in some accumulation of lead ingot inventories, placing downward pressure on prices. However, the current domestic inventory base remains low. Social inventories across five major regions, together with finished-product stocks at primary and secondary lead smelters, are all at relatively low levels. Smelters have also presold part of their October production, limiting the potential scale of inventory accumulation in the short term.
On the demand side, downstream lead-acid battery producers are expected to prioritise consuming existing inventories after the holiday, resulting in limited procurement demand. On the supply side, the pace at which primary lead smelters restore production will remain a key factor to monitor.
The lead price trading range may widen after the holiday. Prices are likely to remain volatile at elevated levels initially before coming under pressure as the expected increase in supply is gradually realised.
The above information is based on market data collected and assessed by the Shanghai Metals Market research team and is provided for reference only. This article does not constitute direct investment advice. Clients should exercise caution and make independent decisions. Shanghai Metals Market accepts no responsibility for any decisions made on the basis of this information.