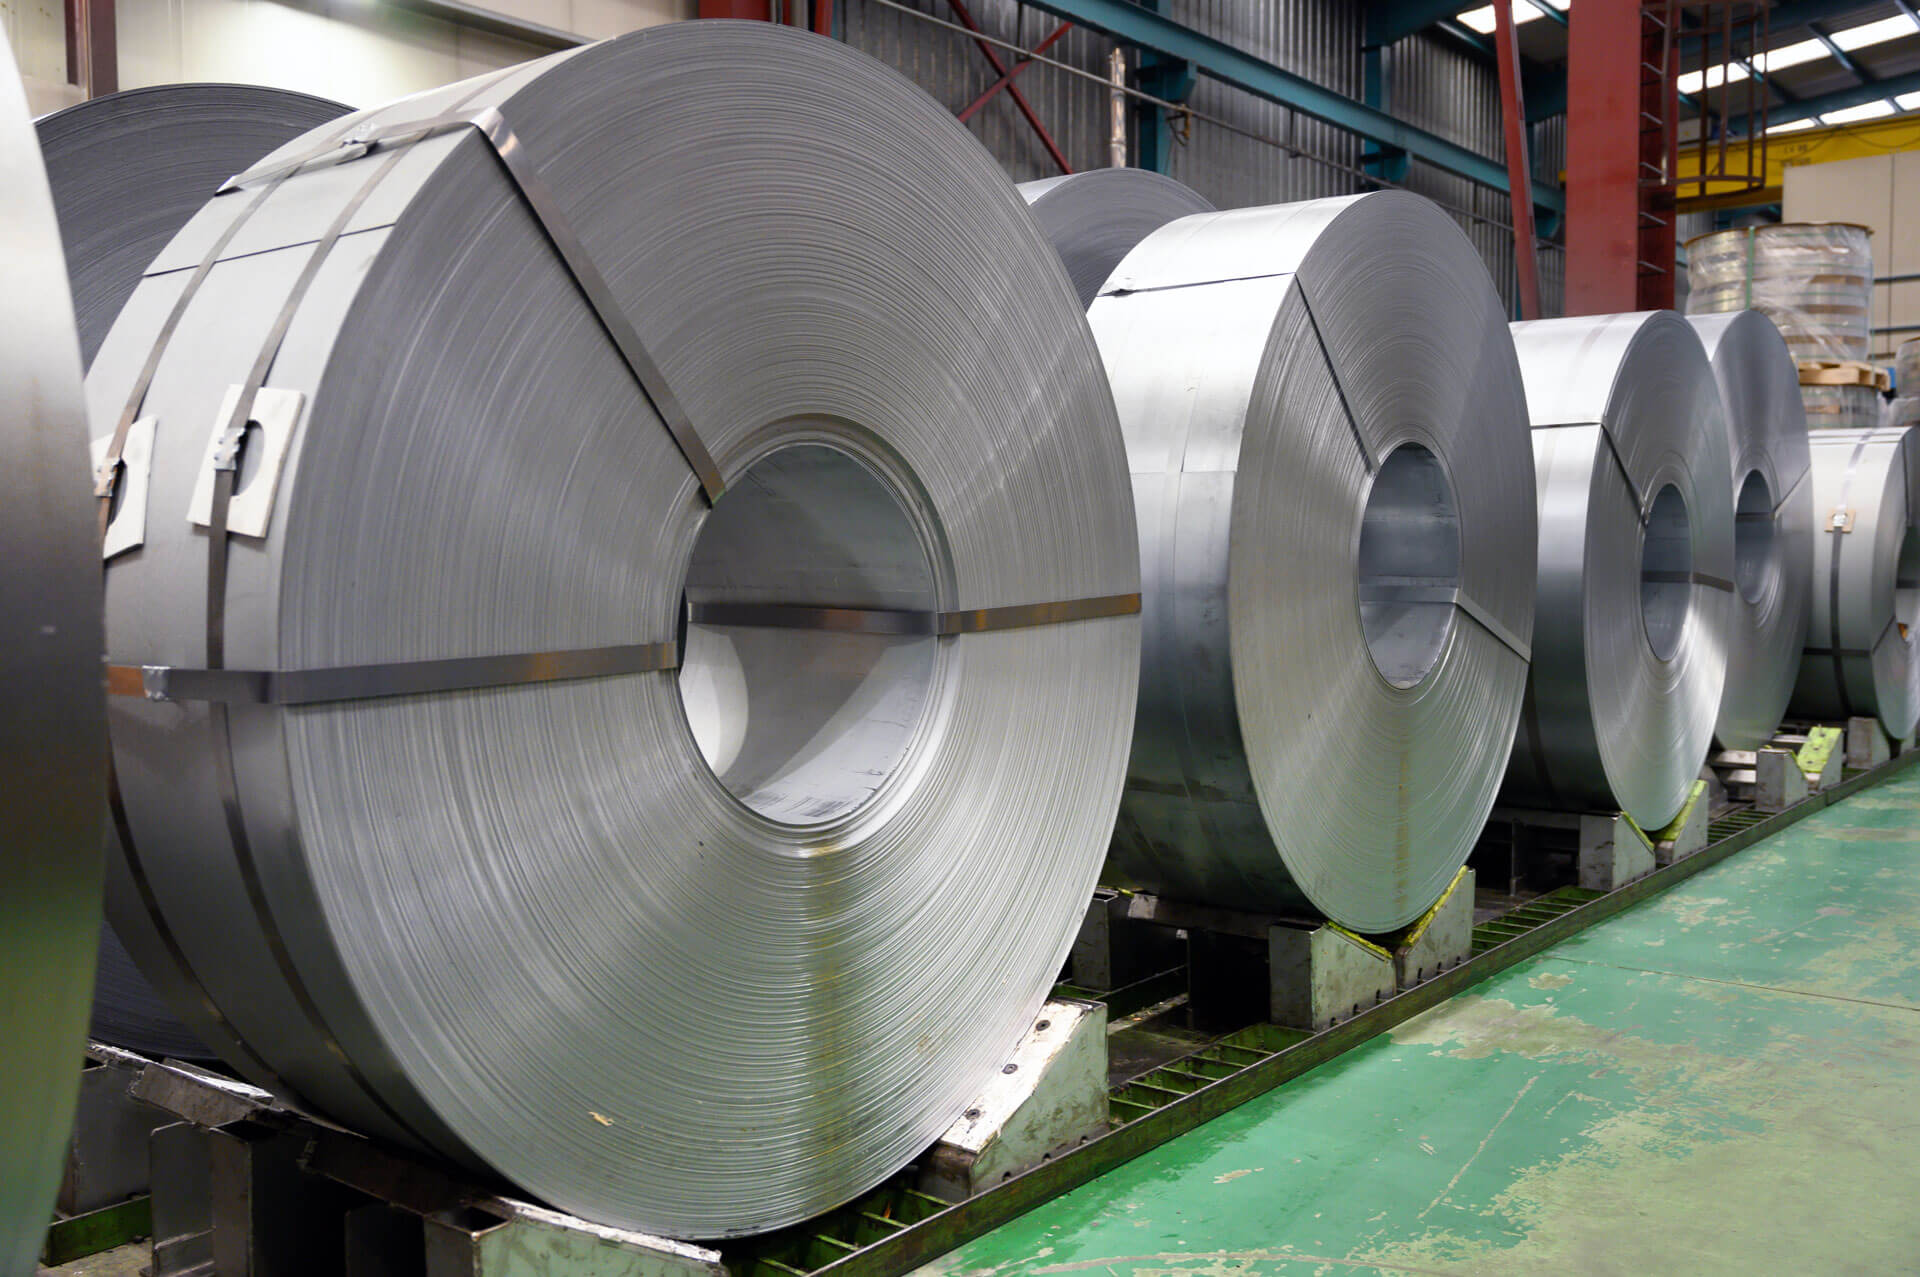
Q3 galvanising operating rates weak YoY; will Q4 demand see a recovery? [SMM analysis]
The galvanising industry remained in the doldrums overall in Q3, with operating rates still at relatively low levels YoY, and demand improvement in the traditional peak season also fell short of expectations. Will demand recover in Q4?
The galvanising industry remained in the doldrums overall in Q3, with operating rates still at relatively low levels YoY, and demand improvement in the traditional peak season also fell short of expectations. Will demand recover in Q4?
Galvanising industry operating rates were weak overall in Q3. High temperatures, typhoons and other weather disrupted production and transportation at some enterprises, while end-use consumption was mediocre. Galvanised pipe sales were sluggish, enterprise orders provided insufficient support, and some enterprises saw finished product inventories increase and proactively lowered production schedules. Steel tower orders began to see significant release from September, but follow-through from other infrastructure orders was relatively limited. Export orders were generally mediocre, PV-related demand was also weak, and overall operating rates remained weak YoY.
Entering Q4, power grid-related orders still provide some support, and as some projects enter the actual construction phase, they are expected to drive galvanising demand. On the infrastructure side, some projects will enter the construction phase in Q4, but property-related demand recovery remains slow, and galvanised pipe demand is improving slowly. Solar panel mounting bracket orders are relatively weak, export orders have yet to show clear growth, and traditional demand still lacks broad-based improvement. Therefore, even if some project orders continue to be released in Q4, overall industry demand may still show only a structural recovery.
Overall, Q4 galvanising operating rates may rebound from Q3, but the extent of the recovery still depends on the follow-through of new orders from the power grid, infrastructure and other sectors. If subsequent project orders can be implemented smoothly, industry operating rates are expected to improve further, but the overall pattern of weak operating rates YoY is expected to persist.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.
For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
1 min ago
Galvanising operating conditions
Read More
Galvanising operating conditions
[Galvanising operating conditions] Operating rates of galvanising producers fell significantly, mainly due to the concentrated holidays of the Mid-Autumn Festival and National Day, which markedly reduced effective production time. Demand side, recent orders showed divergence across different segments. Steel tower orders were relatively strong, with some enterprises receiving solid order support and taking fewer days off during the holidays, maintaining a degree of resilience in production. In contrast, other traditional galvanising orders remained weak, with insufficient new orders. Some enterprises had extended holiday breaks, and overall production schedules were notably affected.
1 min ago
2 mins ago
Zinc SHFE/LME Price Ratio
Read More
Zinc SHFE/LME Price Ratio
[Zinc SHFE/LME Price Ratio] This week, the SHFE/LME zinc price ratio held near 6.8, with the import window for zinc ingot into China remaining closed. Outside China, the US dollar index held up well, and combined with rising oil prices and hawkish remarks from US Fed officials, LME zinc consolidated under pressure. However, the LME Cash-3M backwardation structure persisted, providing some support to prices. In China, end-use consumption was mediocre, and the National Day and Mid-Autumn Festival holiday period was extended. Yet with tight ore supply and low TCs, SHFE zinc also continued to consolidate at highs. Overall, the overseas and domestic markets moved relatively in tandem, and the SHFE/LME zinc price ratio is expected to continue consolidating near 6.8.
2 mins ago
3 mins ago
North China Zinc Ingot Market
Read More
North China Zinc Ingot Market
[North China Zinc Ingot Market] Spot premiums in Tianjin rose significantly this week, up 50 yuan/mt WoW. As of Thursday this week, domestic mainstream brands were quoted at premiums of 50 yuan/mt to discounts of 70 yuan/mt against the 2611 contract, while high-priced brands were quoted at premiums of around 200 yuan/mt against the 2610 contract. Tianjin was quoted at a discount of around 25 yuan/mt against Shanghai, with the Shanghai-Tianjin price spread narrowing. Zinc prices consolidated this week, but with the holiday approaching, many downstream buyers priced and stockpiled, and gradually picked up goods. Some traders were on holiday toward month-end with fewer shipments, coupled with fewer transport vehicles and rising oil prices, freight costs rose notably. Traders raised their quot
3 mins ago