In mid-August, Fortescue announced that its green metal project at the Christmas Creek mine in Western Australia's Pilbara region had produced its first hot metal, marking the first successful operation of the project's electric smelting process. This achieved a complete closed-loop technical route from direct reduced iron (DRI) to iron smelting in an electric furnace.
The project was approved in November 2023, with an investment of approximately $50 million. It was originally planned to commence production in 2025, with a designed capacity of over 1,500 mt of green iron per year. The process is supplied by Metso and comprises two parts: a Circored hydrogen-based fluidized bed direct reduction unit and a DRI electric smelting furnace. The former can use 100% green hydrogen and can directly process Pilbara fines without pelletizing; the latter uses DRI as raw material, replacing the blast furnace for smelting. The first Metso equipment began installation in September 2025. The on-site green hydrogen facility was commissioned in 2024, with two 700 kW electrolyzers producing approximately 530 kg of hydrogen per day.
Fortescue CEO Dino Otranto stated that no enterprise has yet solved the problem of producing green metal from Pilbara ore at a commercial scale. This period proves that the process can produce hot metal, but whether it can operate stably with the target Pilbara ore still requires further verification. Based on the information disclosed so far, the electric smelting furnace has been able to produce hot metal, but the company has not yet provided data on whether the full process from Circored reduction to electric smelting can run continuously with Pilbara fines. The raw material issue of high-impurity fines remains in the verification stage.
Why is Pilbara ore difficult to feed into DRI-EAF
The conventional DRI-EAF route has stringent raw material requirements. The DRI-EAF route can only consume DR-grade raw materials with an iron grade above 66% and combined SiO₂ and Al₂O₃ content below 3.5%, while Pilbara ore is predominantly hematite and goethite, which generally does not meet this threshold. According to an IEEFA briefing from June 2026, the reason is that the direct reduction stage cannot remove impurities, and the oxidizing atmosphere of the electric arc furnace limits its reduction and impurity removal capabilities. An IEEFA report from March showed that DR-grade raw materials account for a very small share of global iron ore supply. Citing Midrex forecasts, it indicated that the DR-grade raw material shortfall could reach 16.4 million mt per year by 2034.
The electric smelting furnace (ESF) is designed to address exactly this issue. The ESF can process high-gangue raw materials, completing slag-iron separation during smelting to produce hot metal close to pig iron, which is then sent to a converter for steelmaking. Therefore, the accurate route name matching Pilbara ore should be DRI-ESF-converter. This route preserves the existing converter assets of steel mills and is more favorable for mills that primarily operate integrated processes.
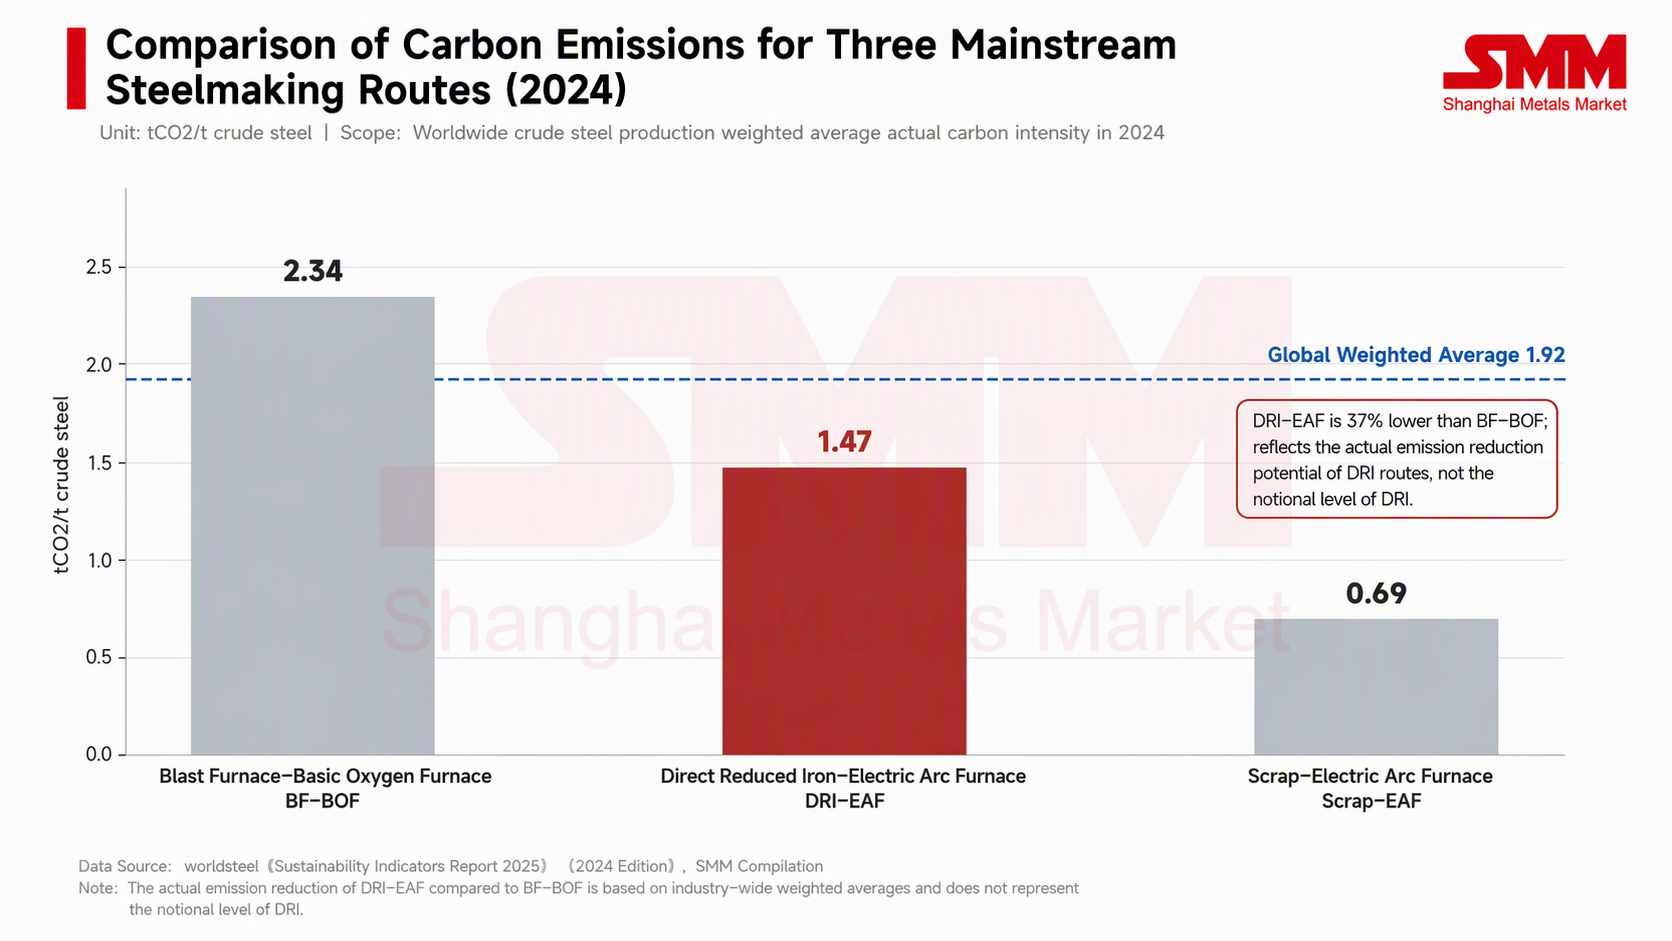
In terms of emission reduction potential, according to the latest Worldsteel statistics, carbon emissions per mt of steel via the BF-BOF route were 2.34 mt in 2024, compared with 1.47 mt for DRI-EAF, about 37% lower than the former, and 0.69 mt for scrap-EAF, with a global weighted average of 1.92 mt. It should be noted that the 1.47 mt figure reflects actual emissions from existing direct reduction capacity and does not represent the level of hydrogen-based DRI; there is also no industry-wide emission standard yet for the DRI-ESF-BOF route.
Electric smelting furnaces (ESF) are taking on low- and medium-grade ore, while the transition from natural gas to hydrogen is generally slowing down.
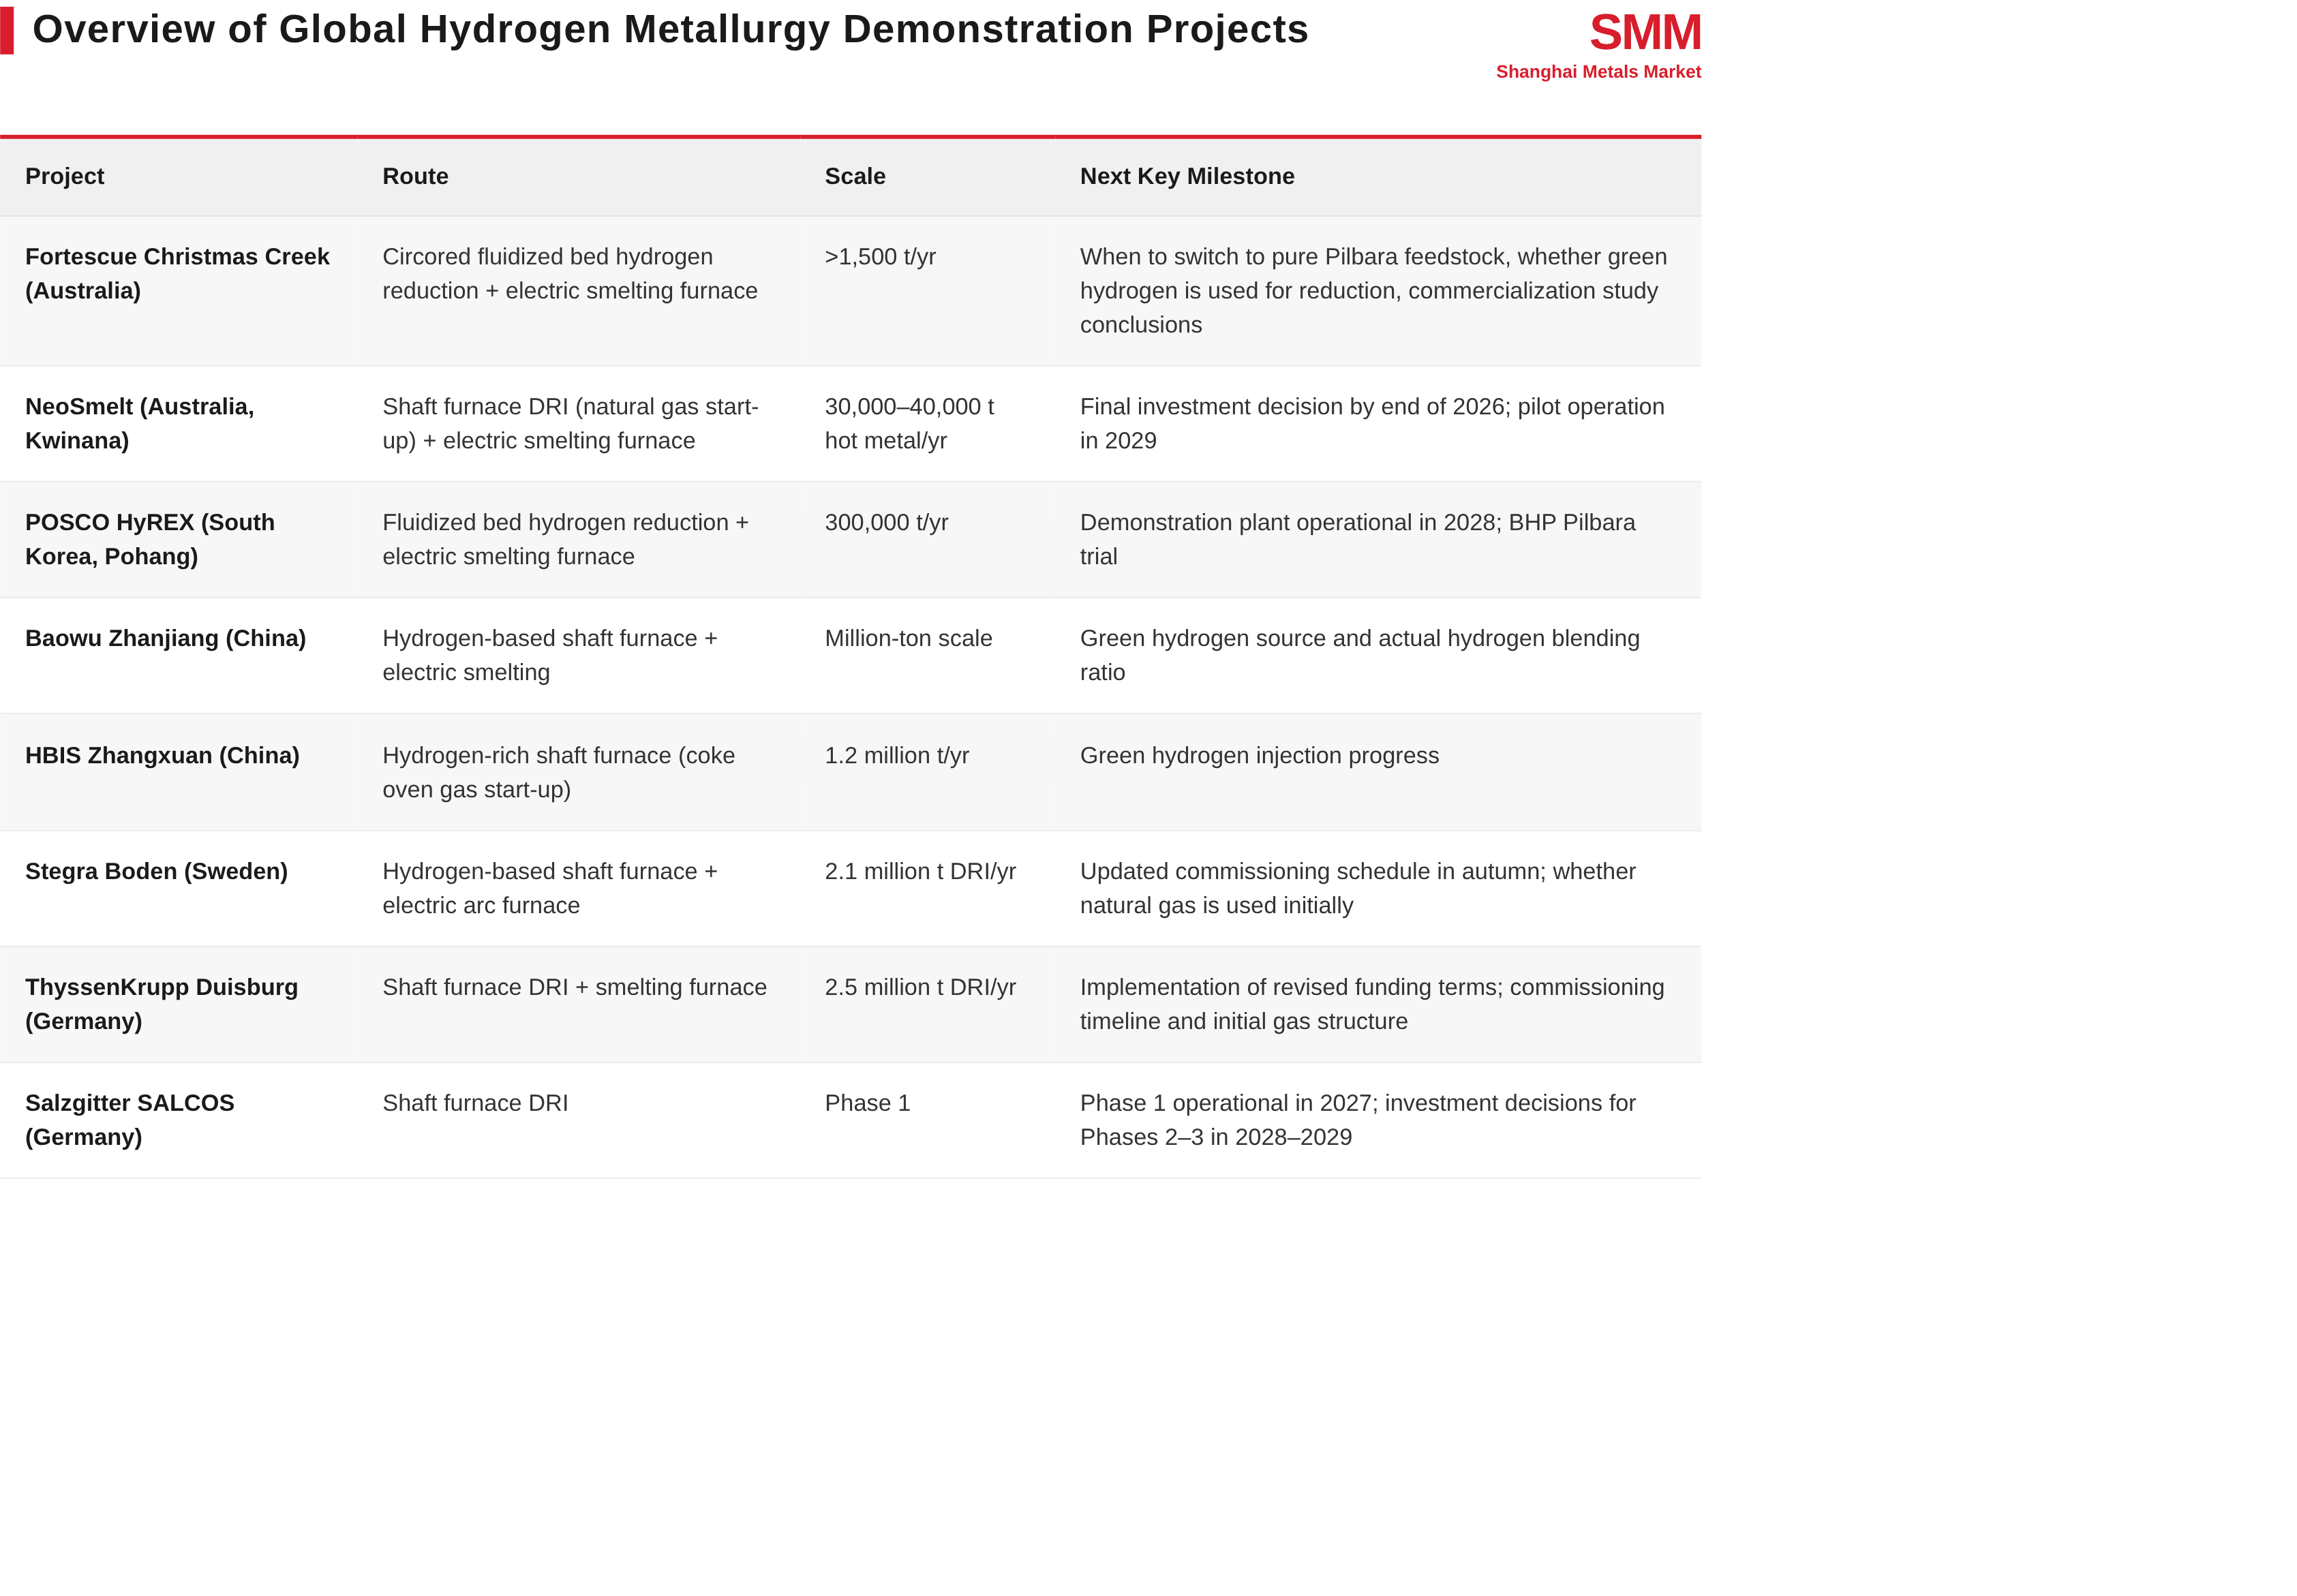
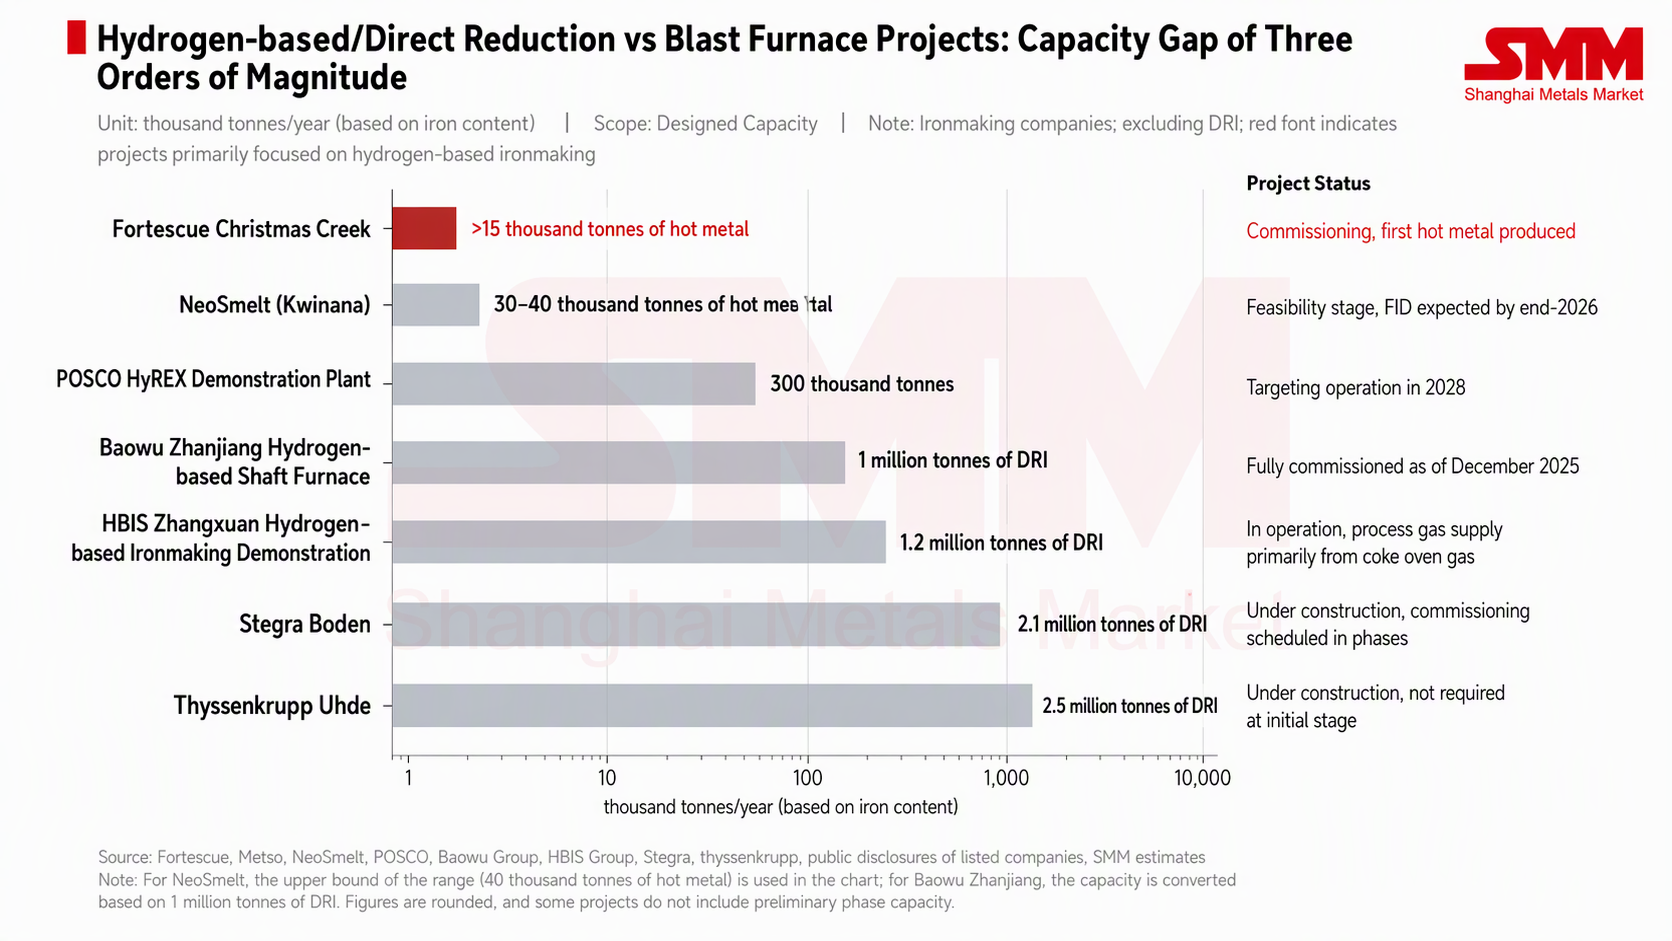
Over the past three years, three ESF projects directly related to Pilbara ore have either been launched or entered the planning stage: in addition to Fortescue's Christmas Creek, the other two are NeoSmelt in Australia and POSCO's HyREX in South Korea. NeoSmelt, comprising BlueScope, BHP, Rio Tinto, Mitsui, and Woodside, plans to build an ESF pilot plant in Kwinana with an annual output of 30,000-40,000 mt of hot metal, initially using natural gas for reduction and switching to hydrogen after commissioning; the consortium said in April that the project's commissioning date has been postponed from 2028 to 2029, with the final investment decision expected to be made at the end of 2026. POSCO's HyREX process also uses fluidized bed hydrogen reduction plus an ESF, can directly use fine ore, and targets commissioning of a 300,000 mt demonstration plant in 2028; BHP signed a memorandum with POSCO in November 2025 to trial Pilbara ore at the demonstration plant.
In terms of scale, the two projects of China Baowu and HBIS both reach the million-mt level. According to China Baowu, its near-zero carbon steel production line in Zhanjiang was fully connected in December 2025, using a hydrogen reduction-electric smelting process that cuts carbon emissions by 50%-80% compared with conventional processes; however, Baowu has not publicly confirmed the subsequent source of green hydrogen supply. HBIS's Zhangxuan hydrogen metallurgy demonstration project with an annual capacity of 1.2 million mt uses hydrogen-rich coke oven gas as the initial gas source, and the shaft furnace system has reserved the function to switch to green hydrogen.
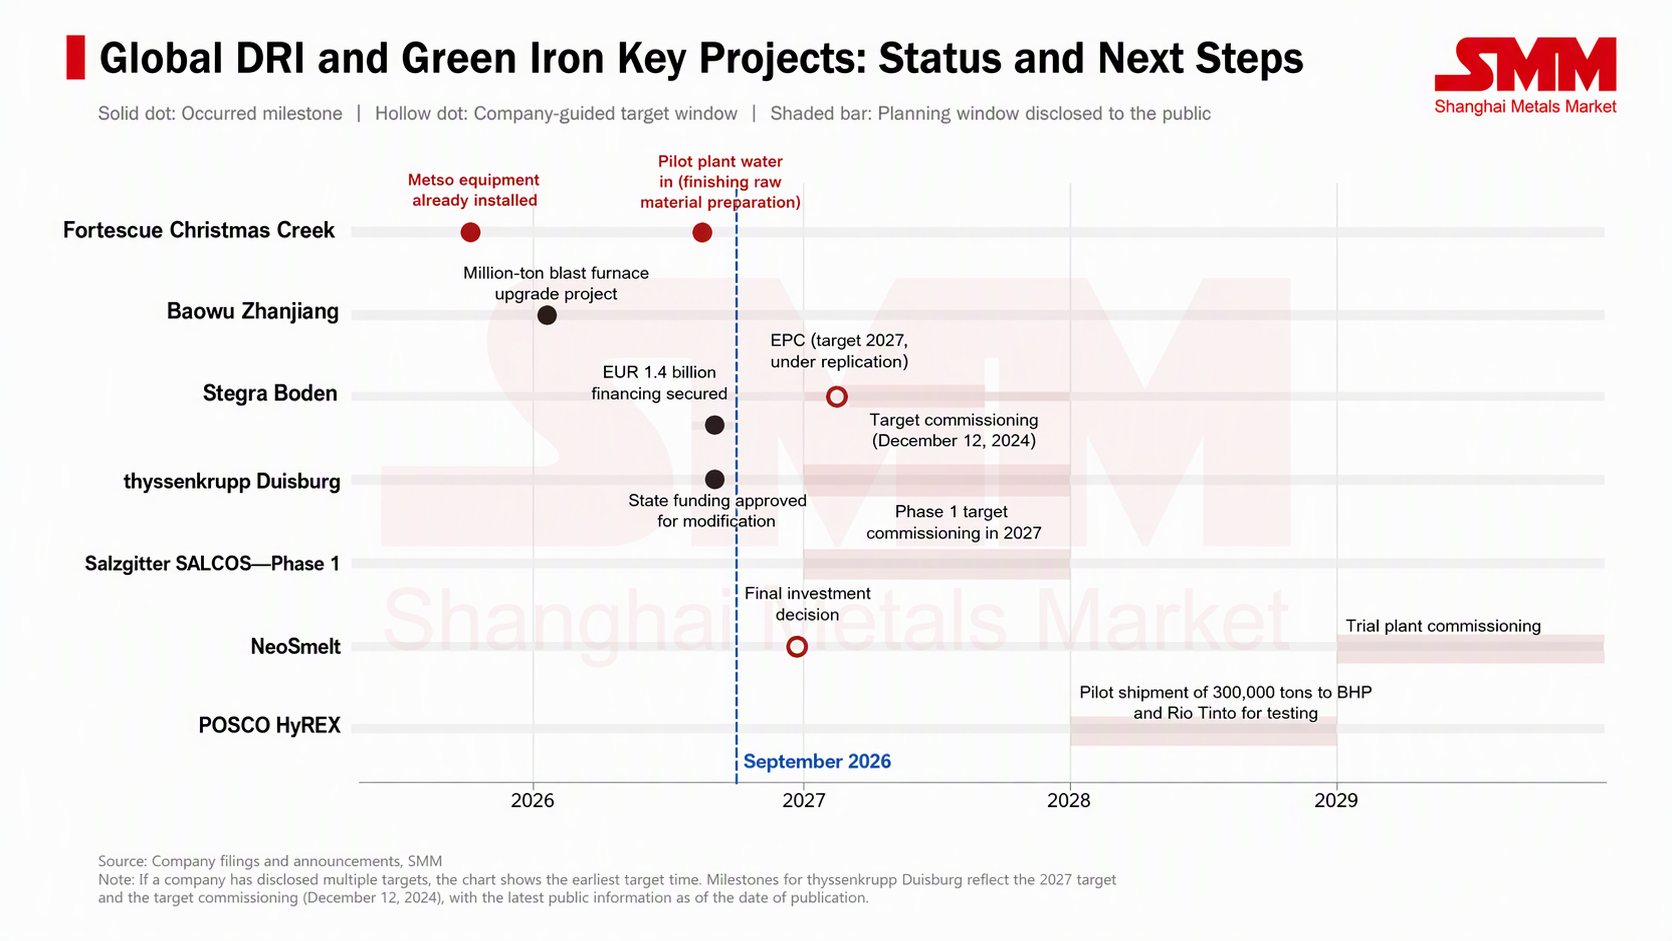
In Europe, ArcelorMittal, Thyssenkrupp, Salzgitter, and Stegra have successively adjusted their hydrogen-based projects in terms of hydrogen availability or commissioning schedules. ArcelorMittal abandoned hydrogen-based retrofits at its Bremen and Eisenhuttenstadt sites in Germany in June 2025, having already received 1.3 billion euros in subsidies, with the company saying that even a transition plan using natural gas-based DRI would not be competitive. About two-thirds of the roughly 3 billion euros in funding for Thyssenkrupp's Duisburg DRI project comes from the federal government and the state of North Rhine-Westphalia, with the funding terms originally tied to hydrogen use; in August, the EU approved changes to the funding rules allowing the project to operate without hydrogen initially, while the specific funding decision still awaits adjustment by the German government. Salzgitter’s SALCOS Phase 1 is still moving forward for commissioning in 2027, while investment decisions for Phases 2 and 3 have been postponed to 2028–2029. Stegra reached an agreement in principle on its €1.4 billion financing in April and completed the closing in June, but the originally planned commissioning time of early 2027 is still under review, and the company previously said it would update the timetable in the autumn.
Industry Implications and Key Projects to Watch
Returning to the iron ore market itself, Christmas Creek’s pilot-scale capacity of 1,500 mt per year will not affect supply and demand in the short term; its value lies in technology validation. From a long-term structural perspective, if the electric smelting furnace route proves viable at commercial scale, part of the low-carbon ironmaking demand that originally required DR-grade raw materials could instead be met by mid- and low-grade ores from the Pilbara, easing the scarcity constraint on high-grade raw materials. If operating indicators using purely Pilbara raw materials are not ideal, low-carbon smelting’s reliance on DR-grade resources will persist, providing more support for the structural premium on high-grade ore. Under the current landscape, however, grade price spreads are still typically driven by Chinese steel mill profits and ore blending structures, while low-carbon smelting demand is a long-term variable with limited impact on near-term pricing.
The periods worth tracking going forward are shown in the table below.