SMM, September 30: With the National Day holiday approaching, enterprises across the lead industry chain are making holiday arrangements. SMM surveyed 16 primary lead smelters across seven provinces regarding their holiday schedules, with enterprise scales (monthly lead ingot production) ranging from several thousand mt to over 10 kt and tens of thousands of mt. The National Day arrangements of major enterprises are as follows:
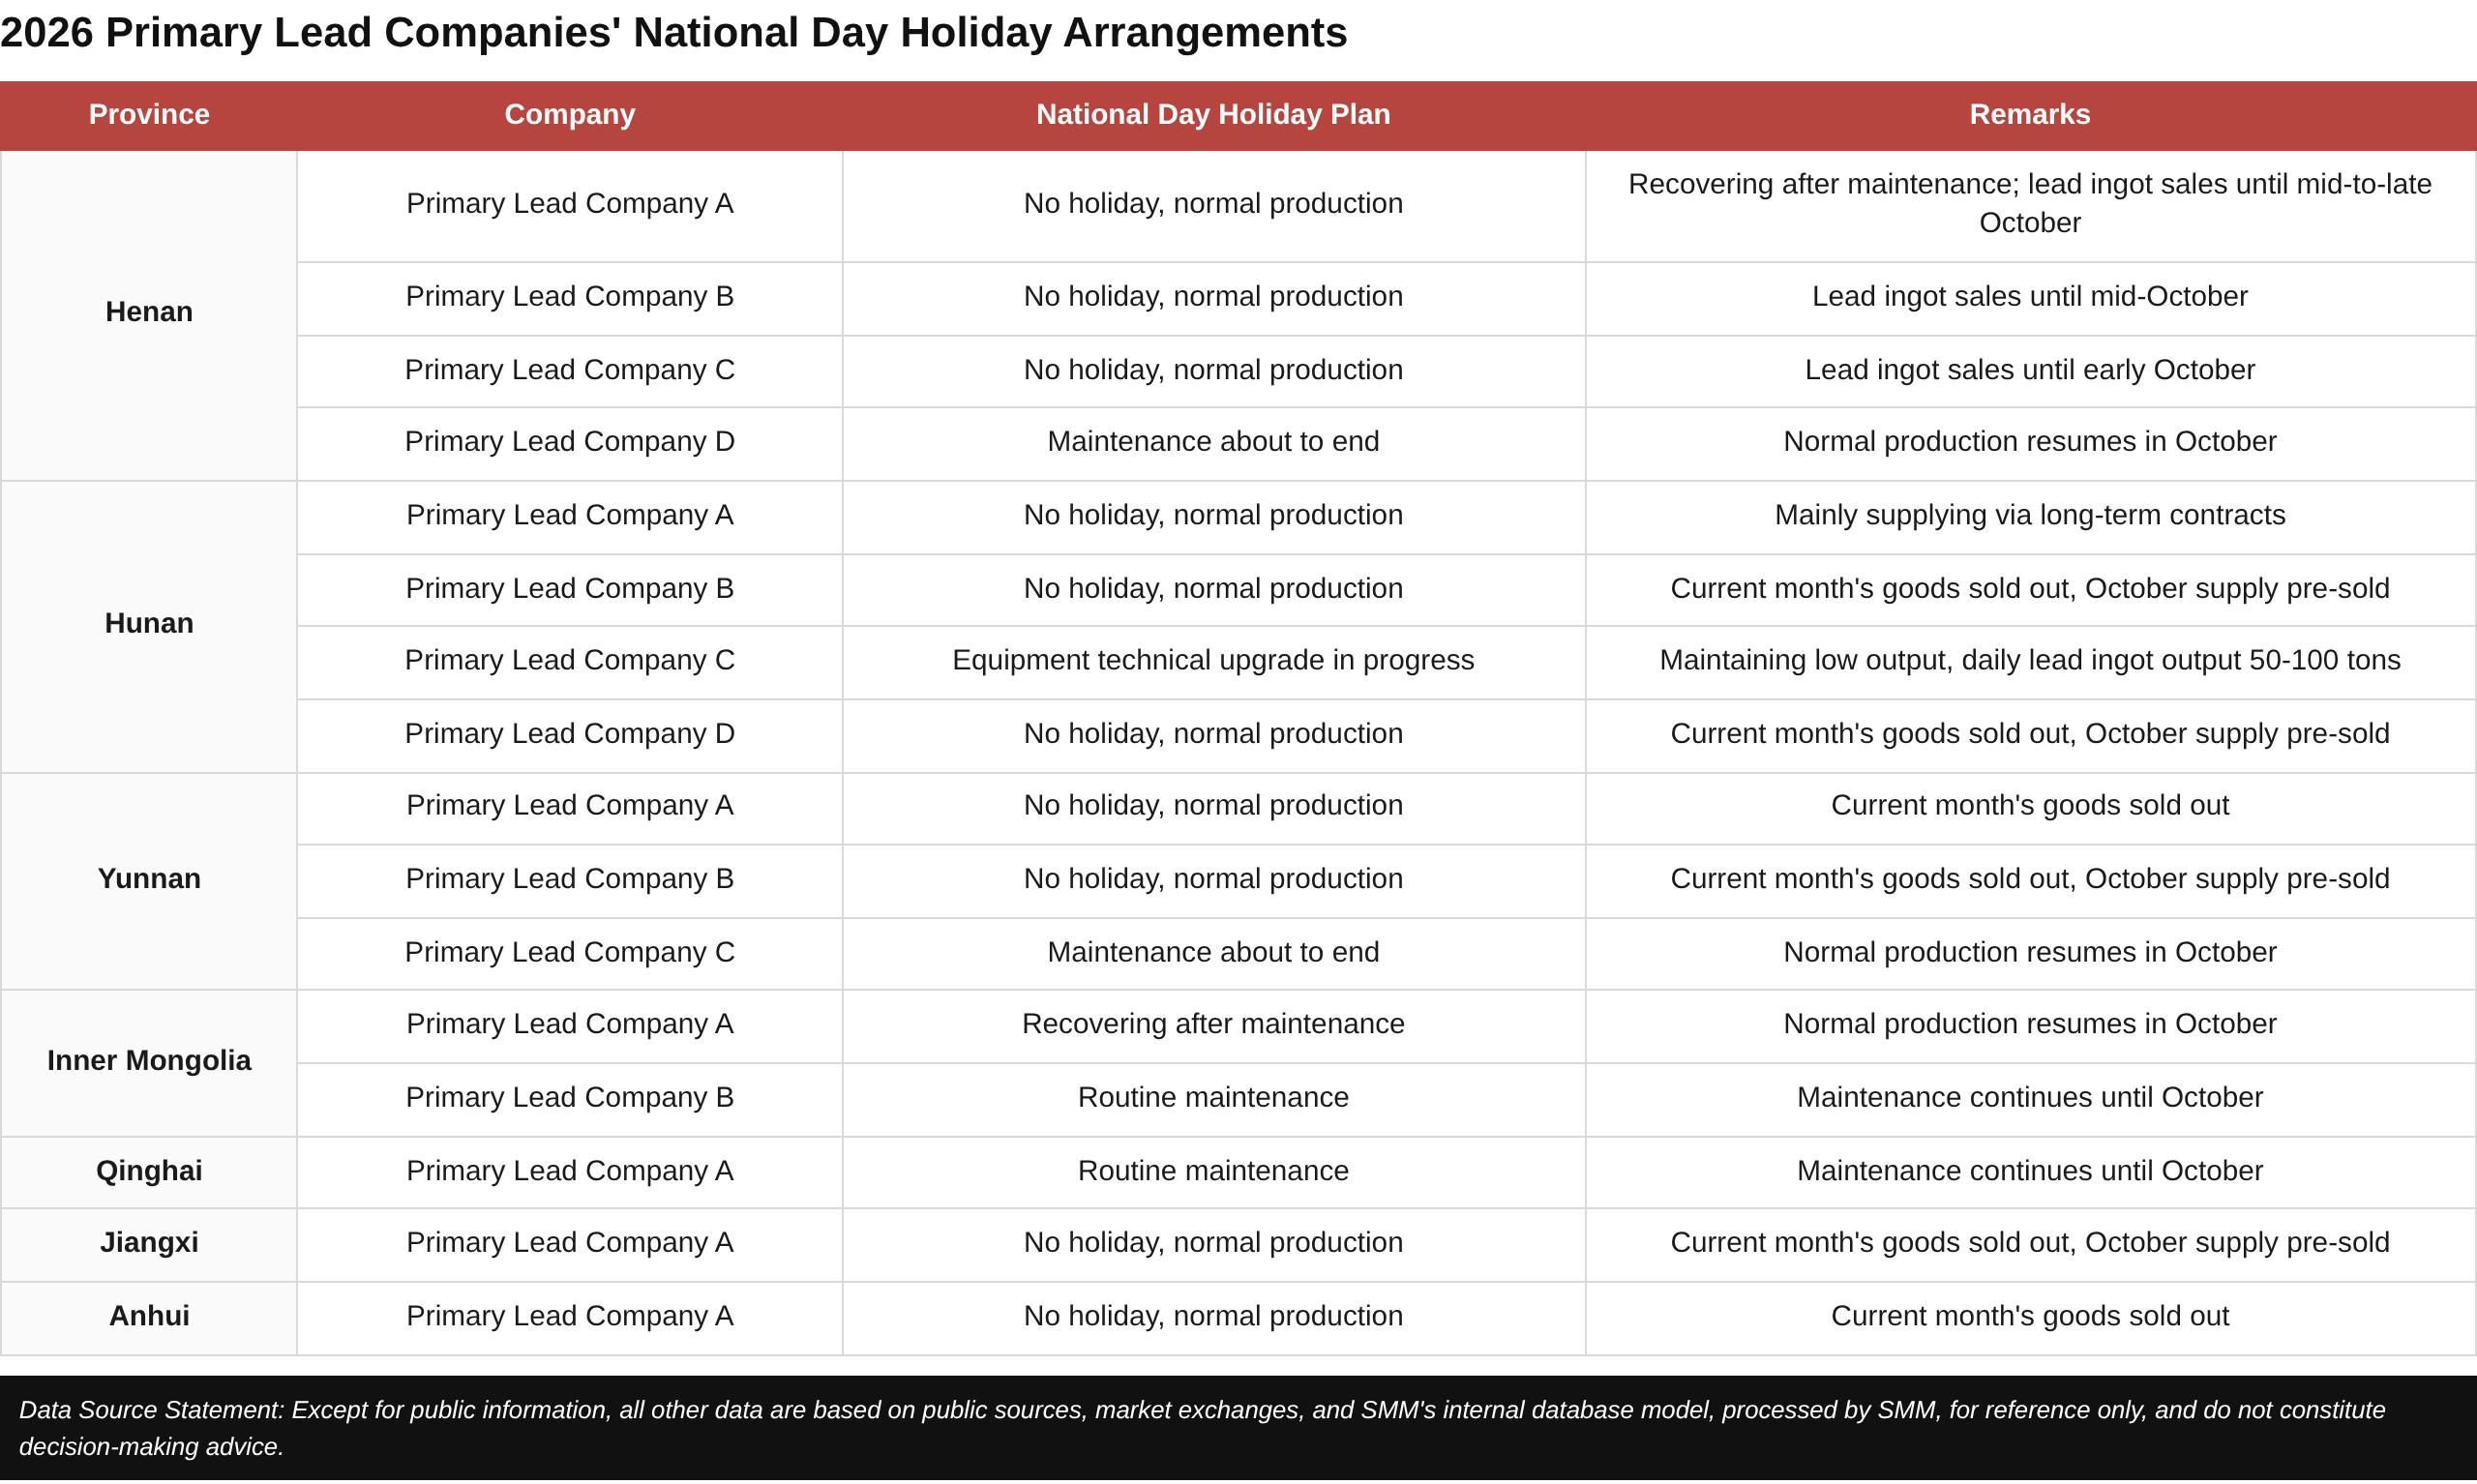
It is understood that mainstream primary lead smelters in China will not arrange full-plant shutdowns during the National Day holiday. Lead smelting systems will maintain continuous operation, with rotating shifts adopted to ensure stable production. Primary lead smelters in Henan, Inner Mongolia, Yunnan, and other regions that were previously under maintenance have completed equipment maintenance and are gradually resuming production, which is expected to bring growth in primary lead supply in October.
Primary lead smelting is a high-temperature continuous production industry. Once core processes such as smelting furnaces, electrolysis, and acid production are started, it is not advisable to shut down furnaces for holidays at will. Shutdown and restart costs are high, and there are significant safety risks. Under industry practice, production generally does not stop during long holidays. During this National Day holiday, large primary lead smelters in China have all formulated holiday production safeguard plans, implementing 24-hour three-shift duty systems, strengthening on-site safety inspections, environmental protection operations, and raw material supply guarantees to ensure stable output of main and by-products such as lead ingot and sulphuric acid, while also providing logistical support for on-duty personnel to uphold the bottom line of safe production.
From a regional perspective, some primary lead enterprises in China arranged equipment maintenance according to annual plans in August-September. Maintenance work at multiple primary lead smelters in Henan, Inner Mongolia, Yunnan, and other regions concluded in mid-to-late September, with related production lines gradually resuming feed and production, and capacity being steadily released. With the return of this maintained capacity, the overall operating rate of primary lead in China will rise.
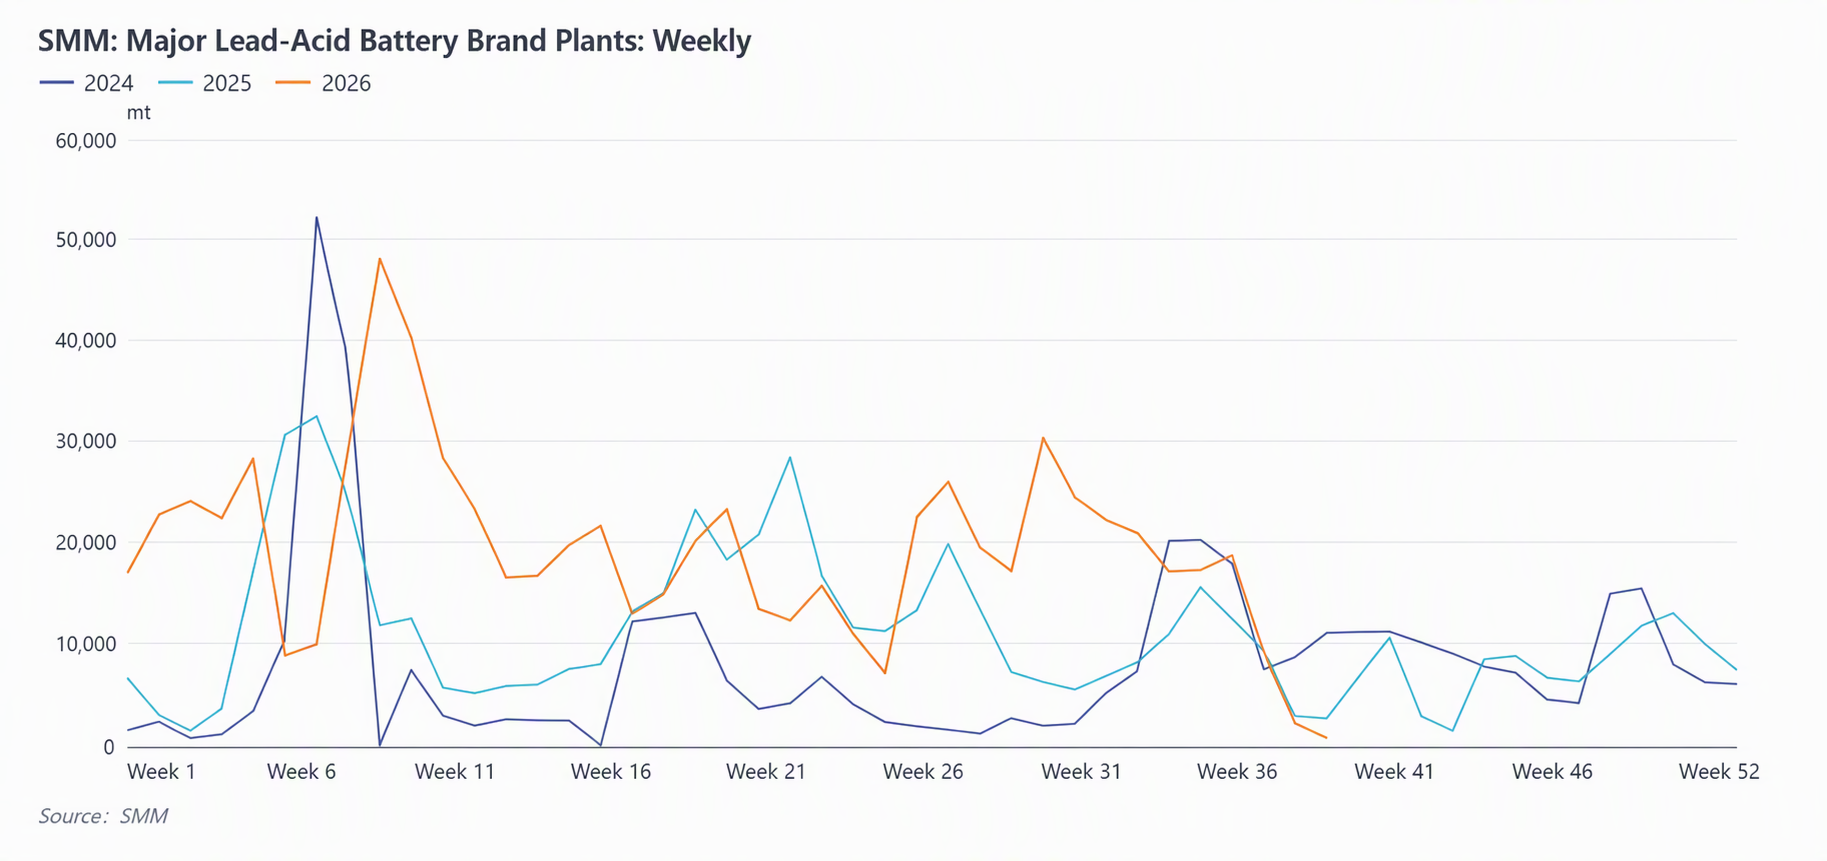
From a market perspective, downstream lead-acid battery enterprises have largely completed pre-holiday stockpiling, and spot transactions during the long holiday may tend to be sluggish. Finished product inventory pressure at smelters will become a key market focus after the holiday. It is understood that multiple smelters have pre-sold October cargoes in advance, with most enterprises pre-selling up to the National Day holiday, and a few pre-selling to mid-October or even mid-to-late October. It is expected that smelter inventory buildup pressure after this National Day holiday will be lower YoY.