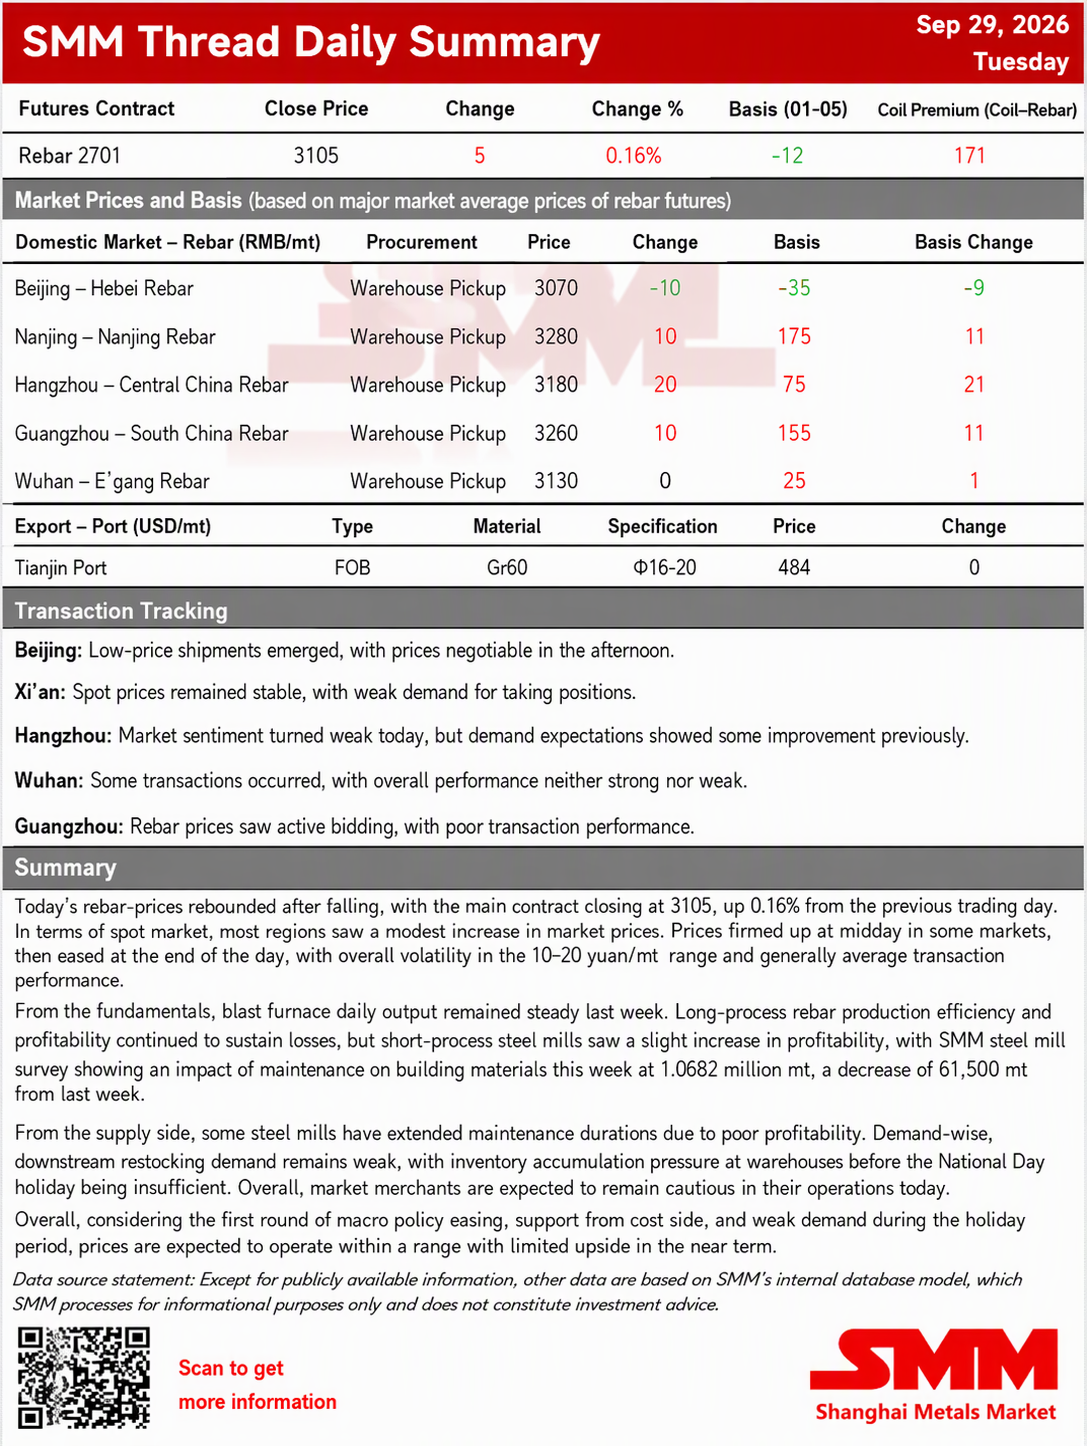
Today, rebar futures rose before pulling back, with the most-traded contract closing at 3,105, up 0.16% from the previous trading day. In the spot market, quotes in most regions edged up slightly in early trading, while some markets saw slight downward adjustments at the lower end of prices in the afternoon to accelerate shipments. Prices fluctuated within a range of 10-20 yuan/mt throughout the day, and overall transaction activity was moderate. From a fundamental perspective, on the supply side, although blast furnace steel mills continued to incur losses in producing construction steel, some mills resumed production on schedule for previously idled rolling lines after maintenance. According to an SMM survey, the impact from maintenance on construction steel this week totaled 1.0682 million mt, down 61,500 mt WoW. On the EAF side, some mills faced difficulties in scrap procurement ahead of the holiday, and production profitability worsened compared with earlier, prompting some to reduce operating hours. On the demand side, downstream restocking demand before the holiday has largely concluded, and some traders in certain markets have already begun their holiday break, leading to a day-on-day weakening in overall transactions today. In summary, the first round of coke price cuts has been initiated, shifting cost support lower. Combined with the lack of notable improvement in pre-holiday demand, upward price momentum remains limited. Spot prices are expected to consolidate ahead of the holiday.