[SMM Analysis]Coke’s Upward Momentum Fades Price Cut Expected in October

Published: Sep 29, 2026 16:49 (GMT+8)

The coke market in September maintained high‑level stalemate with slowing price gains. The core conflict lay in the interplay between cost support from coking coal and restraint stemming from steel mill losses. Following several rounds of price hikes implemented in early September, losses at coking enterprises narrowed, and coking operating rates edged higher. On the supply side, ongoing safety supervision at coal mines in major producing regions kept high‑grade primary coking coal relatively tight, forming floor support for coke. Coking enterprises held low inventories in the early period and showed strong willingness to defend prices. On the demand side, hot‑metal output stayed elevated, coupled with rigid restocking by steel mills ahead of the National Day holiday, which underpinned spot prices on a temporary basis. Nevertheless, end‑user finished‑steel demand under the traditional “Golden September” failed to meet expectations. Steel mill profitability kept deteriorating, raising resistance to high‑priced coke. The sixth round of proposed price hikes failed to materialize. Mid‑to‑late September saw the market shift from a price‑rising phase to sideways consolidation, with limited room for further price advances. Toward month‑end, pre‑holiday restocking wound down, shipments from coking enterprises slowed, and industrial‑chain inventories built up marginally. The market began pricing in blast‑furnace maintenance at steel mills and expectations for the first round of coke price cuts. Overall, coke price levels moved higher in September yet upward momentum gradually ebbed. Profit recovery for coking enterprises brought about marginal supply release, while downstream steel mills faced mounting loss pressure. The tight supply‑demand balance loosened marginally, and market logic shifted from supply contraction to demand‑side validation.
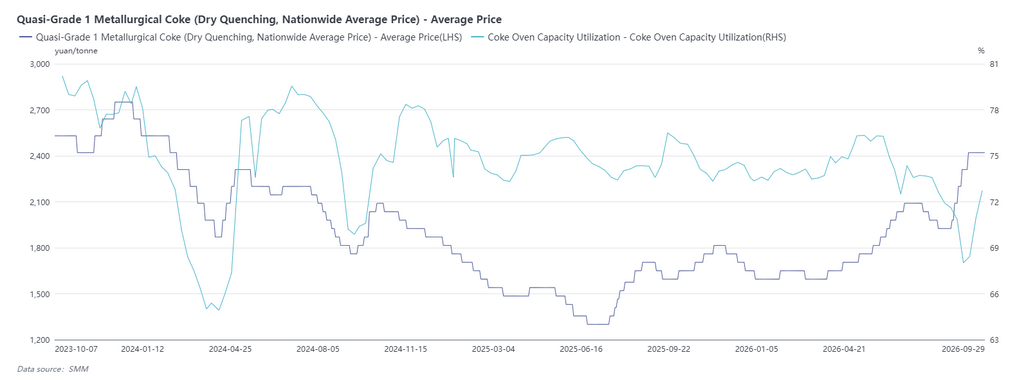
Looking ahead to October, coke will most likely trend sideways‑to‑weaker with risks of periodic corrections. On the supply side, coking enterprises retain flexible operating rates after profit improvements in September. Should prices stay high, coke output may see further increases. On the coking‑coal front, previously constrained mines resume production in an orderly manner, easing tightness in coking‑coal supplies and weakening cost support. Demand will serve as the core driver shaping market performance. In October, should end‑user steel demand for the traditional “Silver October” continue to disappoint, steel‑mill losses will persist, the scope of blast‑furnace maintenance may expand, hot‑metal output will decline, and rigid coke demand will recede. After the National Day holiday, pre‑holiday restocking by steel mills will be complete. Proactive purchasing sentiment will cool, steel mills will be more inclined to push coke prices lower, and steel mills will gain greater pricing power. From an inventory perspective, industrial‑chain inventories are expected to build after pre‑holiday restocking, adding further downward pressure on spot prices. That said, uncertainties remain surrounding coal‑mine safety inspections. Should safety supervision tighten anew, coking coal and coke prices will receive periodic support, limiting the scope of sharp declines.

Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[Stelco to idle Hamilton finishing operations, cut up to 500 jobs on US tariffs]
3 mins ago
[Stelco to idle Hamilton finishing operations, cut up to 500 jobs on US tariffs]
Read More
[Stelco to idle Hamilton finishing operations, cut up to 500 jobs on US tariffs]
[Stelco to idle Hamilton finishing operations, cut up to 500 jobs on US tariffs]
Stelco Holdings Inc. will indefinitely idle finishing operations at its Hamilton, Ontario plant, affecting up to 500 workers across Hamilton and Lake Erie. The company said the move was 'unfortunate but necessary', citing US tariffs that have cut demand for its cold rolled and galvanized products. Demand in its traditional markets fell almost 25% in Q2 2026 vs the 2024 quarterly average, with Canada down 10%. Ottawa's import curbs have cut volumes but not enough to close the gap. Production will be concentrated at the Lake Erie Works in Nanticoke, Ontario. Parent Cleveland-Cliffs said the product mix will change but steel tonnage will not, and will offer Hamilton staff Lake Erie roles. Peer Algoma Steel announced over 1,000 layoffs; ArcelorMittal Long Products Canada shut its Hamilton wire drawing mill.
3 mins ago
[Italian steel association Federacciai warns rising energy costs threaten production continuity, urges EU ETS suspension]
3 mins ago
[Italian steel association Federacciai warns rising energy costs threaten production continuity, urges EU ETS suspension]
Read More
[Italian steel association Federacciai warns rising energy costs threaten production continuity, urges EU ETS suspension]
[Italian steel association Federacciai warns rising energy costs threaten production continuity, urges EU ETS suspension]
Italy's steel association Federacciai warned that soaring energy costs are threatening the continuity of domestic steel production and urged the EU to suspend its Emissions Trading System (ETS). It said the combined burden of high electricity prices and carbon costs has left Italian mills, particularly electric arc furnace operators, facing unsustainable pressure, with some lines at risk of shutdown. Federacciai called on the EU and the Italian government to take emergency measures, including halting ETS allowance auctions and adjusting carbon cost pass-through rules, to protect steel supply and jobs. Spanish peer Unesid also warned of a 658 million EUR energy cost overrun (about 710 million USD) and sought an emergency plan. Source: Federacciai.
3 mins ago
[EU proposes cutting Egypt off from EU-origin steel scrap from 2027]
3 mins ago
[EU proposes cutting Egypt off from EU-origin steel scrap from 2027]
Read More
[EU proposes cutting Egypt off from EU-origin steel scrap from 2027]
[EU proposes cutting Egypt off from EU-origin steel scrap from 2027]
The European Commission proposes barring Egypt from importing EU-origin ferrous and non-ferrous scrap once the revised Waste Shipment Regulation fully takes effect on 21 May 2027. Egypt, with India, Pakistan, Morocco, Bangladesh and Saudi Arabia, failed to prove environmentally sound waste management. Egypt imported 1.86 million tonnes of EU scrap in 2025 and 2.12 million tonnes in H1 2026, up 59.7% y-o-y, ranking third globally; about half its ferrous scrap supply comes from the EU. Mills would need alternative scrap or more DRI: European freight is 20-25 USD/tonne versus 35-40 USD/tonne from China or the US. Egypt has also lost 213 million USD of steel exports to EU and US anti-dumping measures. Feedback closes 16 October; adoption is planned for Q4 2026.
3 mins ago