[SMM Analysis] The U.S. Copper Tariff Trade Is Fading — but It Isn’t Over Yet

Published: Sep 29, 2026 14:37 (GMT+8)
[SMM Analysis] No U.S. refined copper tariff announcement emerged by midday on September 29, but policy risk remains. As the COMEX-LME spread narrowed, near-term arbitrage and the U.S. pull weakened. Yet COMEX stocks have risen from 320,000 to nearly 770,000 short tons, while China’s social inventories fell to 78,300 mt and SMM #1 cathode premiums approached $205/mt (RMB 1,400/mt). Could tariff uncertainty revive the longer-term U.S. pull?

Markets had circled noon Beijing time on September 29 as a key checkpoint for a possible U.S. tariff on refined copper. The date was derived from a copper market update submitted by the U.S. Department of Commerce on June 30: applying Section 232’s 90-day timeline would have taken the presidential decision window to September 28, U.S. time.

However, the update was required under the existing copper tariff proclamation and was not explicitly designated as a new formal Section 232 investigation report. The president’s written explanation may also be published after a decision has been made. The absence of an announcement by noon therefore should not be read as confirmation that the tariff proposal has been dropped.

The U.S. had previously considered a 15% tariff on refined copper imports in 2027, rising to 30% in 2028. If the White House leaves that phased tariff schedule on the table without finalizing the details, the policy risk alone could continue drawing global copper into the U.S. through 2027.

Traders looking to capture future dislocations between COMEX and LME prices would continue moving cathode into U.S. exchange warehouses, bonded facilities and commercial storage. This would allow the U.S. to build a sizeable copper stockpile without direct government funding: private traders would absorb the procurement, financing and storage costs. In effect, tariff expectations could turn privately held copper into a de facto strategic reserve.
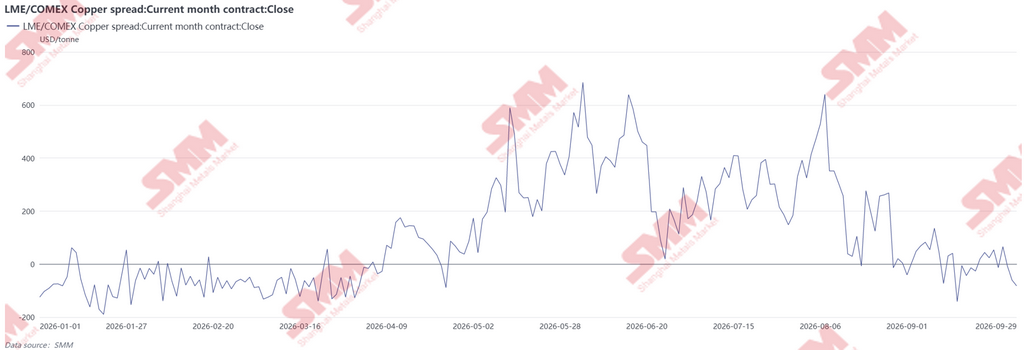
For now, however, the market structure points to a weaker near-term pull. COMEX remains in contango, consistent with ample nearby supply in the U.S., while LME copper remains in backwardation, indicating tighter prompt availability elsewhere. Cross-market spreads have narrowed steadily since late August. The October 2026 COMEX contract traded at a discount of $46.94/mt to LME three-month copper, while the November 2026 contract carried a premium of just $38.99/mt. Neither spread is sufficient to cover freight, financing, storage and exchange-delivery costs, effectively closing the arbitrage window for additional physical shipments into the U.S. If the market had received a firm signal that tariffs were imminent, longer-dated COMEX premiums would likely have widened sharply. That has not happened. The current spread structure suggests that the U.S. pull on global copper is losing momentum and that traders remain unconvinced about the significance of the end-September deadline.
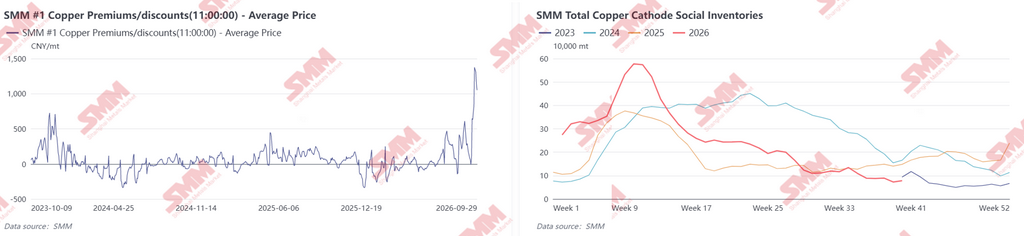
The resulting regional imbalance is already visible in China’s physical market. The SMM #1 copper cathode premium recently approached approximately $205/mt (RMB 1,400/mt), its highest level since October 2023. This rise cannot be attributed to stronger consumption alone. Section 232 tariff expectations have redirected copper towards the U.S., reducing LME stocks in Asia and limiting the volume of imported cathode available to China. Domestic supply has tightened accordingly, with SMM-tracked social inventories falling to a multi-year low of 78,300 mt. Tradable recycled copper feedstock has also become scarce, weakening its ability to substitute for refined copper. At the same time, Chinese fabricators accelerated procurement and restocking ahead of the Mid-Autumn Festival and National Day holidays. The global diversion of copper towards the U.S. provided the underlying support for higher spot premiums, while pre-holiday buying acted as the immediate catalyst.
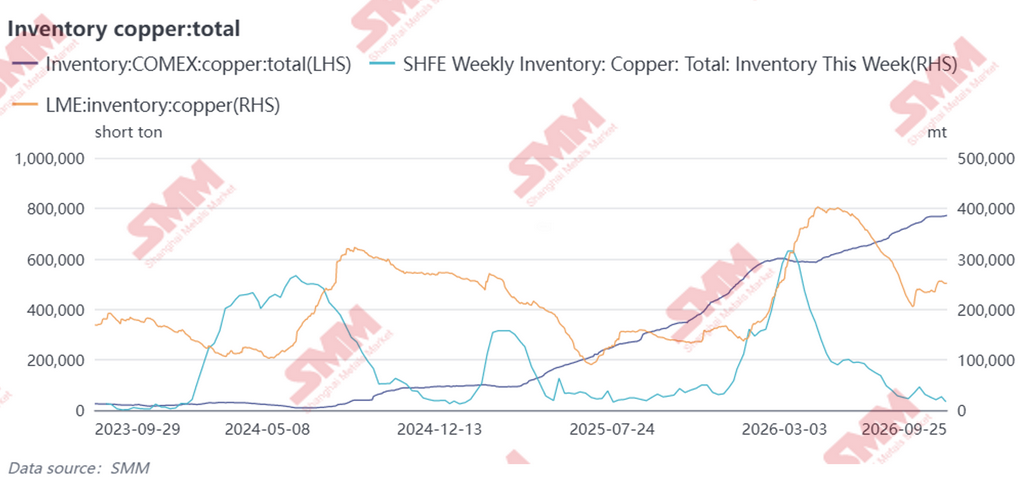
Inventory movements illustrate the scale of the shift. Between September 2025 and September 2026, COMEX copper stocks rose from approximately 320,000 short tons to nearly 770,000 short tons, more than doubling within a year. Over the same period, LME inventories fell from an interim peak of about 400,000 mt in April 2026 to roughly 250,000 mt. SHFE stocks declined even more sharply, from 359,100 mt at the end of March to 47,100 mt on September 24. The direction of travel is clear. Tariff expectations and earlier COMEX premiums pulled cathode from South America, Africa and other producing regions into the U.S., reducing freely available supply elsewhere. The combination of continued stockbuilding in the U.S. and sustained inventory drawdowns across China and the wider Asian market has been a major driver of the recent surge in Chinese spot premiums.

For the global copper market, delaying a final tariff decision may prolong the regional dislocation rather than unwind it. Even if incremental shipments into the U.S. have slowed, the copper already accumulated there is unlikely to return quickly given the cost of financing, handling and re-exporting the metal. Until the White House clearly steps back from tariffs on refined copper, policy uncertainty will keep those stocks anchored in the U.S. and preserve the prospect of renewed inflows if forward COMEX premiums widen again. That would further tighten available supply outside the U.S. and continue to provide support to global copper prices.

Currency conversion is based on the CFETS central parity rate on September 29, 2026: USD 1 = RMB 6.8166.


Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
KGHM and South32 launch US$725m Sierra Gorda expansion, lifting copper capacity 26%
2 hours ago
KGHM and South32 launch US$725m Sierra Gorda expansion, lifting copper capacity 26%
Read More
KGHM and South32 launch US$725m Sierra Gorda expansion, lifting copper capacity 26%
KGHM and South32 have broken ground on a fourth grinding line at the Sierra Gorda copper-molybdenum mine in Chile's Atacama region. The US$725 million expansion runs for three years from January 2027, with completion by late 2029 and full output in H2 2030. Ore processing capacity rises 26%, from 131,000 tonnes per day to 165,000 tpd. Annual copper output is projected to climb from 165,000 tonnes in 2025 to 195,000 tonnes, with 6,000 tonnes of molybdenum, 58,000 ounces of gold and 1.7 million ounces of silver as by-products. The project creates over 900 direct jobs and is funded from operating cash flow and debt. Unit operating costs are expected to fall about 10%.
2 hours ago
Emerita Extends Final Review of Iberian Belt West PFS, Release Expected in Coming Weeks
3 hours ago
Emerita Extends Final Review of Iberian Belt West PFS, Release Expected in Coming Weeks
Read More
Emerita Extends Final Review of Iberian Belt West PFS, Release Expected in Coming Weeks
Emerita Resources has provided an update on the Preliminary Feasibility Study (PFS) for its Iberian Belt West polymetallic project in Spain, saying the study is well advanced but remains under final technical review.​ The company said the review process has been expanded to include additional technical and quality-assurance oversight before publication. As a result, Emerita now expects the PFS to be released in the coming weeks rather than within the previously indicated timeframe.​ Iberian Belt West hosts copper, zinc, lead, gold and silver mineralization and is one of Emerita’s principal development-stage assets in Spain. The PFS is expected to provide updated detail on the proposed mine plan, processing configuration, capital requirements, operating costs and project economics.​ Emerita said the additional review work is intended to ensure consistency and completeness across the technical disciplines contributing to the study before it is finalized.​ The company did not announce a revised specific publication date, and no new production, capital or economic figures were disclosed in the latest update.​ The extended review delays the next major technical milestone for Iberian Belt West, but the company continues to indicate that the PFS is nearing completion. For the copper market, the significance of the study will depend on the production profile and project economics ultimately disclosed, particularly the contribution of copper relative to the project’s other payable metals. Attention will therefore remain on the timing of the PFS release and whether the final study materially changes the project’s development outlook.
3 hours ago
Cascadia Intersects 75.55 m at 1.19% Cu at Carmacks Copper-Gold Project
3 hours ago
Cascadia Intersects 75.55 m at 1.19% Cu at Carmacks Copper-Gold Project
Read More
Cascadia Intersects 75.55 m at 1.19% Cu at Carmacks Copper-Gold Project
Cascadia Minerals has reported additional drill results from its 2026 exploration programme at the Carmacks copper-gold project in Yukon, Canada, with new step-out drilling extending mineralization at Zone 2000S beyond the boundaries of the existing Mineral Resource.​ Drill hole CD-26-058 returned 75.55 metres grading 1.19% copper, 0.97 g/t gold, 10.4 g/t silver and 335 ppm molybdenum, equivalent to 2.18% copper-equivalent. The interval included 48.66 metres grading 1.61% copper, 1.39 g/t gold, 15.1 g/t silver and 475 ppm molybdenum, equivalent to 3.03% CuEq.​ Within the same hole, a higher-grade interval of 14.50 metres returned 2.30% copper, 2.68 g/t gold, 29.5 g/t silver and 1,015 ppm molybdenum, equivalent to 5.08% CuEq.​ A second hole, CD-26-059, intersected 93.99 metres grading 0.96% copper, 0.70 g/t gold, 4.6 g/t silver and 919 ppm molybdenum, equivalent to 1.94% CuEq. This included 63.97 metres at 1.26% copper, 0.96 g/t gold, 6.3 g/t silver and 1,049 ppm molybdenum, equivalent to 2.52% CuEq.​ Cascadia said the latest results continue to expand mineralization at Zone 2000S beyond the limits of the current Mineral Resource and highlight the higher-grade nature of the extension. The reported drill intervals represent drilled thicknesses, with true widths estimated at approximately 60–70%.​ The latest step-out results indicate that copper-gold mineralization at Zone 2000S extends beyond the boundaries of the current Carmacks Mineral Resource. The broad intervals and higher-grade internal zones could support future resource expansion if additional drilling confirms continuity. However, the new intersections have not yet been incorporated into an updated Mineral Resource Estimate, meaning their ultimate impact on project scale and mine planning remains to be determined.
3 hours ago

