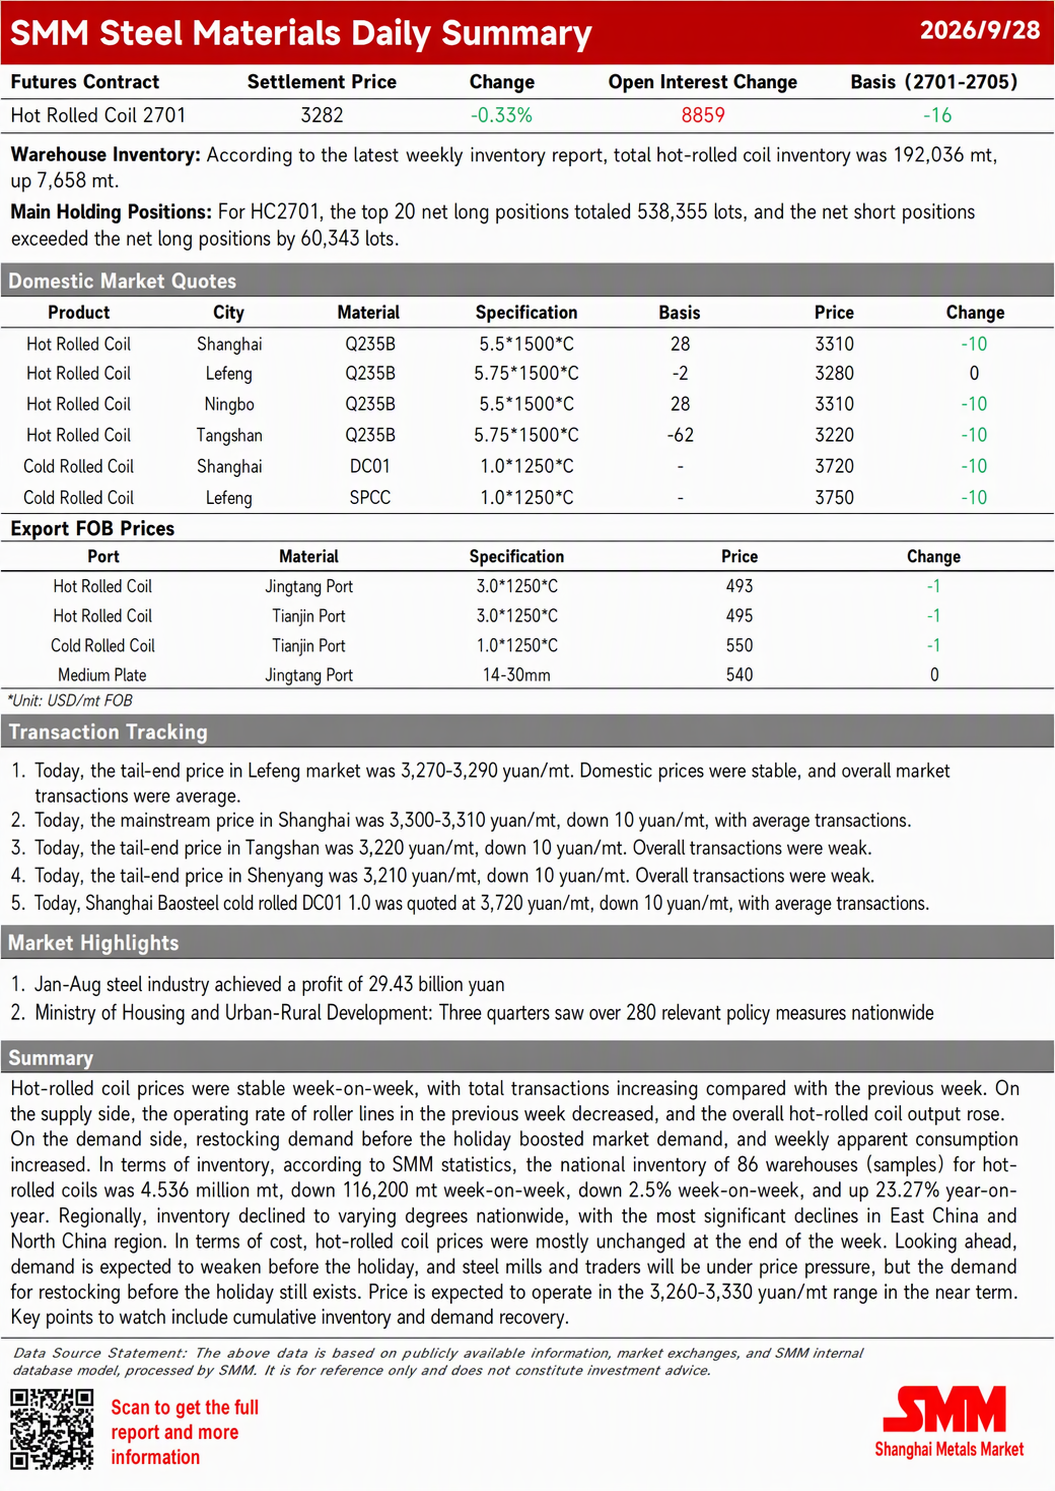
Last week, HRC prices were basically flat WoW, while overall trading volume increased from the previous week. In terms of supply, the impact from rolling line maintenance decreased WoW, and overall HRC production rebounded. On the demand side, pre-holiday restocking demand surged, driving apparent demand up WoW. In terms of inventory, SMM data showed HRC social inventory across 86 warehouses nationwide (large sample) at 4.5356 million mt, down 116,200 mt WoW, or -2.5% WoW, and up 23.27% YoY on a calendar-year basis. By region, inventory declined to varying degrees nationwide, with the most notable drops in Central and North China. On the cost side, cost support for HRC showed no significant change last week. Looking ahead, pre-holiday peak-season demand remains weak, and steel mills and traders are under price pressure. However, with the extended National Day holiday, pre-holiday restocking demand still provides support. Prices are expected to hold firm and consolidate around current levels, with the most-traded contract likely to trade in the 3,260-3,330 range. After the holiday, close attention should be paid to inventory buildup and demand recovery.