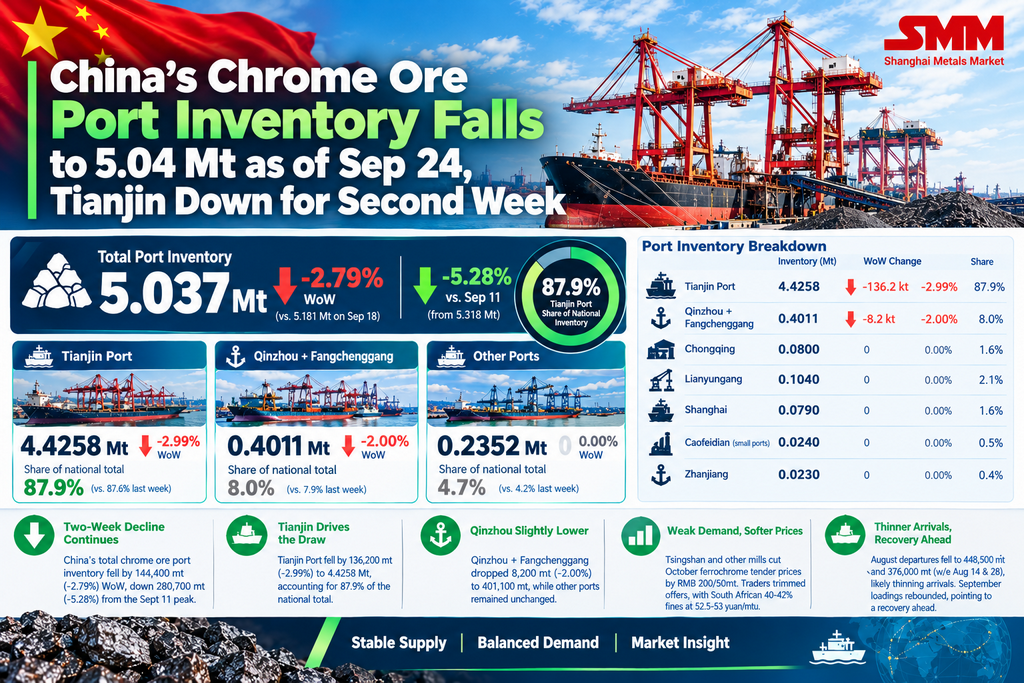
As of September 24, 2026, China's total chrome ore inventory at ports fell to 5.037 million mt, down 144,400 mt (-2.79%) from September 18, the second straight weekly decline. Stocks are now down 280,700 mt (-5.28%) from the September 11 peak, essentially erasing the two-week build.
Tianjin Port drove the draw, falling 136,200 mt (-2.99%) to 4.4258 million mt, or 87.9% of the national total. Qinzhou plus Fangchenggang slipped 8,200 mt (-2.00%) to 401,100 mt, while all other ports were unchanged.
The decline came despite weak demand, as Tsingshan and other major mills cut October ferrochrome tender prices by RMB 200 per 50mt unit and held back restocking. Traders trimmed offers to clear cargoes ahead of the holidays, with South African 40-42% fines at Tianjin at 52.5-53 yuan/mtu, while limited ferrochrome output cuts kept smelters drawing on port stocks. Softer mid-to-late August departures, at 448,500 mt and 376,000 mt in the weeks ended August 14 and 28, also likely thinned arrivals, though the September rebound in loadings points to a recovery ahead.