

━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━━
SMM ANALYSIS | AFRICA COPPER
Sulphuric Acid Shortage Emerges as a Constraint on Zambia’s Copper Growth
Tight domestic acid availability is already showing up in policy action, small-scale mining weakness and refinery cost pressure, with Jubilee Metals reporting a more than 200% increase in acid costs during Q4 FY2026.
25 September 2026 | SMM Analysis
|
>200% Q4 FY2026 acid cost increase Jubilee Metals |
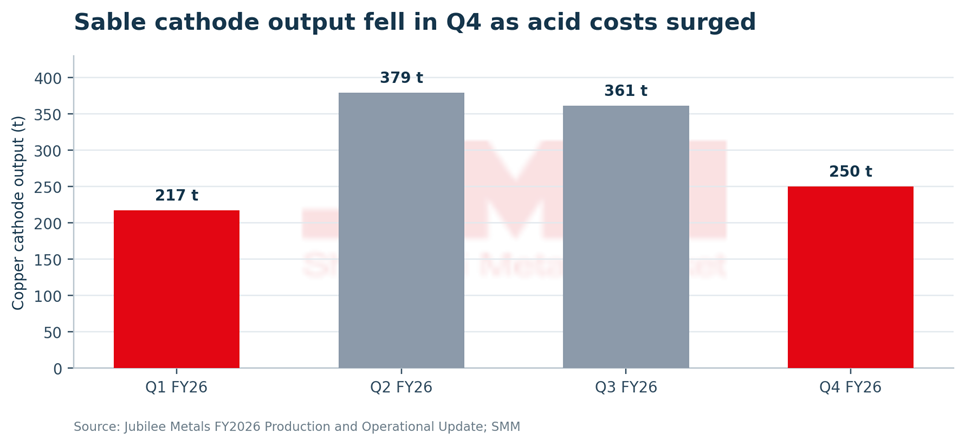
250 t Sable Q4 cathode output down from 361 t in Q3 |
-35.2% Small-scale copper production Zambia H1 2026 YoY |
~1.1 Mt Kansanshi acid output 2025 production |
Zambia’s copper sector is expanding investment and processing capacity, but sulphuric acid availability is becoming a visible constraint for parts of the domestic value chain. Ministry of Mines data show national copper production rising only 0.45% year on year to 447,181 t in H1 2026, while small-scale copper production fell 35.2%. The Ministry attributed the small-scale decline partly to inadequate domestic sulphuric acid supply and the delayed end of the rainy season.
Recent company disclosures add a more immediate operating signal. Jubilee Metals reported that domestic acid availability in Zambia reduced significantly during Q4 FY2026, with acid costs rising by more than 200% and diesel costs increasing by 90%. The company said these conditions had a marked impact on production at its Sable Refinery and contributed to temporary closures among some metal processors in its operating area.
┃ Jubilee data show pressure reaching the refining stage
Sable produced 1,207 t of copper cathode in FY2026, up 17.5% from 1,027 t in FY2025. However, the quarterly profile weakened toward year-end: cathode output rose from 217 t in Q1 to 379 t in Q2, eased to 361 t in Q3 and then fell to 250 t in Q4. Q4 production was therefore about 31% below Q3 and 34% below the Q2 peak.
The Q4 fall should not be attributed to acid alone. Jubilee also reported operational factors including extended maintenance at Roan and pre-stripping work at Molefe. The more defensible conclusion is that acid availability and cost pressure became one of several operating constraints, and one that Jubilee explicitly linked to Sable’s performance during the quarter.
┃ The constraint is uneven across Zambia’s copper producers
The impact of tight sulphuric acid supply is not uniform. Large integrated operations with captive smelting and acid production are less exposed to the merchant market than smaller leach operators and independent processors. This helps explain why national copper production still edged higher while small-scale output fell sharply.
First Quantum’s disclosures illustrate the difference. Kansanshi generated approximately 1.1 million t of sulphuric acid in 2025, almost all of which was consumed on site in leaching circuits for cathode production. Following the smelter expansion, Acid Plant 5 could generate supplementary acid for internal use or external sale, depending on mine geology and processing requirements.
This means Zambia can be a significant acid producer and still have a shortage in the merchant market. Installed acid capacity is not the same as freely available supply. Internal consumption, ore type, smelter availability, contractual allocation, transport economics and local pricing all affect how much acid reaches third-party consumers.
┃ Upstream copper units are growing faster than saleable output
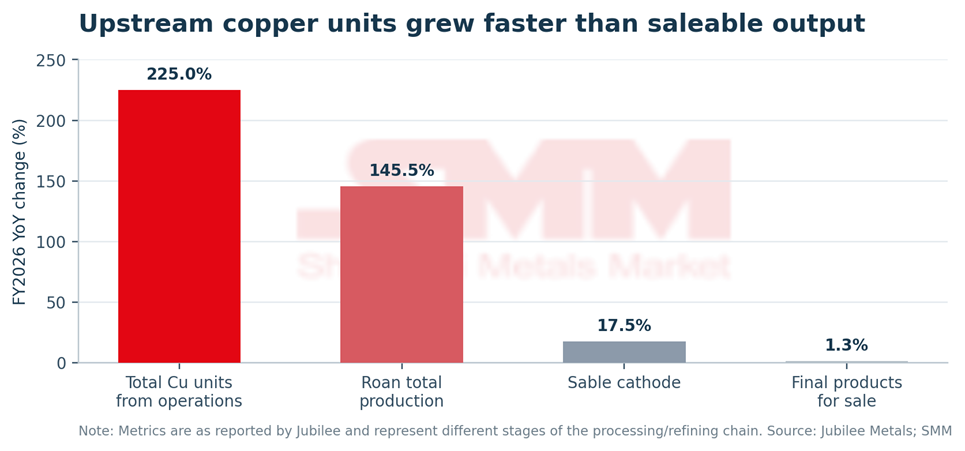
Jubilee’s production mix also shows why copper growth is not only a mining issue. Combined copper units from Roan and Molefe reached 3,739 t in FY2026, up 225.0% year on year. Roan total production increased 145.5% to 2,823 t. Yet final copper products produced for sale increased only 1.3% to 2,120 t, while Sable cathode production rose 17.5%.
Part of this gap reflects the build-up of oxide concentrate fines awaiting processing through Roan’s newly commissioned dewatering circuit and the fact that Jubilee reports different streams at different stages of the value chain. Even so, the contrast highlights the broader issue: converting mined or concentrated copper units into saleable metal depends on refinery availability, reagents, energy and logistics, not only ore supply.
┃ SMM outlook
Through the remainder of 2026, sulphuric acid availability is likely to remain an important variable for Zambia’s oxide and mixed-ore copper producers. The March export-permit system may help retain more acid for domestic users, but it does not create additional supply. In the near term, the market balance will depend on smelter operating rates, internal acid consumption at integrated mines and the amount of surplus product that producers are willing and able to release into the merchant market. For smaller leach operators, delivered availability and price could therefore remain more important than Zambia’s headline installed acid capacity.
There are signs that the supply side could improve. First Quantum has said the Kansanshi smelter expansion and Acid Plant 5 provide the potential to generate supplementary sulphuric acid, depending on mine geology and internal processing requirements. The expanded smelter is configured for around 1.5 million tonnes per year of acid capacity, including Acid Plant 5 at approximately 900 tonnes per day. However, Kansanshi consumed almost all of the roughly 1.1 million tonnes it produced in 2025 on site, which means additional capacity will not automatically translate into an equivalent increase in merchant supply.
The restart of KCM’s Nchanga Smelter in September also introduces a potential source of relief. The 311,000-tonne-per-year smelter returned after a 106-day rehabilitation programme, and KCM identifies sulphuric acid as one of the products manufactured at the Nchanga complex. If the smelter and associated acid systems operate consistently, additional output could improve domestic availability. The extent of that benefit will depend on KCM’s own leach requirements, operating rates and how much acid is ultimately made available to third-party customers.
Demand for acid could rise at the same time. Jubilee expects Sable to receive feed from a growing portfolio of Jubilee-controlled sources as Molefe develops and Project G moves toward targeted development from February 2027. Higher oxide and mixed-feed throughput would increase the importance of reliable reagent supply. Unless merchant acid availability expands alongside this processing growth, the market could remain vulnerable to renewed price spikes or temporary throughput constraints even as Zambia’s mined copper base increases.
Looking ahead to 2027, the acid balance could become an increasingly important differentiator between integrated and merchant-dependent producers. A sustained improvement in smelter uptime, additional third-party acid sales and effective domestic allocation could allow smaller mines and independent processors to recover output and participate more fully in Zambia’s copper-growth cycle. If the market remains tight, however, production growth is more likely to remain concentrated among large integrated operators that can secure acid internally. Key indicators to watch will be merchant acid prices, smelter operating rates, export-permit flows, third-party acid sales and Sable’s ability to convert rising upstream feed into saleable copper products.
Sources: Jubilee Metals Group, FY2026 Production and Operational Update, 14 September 2026; Zambia Ministry of Mines and Minerals Development, H1 2026 mining-sector update; First Quantum Minerals, Q1 2026 results and Zambia operations presentation; Zambia Ministry of Commerce, Trade and Industry, Sulphuric Acid Export Permit notice; Konkola Copper Mines corporate information and ZNBC report on the September 2026 Nchanga Smelter restart; SMM calculations based on public source data.



