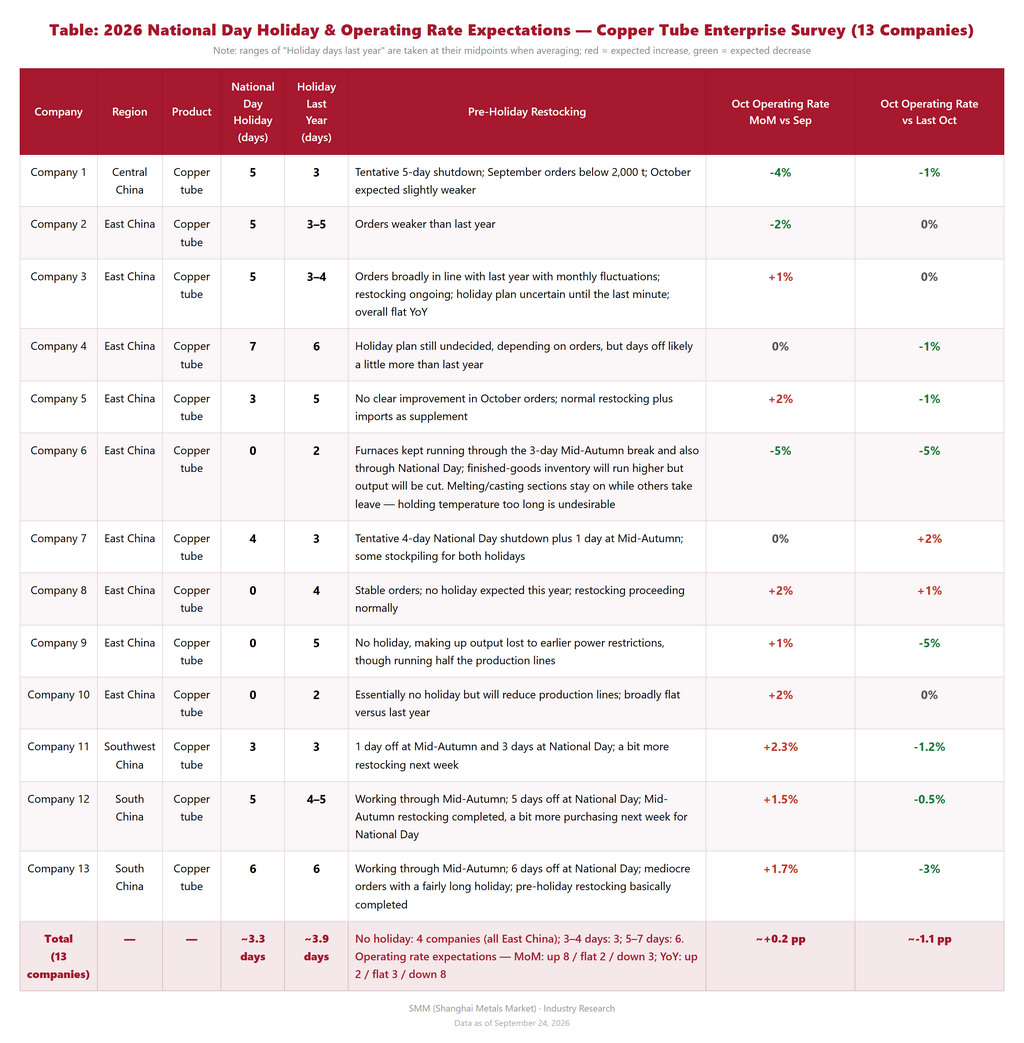
This year, against the backdrop of narrowing declines in air-conditioner production schedules and a return to positive YoY growth in the October schedule, the 13 copper tube enterprises surveyed by SMM have generally tightened holiday arrangements versus last year — 4 East China enterprises will keep running through the National Day holiday, and the sample's average days off is about 3.3 days, roughly 0.6 days shorter than last year. The copper tube industry operating rate is expected to stabilize MoM in October with a markedly narrower YoY decline, but orders have yet to improve substantively, so the quality of this "Silver October" remains to be seen.
1. Days of Holiday
SMM surveyed 13 copper tube enterprises (East China 9, South China 2, Central China 1, Southwest China 1). This year's National Day holiday arrangements are clearly divided: the sample's average days off is about 3.3 days, some 0.5–0.6 days shorter than last year (about 3.9 days, estimated on the midpoint of ranges) — a contrast to last year, when most enterprises added 1–3 days of holiday.
Specifically, 4 East China enterprises (Companies 6, 8, 9 and 10) will take no holiday at all: Company 9 is making up output lost to earlier power restrictions during the break (running half its production lines); Company 8 has stable orders and will maintain normal production; Companies 6 and 10, while not taking holidays, will cut production lines and control output, with melting sections generally kept hot rather than shut down. Three enterprises (Companies 5, 7 and 11) will take 3–4 days off, with Company 5 shortening its break by 2 days versus last year. Six enterprises (Companies 1, 2, 3, 4, 12 and 13) will take 5–7 days off; the two South China mills will take 5 and 6 days respectively, and Company 4 tentatively plans the full 7 days — one day more than last year. Most enterprises noted that final holiday arrangements still depend on order books in the last few trading days before the holiday. During the Mid-Autumn break (September 25–27), most enterprises ran normally or took only 1–3 days off, and some South China mills worked through Mid-Autumn with restocking already completed ahead of time.
2. Pre-Holiday Restocking
Copper prices kept setting record highs ahead of the holiday: LME copper climbed above $14,000/t (touching an intraday high of $14,635/t on September 8), and the SHFE most-active copper contract traded around 108,000 yuan/t; China's copper cathode social inventories fell to a multi-year low of around 90 kt, with copper cathode spot remaining in a premium structure. Record-high raw material prices have markedly raised the capital cost of stocking, and most enterprises reported September orders broadly flat to slightly weaker than last year, so pre-holiday restocking has been cautious and largely need-based: large enterprises replenished raw material inventories through long-term contracts and imported cargoes (e.g. Company 5: "normal restocking plus imports as supplement"); smaller players purchased on demand — Mid-Autumn restocking is basically done, with only small top-ups planned ahead of National Day depending on orders (e.g. Company 12: "Mid-Autumn restocking is completed; we will buy a bit more next week for National Day"). In addition, enterprises hit by earlier power restrictions in parts of East China are rushing orders before the holiday, bringing their raw material restocking forward.
3. Market Status
On operating rates, the copper tube industry averaged 62.87% in August, down 1.22 percentage points MoM and 2.83 percentage points YoY — the declines kept narrowing and trough-like off-season features gradually emerged. The September average operating rate is projected at 63.88%, up 1.01 percentage points MoM but down 3.80 percentage points YoY. Appliance OEMs continue to restrain output and destock, keeping raw material stocking appetite at a low level, but as the decline in air-conditioner production schedules narrows, upstream copper tube procurement is expected to gradually warm up.
On the demand side, according to ChinaIOL's latest production schedule report, total household air-conditioner output scheduled for September is 9.75 million units, down 7.7% YoY: domestic sales are scheduled at 5.39 million units, down 9.4% YoY, with the decline narrowing sharply from August's 24.1% thanks to the low base in the same period of 2025; exports are scheduled at 4.36 million units, down 11.7% YoY amid the seasonal off-peak. October's total household air-conditioner schedule stands at 11.45 million units, returning to positive growth of 0.7% YoY, with domestic sales scheduled up 16.4% YoY and exports up 6.9% YoY — both back in positive territory. On the one hand, overseas distributors have started Black Friday restocking earlier, pulling orders forward into October given shipping lead times; on the other, the base in the same period of 2025 was low. That said, current schedules remain below the 2024 peak, overseas markets still carry some inventory and competitive pressure, and the domestic recovery owes more to a low base than to a genuine reversal in end demand.
4. Outlook
Across the 13 surveyed enterprises: 8 expect their October operating rate to edge up from September (+1 to +2.3 percentage points), 2 expect it flat and 3 expect a decline (-2 to -5 percentage points); the simple average is about +0.2 percentage points MoM, suggesting the industry operating rate is poised to stop falling and stabilize. On a YoY basis, only 2 enterprises expect to be above last year's level, 3 flat and 8 below; the simple average is about -1.1 percentage points — a markedly narrower decline than the industry-wide -3.80 percentage points in September, though the absolute level remains below a year earlier.
Overall, with October air-conditioner schedules back in positive territory and Black Friday restocking orders pulled forward, the direction of marginal improvement in copper tube demand is becoming established, and tighter holiday arrangements indirectly corroborate better order books at some mills. But enterprises widely report no clear improvement in October orders yet (e.g. Company 5: "October orders have not clearly improved"; Company 1: "September orders below 2,000 t, October expected to be a bit worse"), and record-high copper prices are suppressing restocking and new orders. The "Silver October" recovery is thus likely to be mild — closer to a "weak stabilization" than a "strong rebound".