SMM, September 24:
In the metals market:
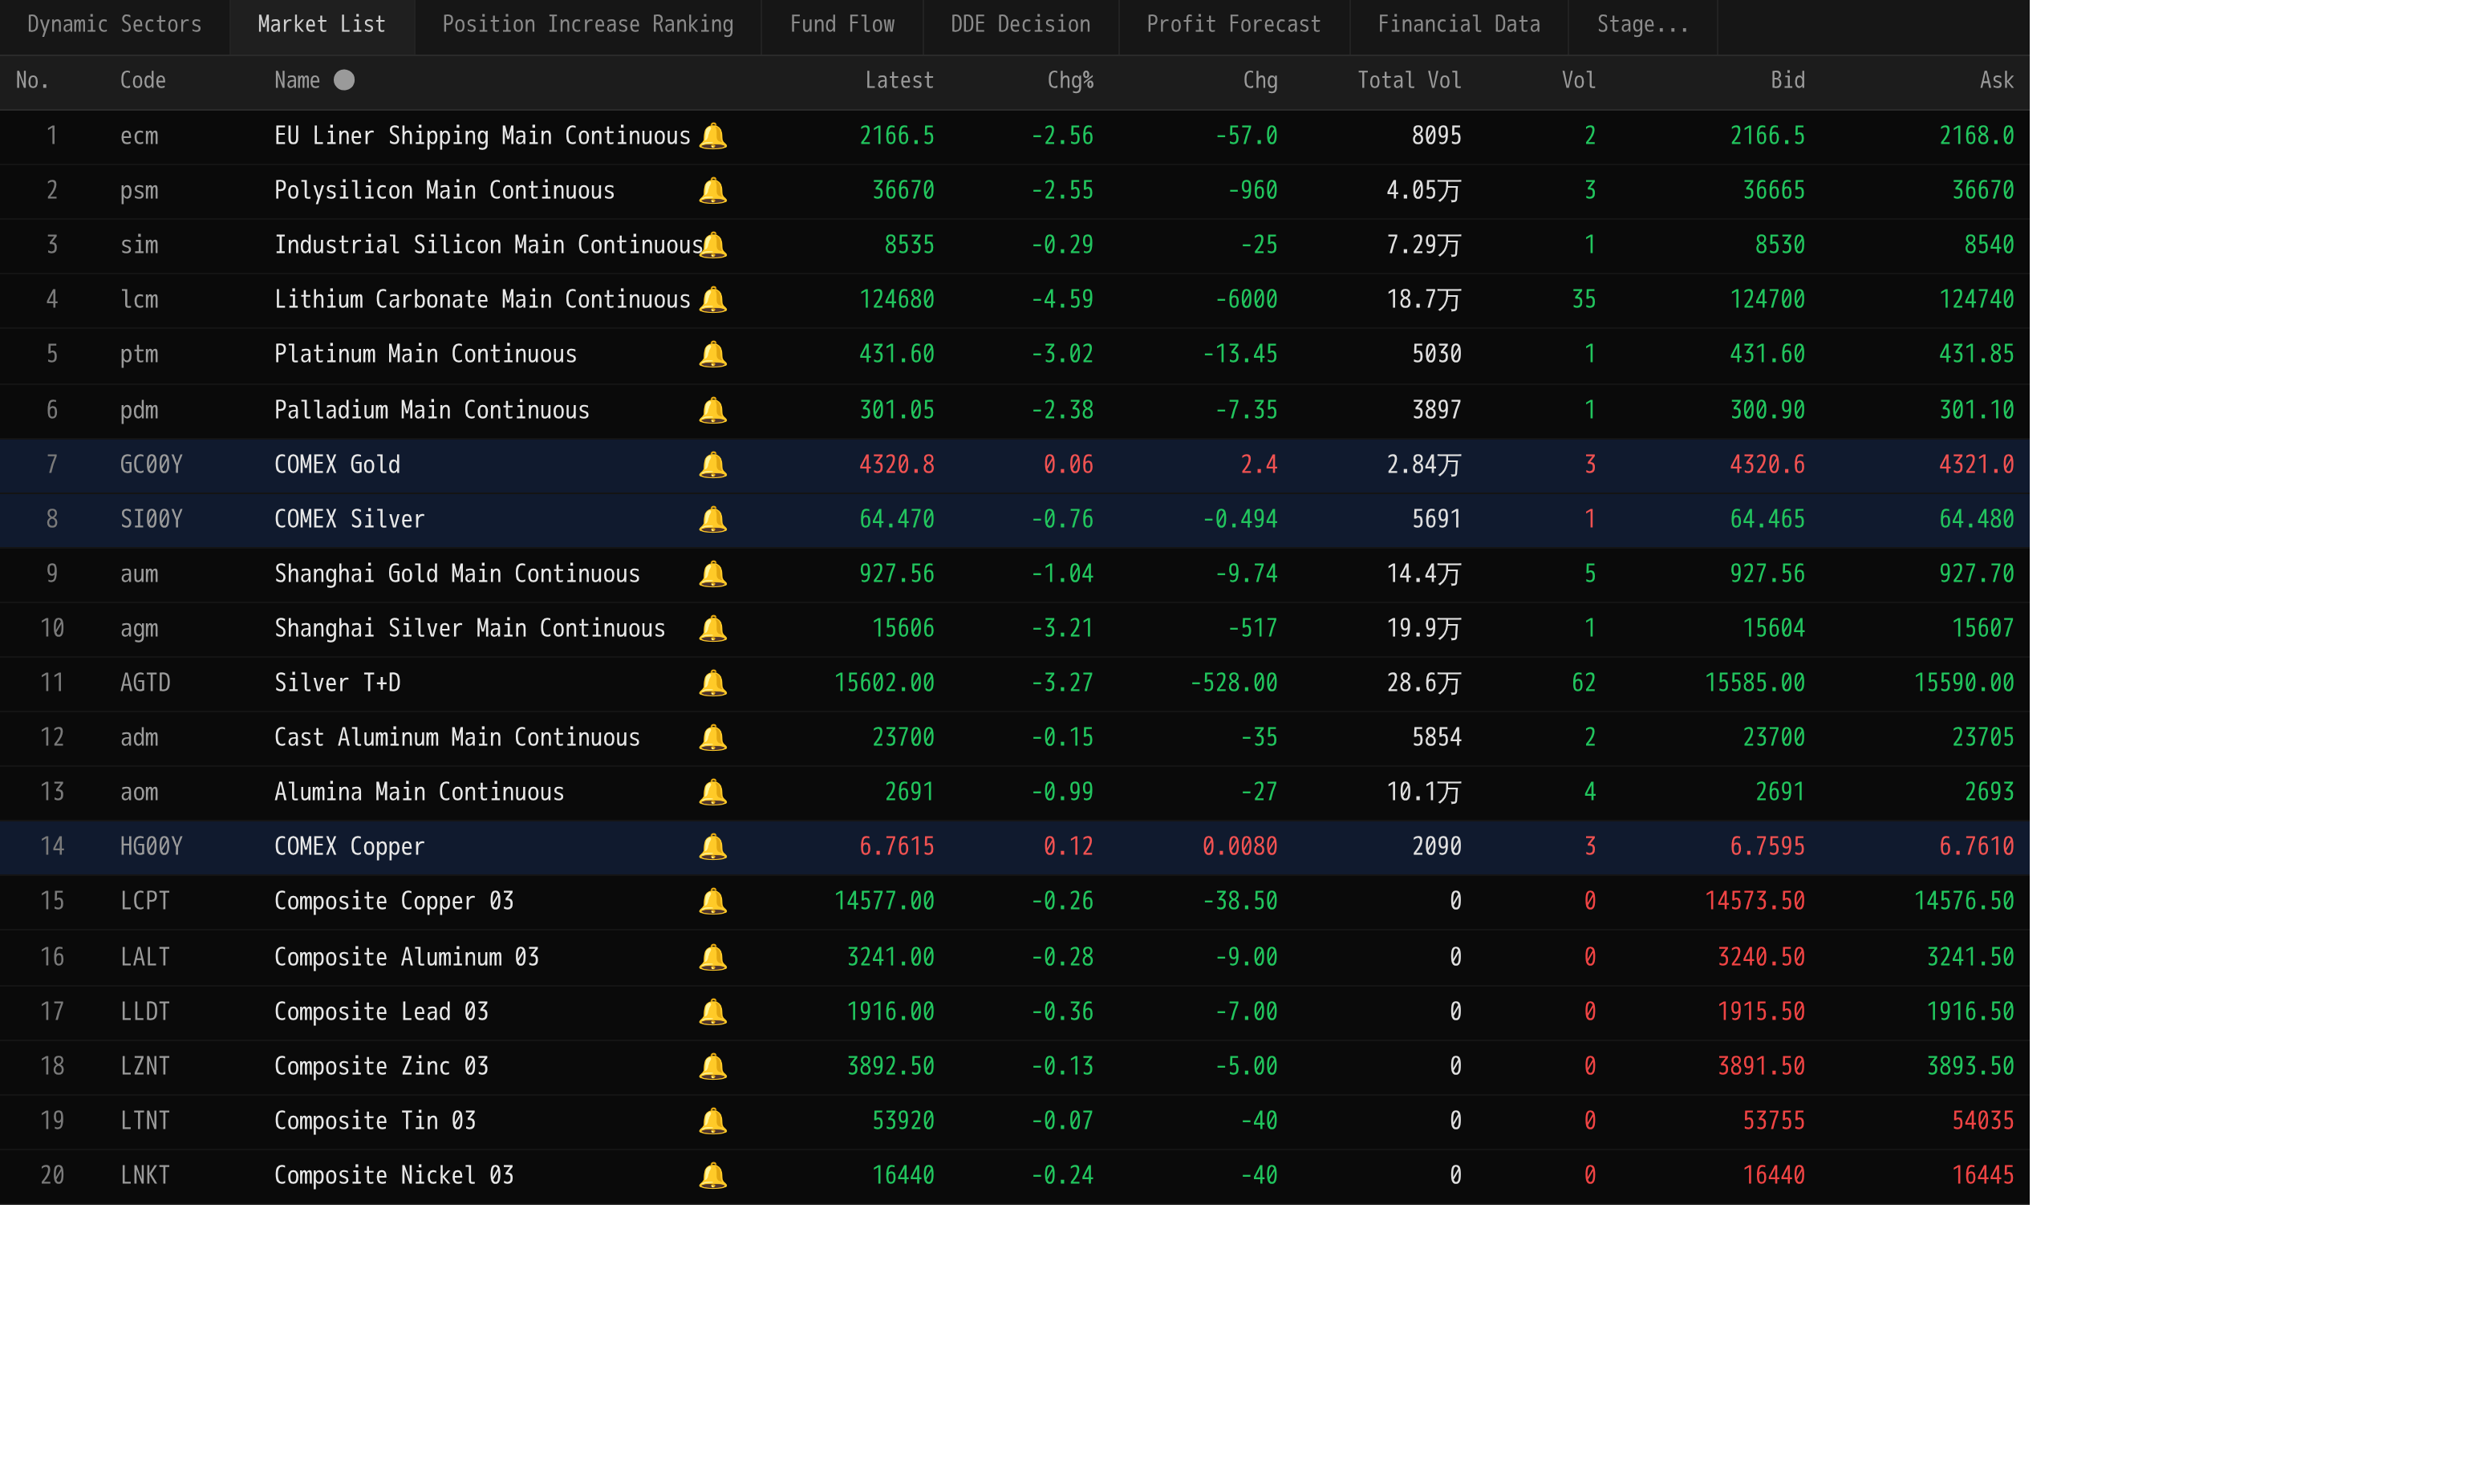
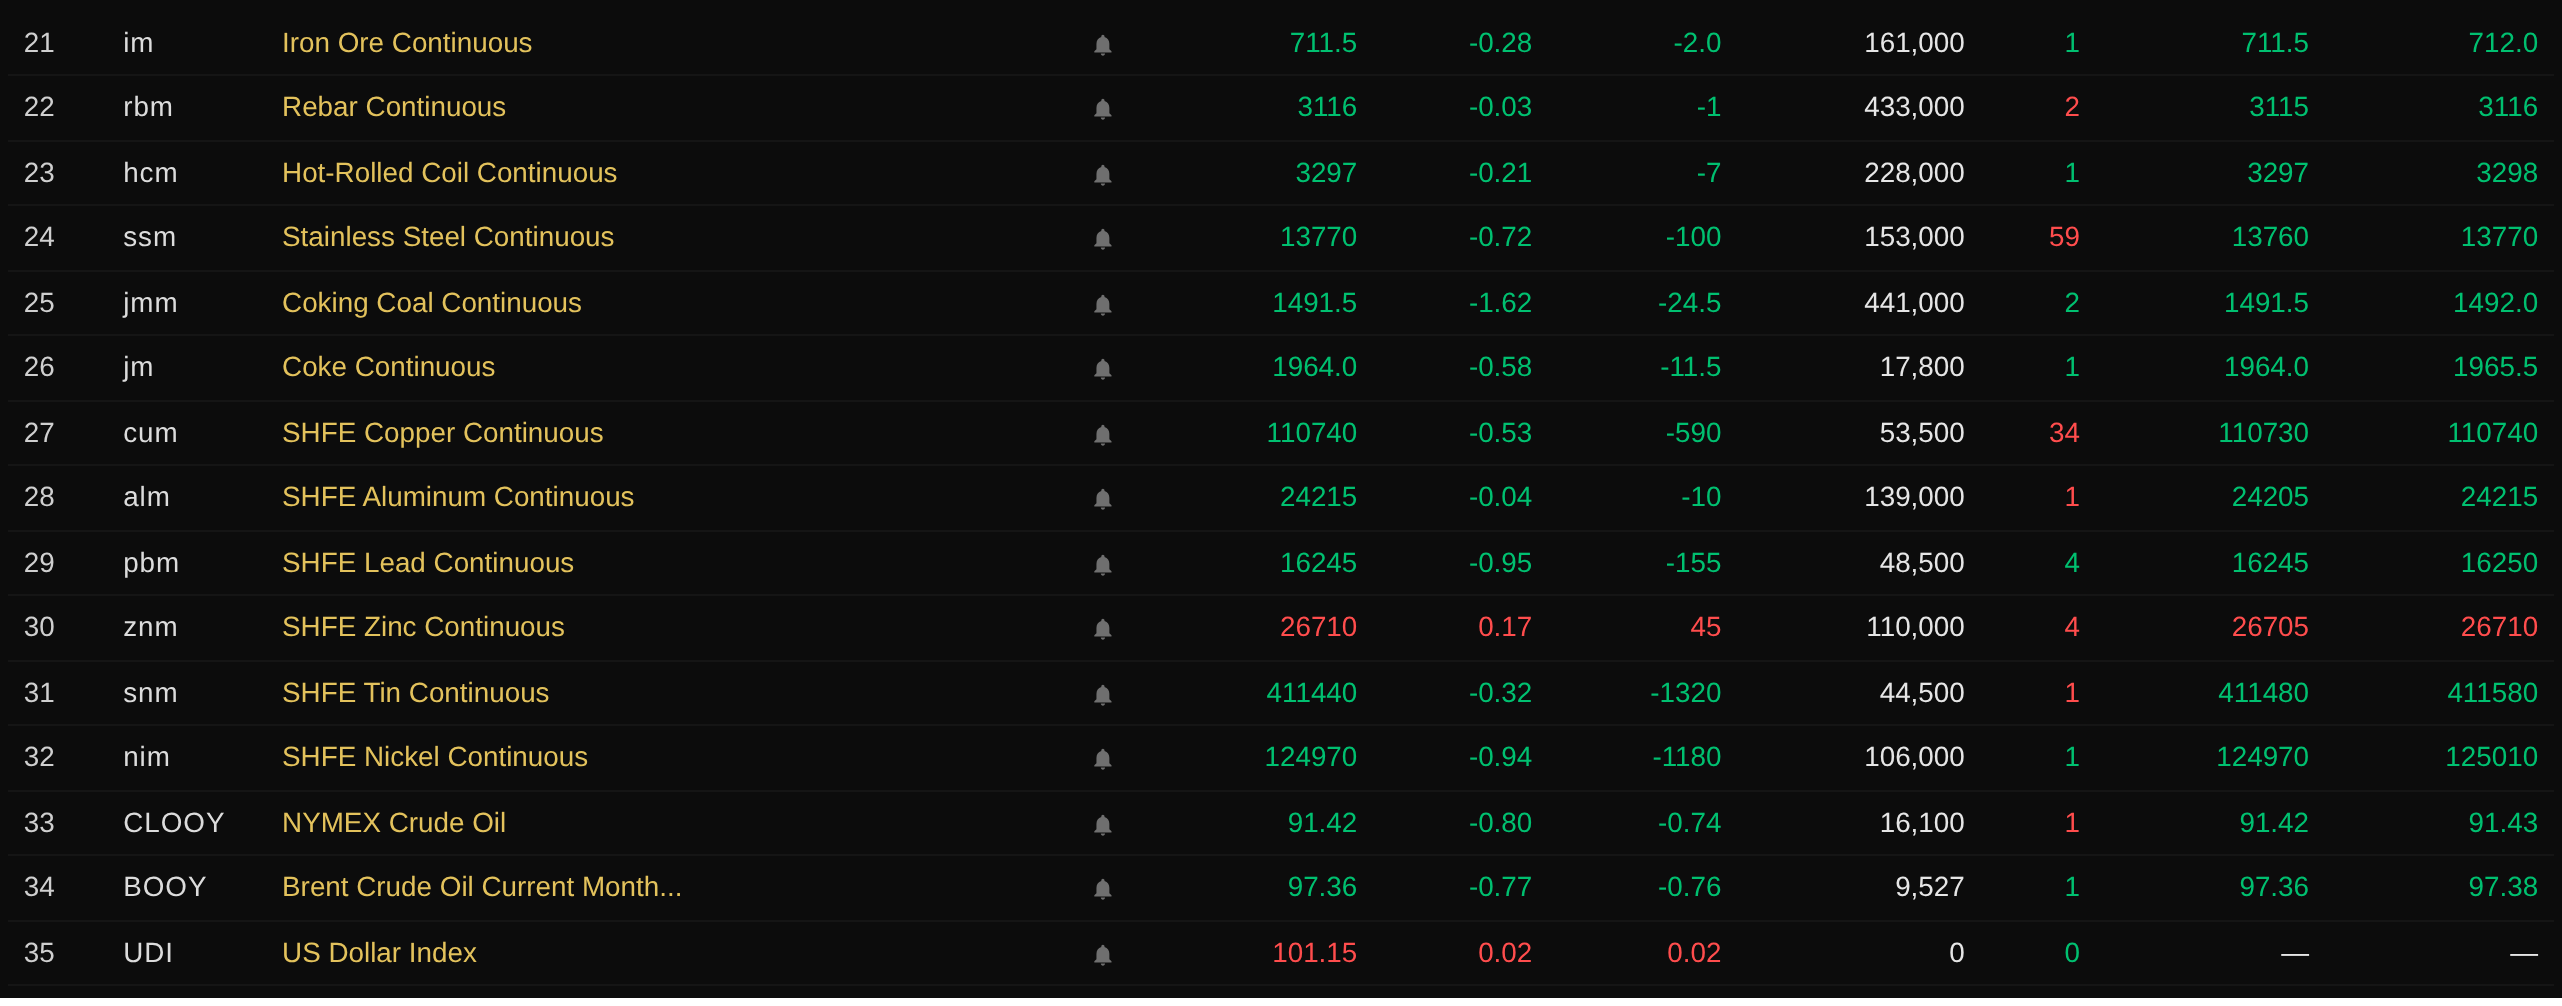
As of the midday close, base metals on the domestic market mostly fell. SHFE copper fell 0.53%. SHFE aluminum fell 0.05%. SHFE lead fell 0.95%. SHFE zinc rose 0.17%. SHFE tin fell 0.32%, and SHFE nickel fell 0.94%.
In addition, the most-traded cast aluminum futures contract fell 0.15%, and the most-traded alumina contract fell 0.99%. The most-traded lithium carbonate contract fell 4.59%. The most-traded silicon metal contract fell 0.29%. The most-traded polysilicon futures contract fell 2.55%.
Ferrous metals all fell. Iron ore fell 0.28%, rebar edged down, and hot-rolled coil fell 0.21%. Stainless steel fell 0.72%. For coking coal and coke: the most-traded coking coal contract fell 1.62%, and the most-traded coke contract fell 0.58%.
In overseas base metals, as of 11:43, LME metals fell across the board. LME copper fell 0.26%, and LME aluminum fell 0.28%. LME lead fell 0.36%, and LME zinc fell 0.13%. LME tin fell 0.07%. LME nickel fell 0.24%.
In precious metals, as of 11:43, COMEX gold edged up 0.06%, and COMEX silver fell 0.76%. In domestic precious metals: SHFE gold fell 1.04%, and the most-traded SHFE silver contract fell 3.21%.
In addition, as of the midday close, the most-traded platinum futures contract fell 3.02%, and the most-traded palladium futures contract fell 2.38%.
As of the midday close, the most-traded container shipping index futures contract fell 2.56% to 2,166.5 points.
As of 11:43 on September 24, some futures midday quotes:
Spot and fundamentals
Silver: US September manufacturing and services PMIs both hit multi-year highs, the probability of an October rate hike rose to 75%, and combined with heightened US-Iran tensions, precious metals fell under pressure. In the spot market, stockpiling for the two holidays briefly boosted trading before weakening. Silver prices fell today, downstream inquiries remained stable, holiday sentiment was strong, and trading was concentrated near parity...
Macro front
Domestic:
[National Energy Administration: As of end-August, China's cumulative installed power generation capacity reached 4.103 billion kW, up 11.1% YoY] On September 24, the National Energy Administration released national power statistics for January-August. As of end-August, China's cumulative installed power generation capacity reached 4.103 billion kW, up 11.1% YoY. Of this, solar power installed capacity was 1.299 billion kW, up 16.3% YoY, and wind power installed capacity was 693 million kW, up 19.6% YoY. From January to August, the average utilization of power generation equipment nationwide was 1,942 hours, down 163 hours YoY. (National Energy Administration)
[Beijing's Mid-Autumn Festival holiday inbound and outbound passenger flow expected to reach 11.18 million]This year's Mid-Autumn Festival holiday runs from September 25 (Friday) to September 27 (Sunday), close to the National Day holiday, creating an extended travel window. Family visit flows during the Mid-Autumn Festival, staggered leave-taking flows, and National Day travel flows will be released in sequence, with higher peaks and longer duration. According to the Beijing Municipal Commission of Transport, the total inbound and outbound passenger flow during this year's Mid-Autumn Festival holiday is expected to reach 11.18 million, with a daily average of 3.726 million. (CCTV News)
[Beijing: Accelerate the building of a globally influential emerging industry hub and future industry leader]On the afternoon of September 23, the Beijing Municipal Bureau of Economy and Information Technology held an expanded Party group meeting. The meeting stressed the need to fully implement Beijing's 15th Five-Year Plan period development plan for high-end and sophisticated industries, expand the growth of emerging industries, cultivate variables in future industries, improve the stock of traditional industries, and accelerate the building of a globally influential emerging industry hub and future industry leader. Efforts should be made to promote the coordinated development of industries in the Beijing-Tianjin-Hebei region, strengthen the sharing of innovation resources and the embedding of industrial resources across the region, advance the "six chains and seven clusters" in depth, accelerate the construction of a number of highly demonstrative cross-regional collaborative projects such as the Beijing-Tianjin-Hebei intelligent connected NEV technology eco-park, and promote the landing and transformation of more achievements in the Beijing-Tianjin-Hebei region. Work mechanisms should be continuously improved, industrial development coordinated, cross-regional industrial linkages deepened, factor guarantees strengthened, and problem-oriented and goal-oriented approaches highlighted to advance the implementation of key tasks in a step-by-step manner. (Beijing Economy and Information Technology)
[Suzhou provident fund new policy supports withdrawal for decoration, with a maximum amount of 150,000 yuan]The Suzhou Housing Provident Fund Management Center issued the Notice on Supporting Withdrawal of Housing Provident Fund for Decoration. It proposes that if depositors and their spouses have no outstanding housing provident fund loan balance nationwide and decorate their self-occupied housing within the administrative area of Suzhou, they may apply to withdraw housing provident fund for the same property under their name. The cumulative withdrawal amount of all withdrawers shall not exceed the VAT invoice amount for housing decoration, and shall not exceed 150,000 yuan. Individual housing provident fund accounts must retain at least one month's contribution based on the latest contribution base (excluding subsidies for new employees). (Suzhou Provident Fund)
[PBOC reverse repo operations achieve a net withdrawal of 110.5 billion yuan on the day; net injection of 19.5 billion yuan this week]The PBOC conducted 51.5 billion yuan of 7-day reverse repo operations today. As 162 billion yuan of 7-day reverse repos matured today, a net withdrawal of 110.5 billion yuan was achieved on the day. This week (9.2-9.24), the PBOC conducted 291.5 billion yuan of 7-day reverse repo operations. As 272 billion yuan of 7-day reverse repos matured this week, a net injection of 19.5 billion yuan was achieved this week. (Jin10 Data APP)
US dollar:
As of 11:43, the US dollar index rose 0.02% to 101.15.
Driven by a surge in new orders, US business activity accelerated to its highest level in more than five years in September; however, strong demand also put pressure on supply chains and pushed up prices. S&P Global said on Wednesday that the flash US composite PMI rose to 58.4 in September, the highest level since July 2021 and up from 56 in August. The rise in the PMI reflected strong growth in both services and manufacturing. S&P Global said the PMI data was consistent with the US economy growing at an annualized rate of about 5%. The agency also noted that backlogs of orders and supply chain delays increased significantly, "indicating insufficient operating capacity and driving further price increases." Chris Williamson, chief business economist at S&P Global Market Intelligence, said: "At the moment, business activity in both manufacturing and services is clearly very strong. However, excluding the impact of the pandemic period, this growth is accompanied by one of the most severe supply chain bottlenecks in nearly 20 years of survey history." Supply constraints mainly stem from the US-Israel war against Iran, which has now entered its seventh month. (Jin10 Data APP)
According to CME "FedWatch": The probability of the Fed keeping rates unchanged at 3.75%-4.00% at the October meeting is 30.3%, and the probability of a 25 basis point hike is 69.7%. The probability of the Fed keeping rates unchanged at 3.75%-4.00% by December is 6.5%, the probability of a cumulative 25 basis point hike is 38.7%, and the probability of a cumulative 50 basis point hike is 54.8%. (Jin10 Data APP)
White House National Economic Council Director Hassett on Wednesday criticized Fed officials who recently supported further rate hikes, saying that with core inflation already close to 2%, continued tightening by the Fed is concerning. Hassett said, "Why raise rates again," and questioned recent remarks by some officials not appointed by Trump supporting more hikes. Hassett said Fed Chairman Warsh is managing a "highly politicized Fed," and restoring Fed independence is an important task he faces. Hassett also criticized the fact that some senior Fed officials continue to remain at the Fed even after leaving their original leadership positions. He named Powell and Barr, arguing that this situation differs from past practice after Fed leadership transitions. Recently, multiple Fed officials have released hawkish signals. Barr said further rate hikes may be needed to bring inflation back to the 2% target; Collins and Musalem also expressed support for further hikes. The Fed's latest economic projections show that 16 officials expect at least one more rate hike this year. (Jin10 Data APP)
Fed Governor Barr said that to ensure inflation falls back to target in a timely manner, the Fed may need to raise rates further. Barr said on Wednesday that he supported the Fed's decision to raise rates by 25 basis points last week, and that risks to achieving the Fed's inflation target have risen. He said: "Inflation remains above our 2% target and has not yet clearly shown a trend of returning to target in a timely manner. In my baseline scenario, further policy adjustments may be needed to ensure inflation falls back to target in a timely manner." Barr said the US economy has experienced a series of shocks over the past year and a half, which have intensified upward price pressures. These include tariffs, the Middle East conflict, disruptions caused by Russia's war against Ukraine, and the recent surge in investment demand to support AI infrastructure construction. (Jin10 Data APP)
Other currencies:
Despite a strong rebound in employment, Australia's unemployment rate unexpectedly rose to a five-year high in August. The mixed employment report did not change market expectations that the Reserve Bank of Australia is about to raise rates, with markets still betting it will hike to curb inflation. Markets currently see a 95% probability that the RBA will raise rates for the fourth time next Tuesday, lifting the rate to 4.6%. Oscar Guth, Australia economist at Oxford Economics, noted that employment growth in August failed to keep pace with the increase in new entrants to the labour market, and labour market tightness has eased somewhat. Nevertheless, inflationary pressure comes not only from the labour market but also from oil prices. Therefore, the RBA is still expected to raise rates next Tuesday. (Jin10 Data APP)
Data:
Today will see the release of US initial jobless claims for the week ending September 19, US Q2 current account, US August new home sales annualized, Australia August seasonally adjusted unemployment rate, Switzerland central bank policy rate as of September 24, Germany September IFO business climate index, UK September CBI retail sales balance, Canada July retail sales m/m, and other data.
In addition, the Swiss National Bank will announce its rate decision. FOMC permanent voter and New York Fed President Williams will hold a fireside chat with former Bank of England Deputy Governor Charlie Bean at the London Macro Policy Forum. 2027 FOMC voter and Richmond Fed President Barkin will participate in a fireside chat at an economics club. 2026 FOMC voter and Cleveland Fed President Hammack will deliver opening remarks at a conference. 2026 FOMC voter and Philadelphia Fed President Paulson will speak at a fintech conference. China's refined oil products will open a new round of price adjustment window (to be determined). President Xi Jinping will pay a state visit to the US from September 23 to 25.
Crude oil:
As of 11:43, oil prices fell in both markets, with WTI down 0.8% and Brent down 0.77%. US crude oil inventories increased last week, and uncertainty over US-Iran negotiations also affected oil price movements.
On September 23 local time, Iranian President Pezeshkian delivered a speech at the general debate of the 81st session of the UN General Assembly. He said Iran is willing to negotiate and cooperate, but will not accept being forced to make concessions through power, sanctions, or military threats, and that peace must be built on the basis of fairness, justice, dignity, and equal rights for all nations. (CCTV News)
Data: US EIA crude oil inventories for the week ending September 18 were 2.969 million barrels, compared with expectations of -641,000 barrels and a previous reading of -640,000 barrels. US EIA gasoline inventories for the week ending September 18 were -1.686 million barrels, compared with expectations of 95,000 barrels and a previous reading of 794,000 barrels.
US Treasury Secretary Bessent discussed inflation and the economic impact of the conflict with Iran in an interview with Fox News. Bessent acknowledged that the Iran conflict triggered an energy supply shock, but predicted that oil prices will fall once supply disruptions ease. Bessent also highlighted the creation of more than 1 million jobs in the US private sector and real wage growth, and expects the economy to continue growing. (Jin10 Data APP)
In addition, after Politico reported that the Trump administration is formulating a 90-day diesel export ban, ultra-low sulfur diesel futures fell about 5% in midday trading, but the White House subsequently denied the report.
White House officials said reports that the Trump administration is considering a diesel export ban are "fake news." Earlier, market reports that the US might impose a 90-day diesel export restriction caused US ultra-low sulfur diesel futures to fall more than 7% at one point, while European diesel futures rose more than 7% on supply concerns. (Jin10 Data APP)
Spot market overview:
►
►
►
►
Midday reviews for other metals spot will be updated later. Please refresh to view~