SMM, September 23:
In the metals market:
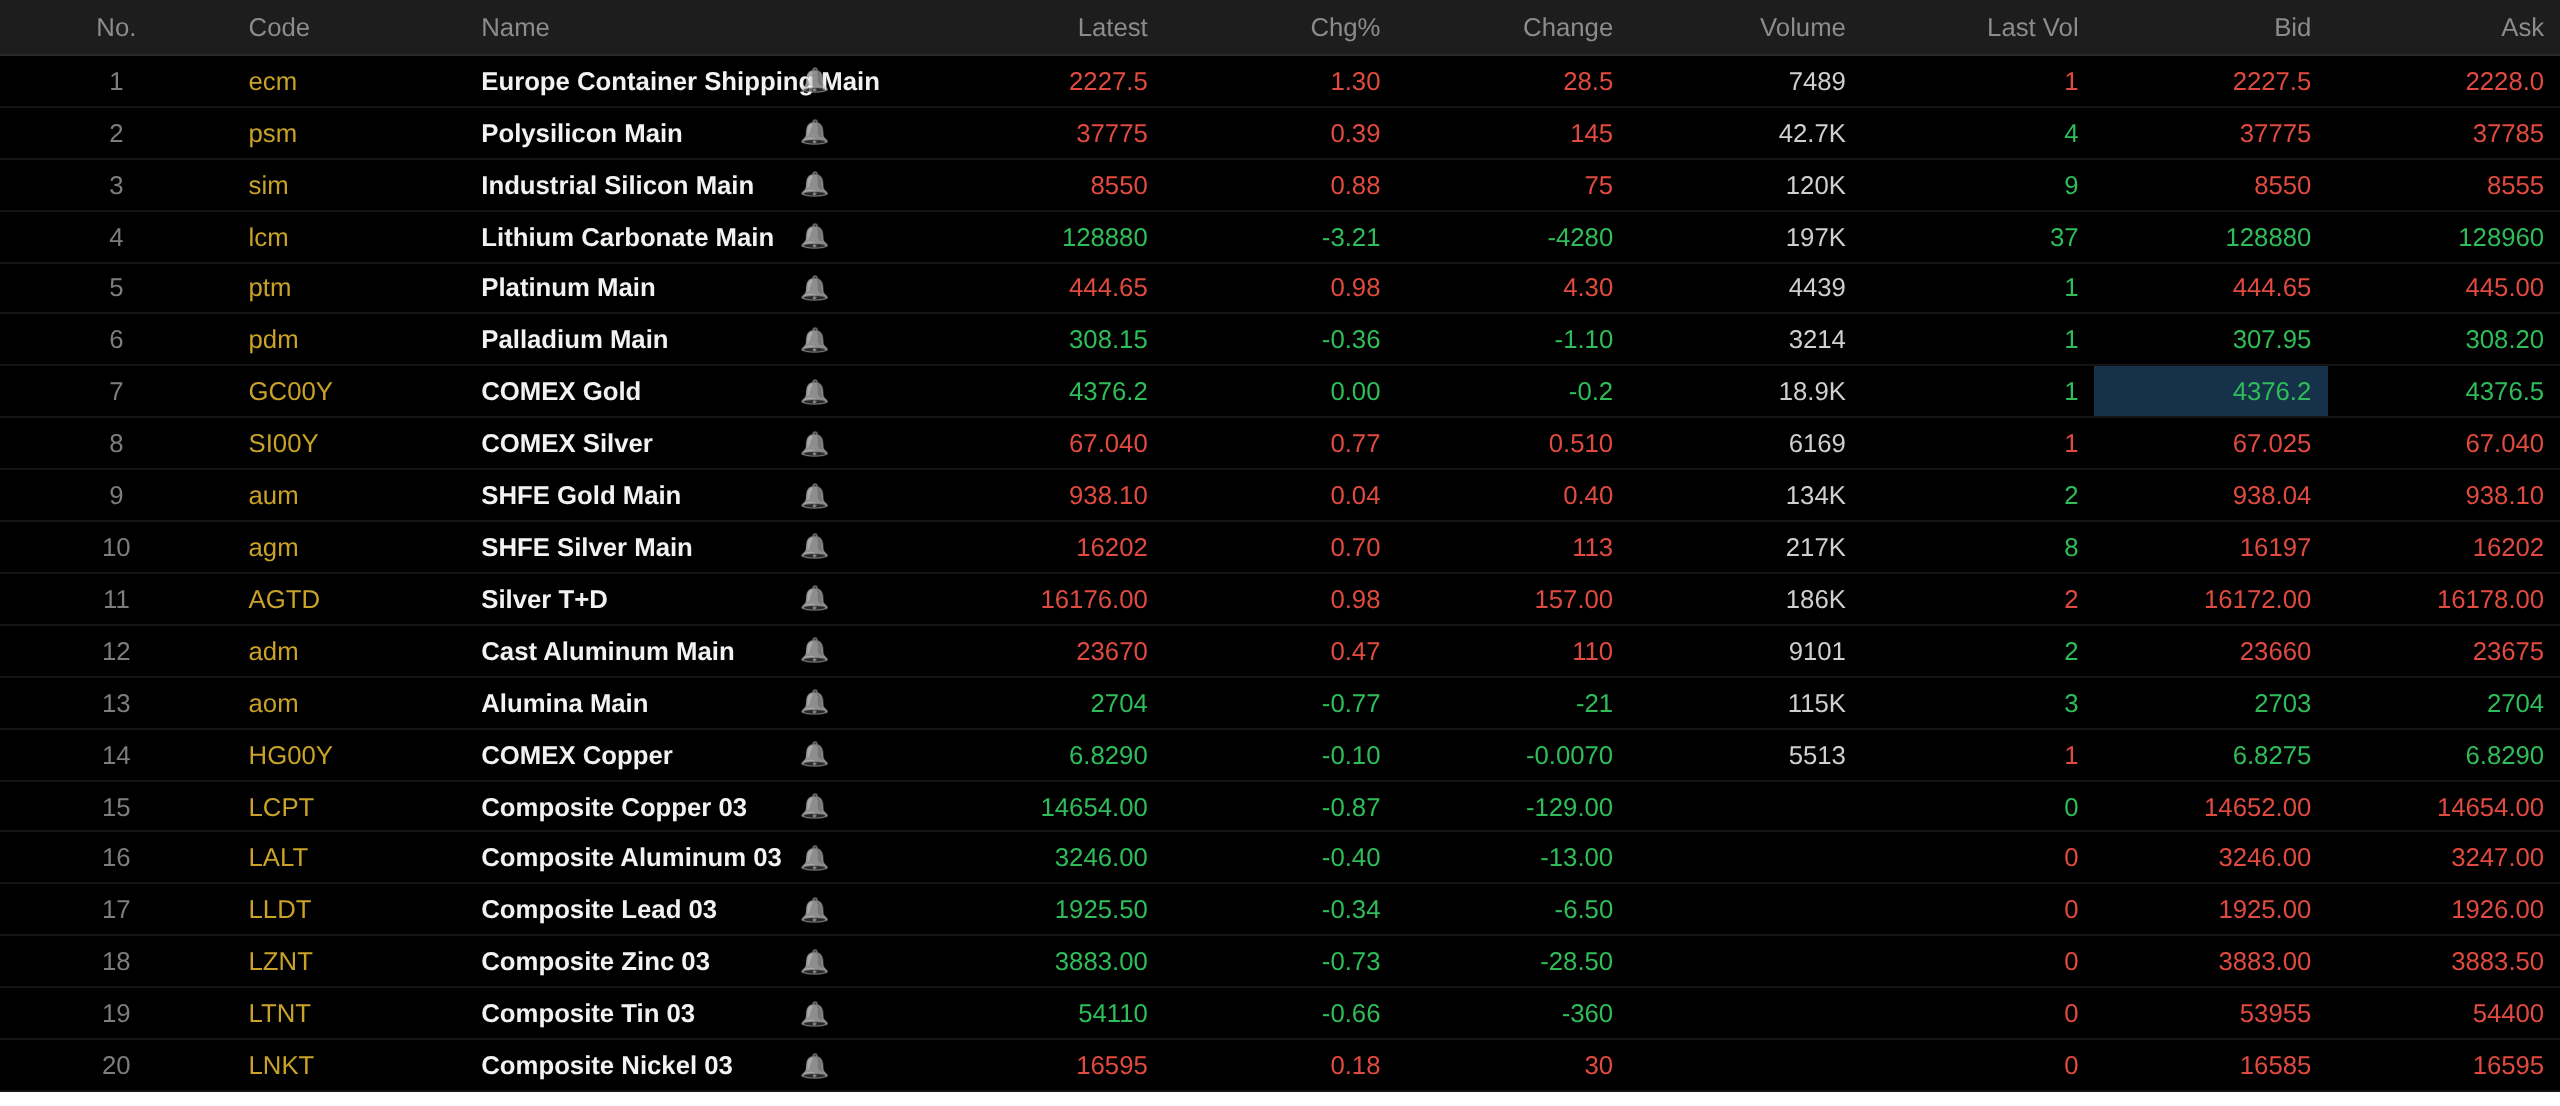
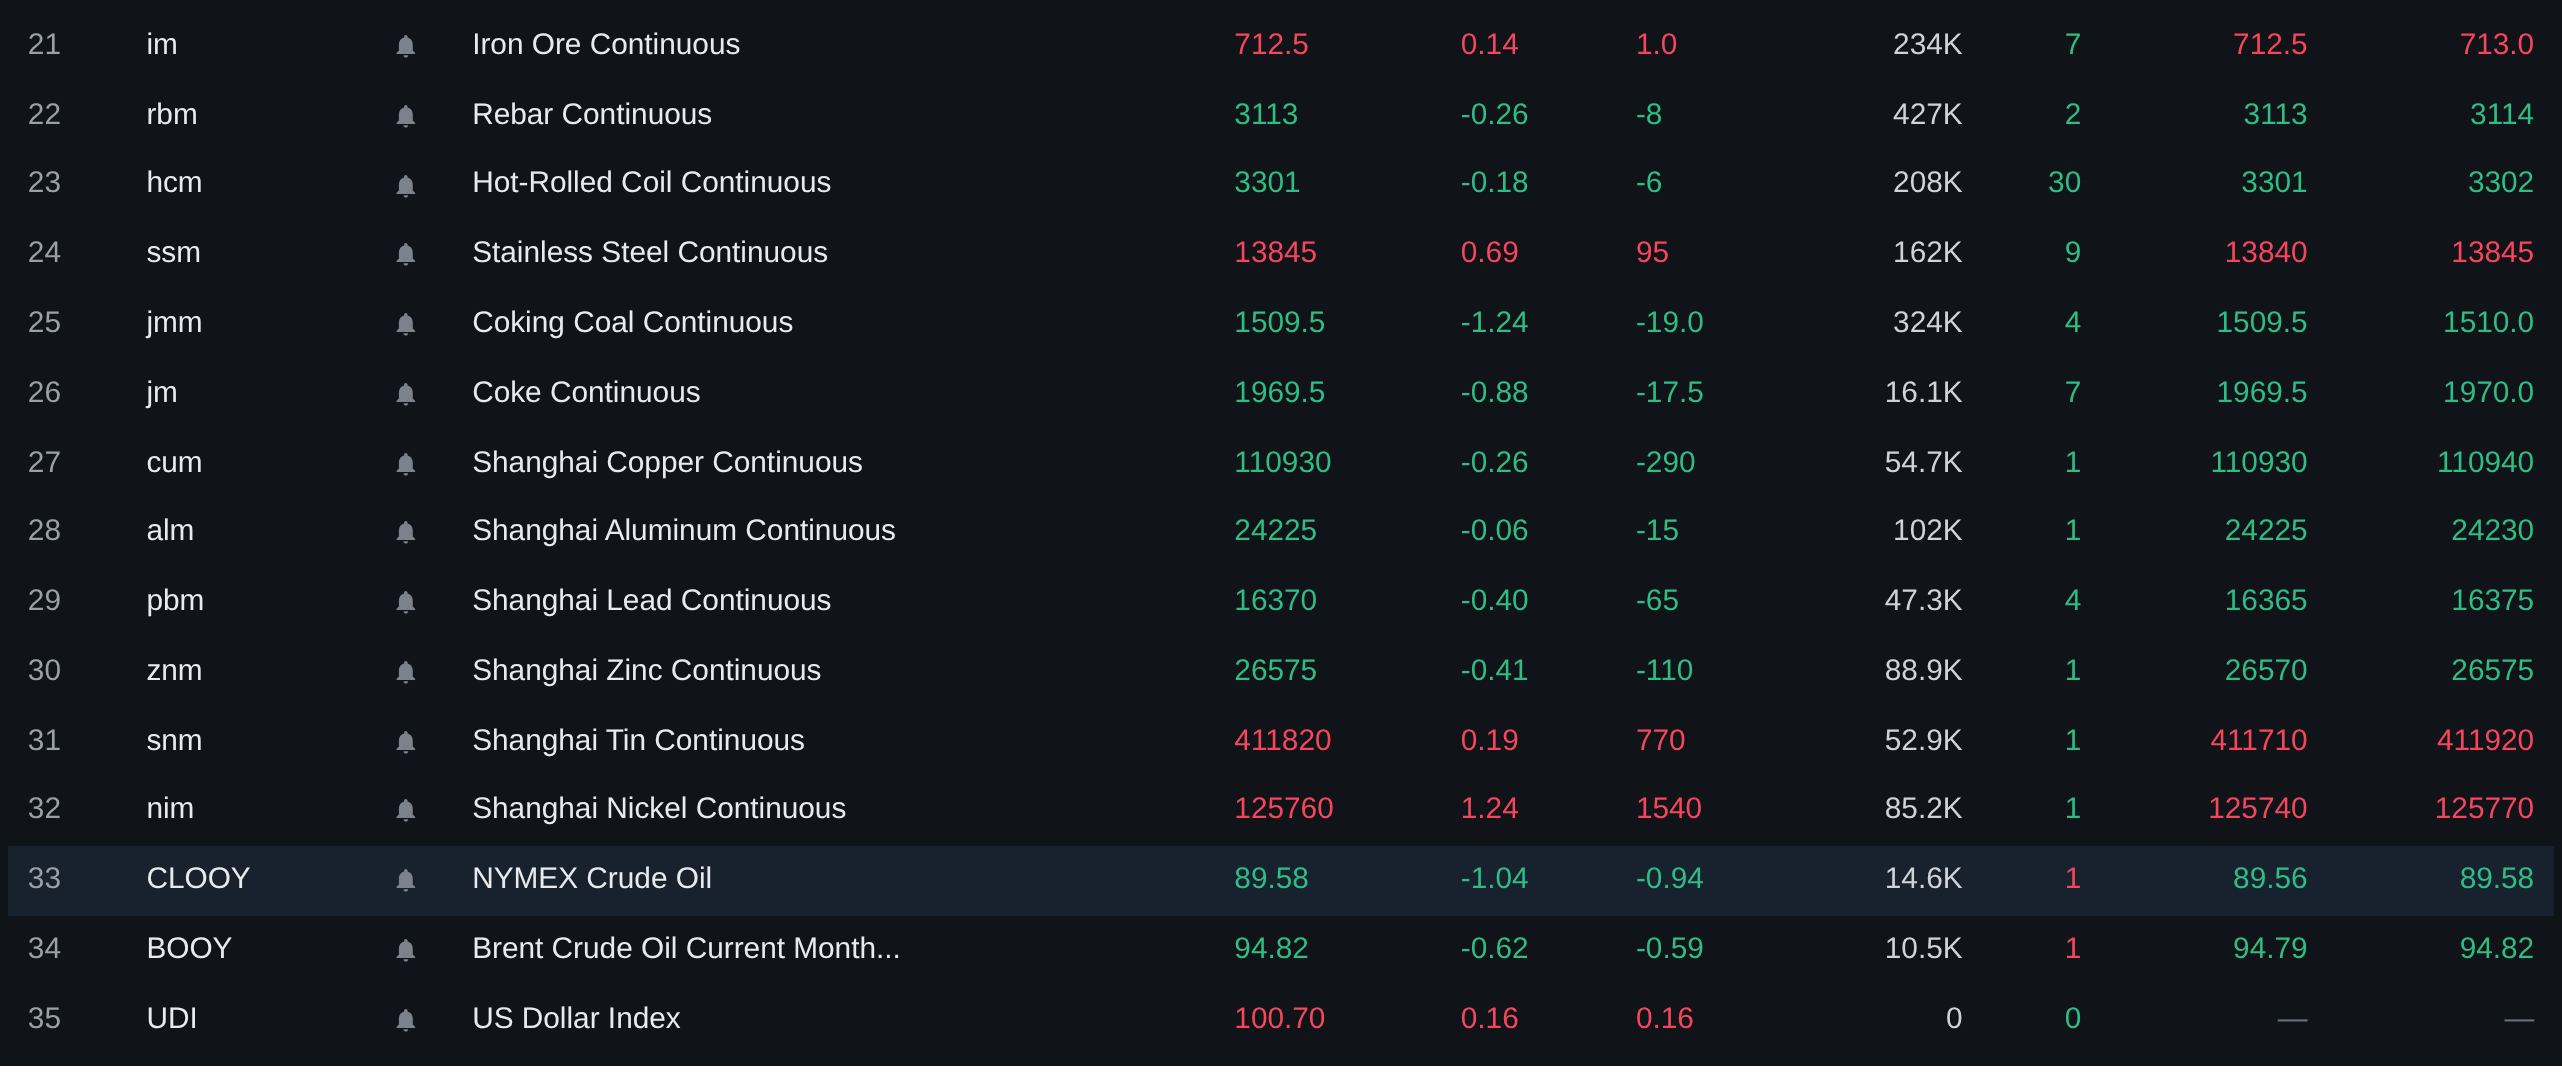
As of the midday close, base metals in the domestic market mostly fell. SHFE copper fell 0.26%. SHFE aluminum edged lower. SHFE lead and SHFE zinc both fell within 0.5%. SHFE tin rose 0.19%, and SHFE nickel rose 1.24%.
In addition, the most-traded cast aluminum futures contract rose 0.47%, while the most-traded alumina contract fell 0.77%. The most-traded lithium carbonate contract fell 3.21%. The most-traded silicon metal contract rose 0.88%. The most-traded polysilicon futures contract rose 0.39%.
Ferrous metals mostly fell. Iron ore rose 0.14%, rebar fell 0.26%, and hot-rolled coil fell 0.18%. Stainless steel rose 0.69%. In coking coal and coke: the most-traded coking coal contract fell 1.24%, and the most-traded coke contract fell 0.88%.
In overseas base metals, as of 11:41, LME metals were nearly all lower. LME copper fell 0.87%, and LME aluminum fell 0.4%. LME lead fell 0.34%, and LME zinc fell 0.73%. LME tin fell 0.66%. LME nickel rose 0.18%.
In precious metals, as of 11:41, COMEX gold was flat at $4,376.2/oz, and COMEX silver rose 0.77%. In domestic precious metals: SHFE gold rose 0.04%, and the most-traded SHFE silver contract rose 0.7%.
In addition, as of the midday close, the most-traded platinum futures contract rose 0.98%, and the most-traded palladium futures contract fell 0.36%.
As of the midday close, the most-traded European shipping route containerized freight index futures contract rose 1.3% to 2,227.5 points.
As of 11:41 on September 23, some futures midday quotes:
Spot and Fundamentals
Copper: Today, spot Guangdong #1 copper cathode against the front-month contract: high-quality copper was quoted at a premium of 1,400 yuan/mt, up 100 yuan/mt from the previous trading day; standard-quality copper was quoted at a premium of 1,100 yuan/mt, up 100 yuan/mt from the previous trading day; SX-EW copper was quoted at a premium of 1,040 yuan/mt, up 100 yuan/mt from the previous trading day. The average price of Guangdong #1 copper cathode was 112,615 yuan/mt, up 380 yuan/mt from the previous trading day, and the average price of SX-EW copper was 112,405 yuan/mt, up 380 yuan/mt from the previous trading day. Spot market: Guangdong inventory continued to decline today, falling for a second consecutive day, mainly due to reduced arrivals and increased warehouse withdrawals, with stockpiling picking up ahead of the Mid-Autumn Festival...
Macro Front
Domestic:
[National Energy Administration: As of end-August 2026, China's EV charging infrastructure (guns) totaled 24.223 million units] On September 23, the National Energy Administration released national EV charging facility data for August 2026. According to data from the national charging facility monitoring service platform, as of end-August 2026, the total number of EV charging infrastructure units (guns) in China reached 24.223 million, up 39.6% YoY. Of this, public charging facilities (guns) totaled 5.16 million, up 19.5% YoY, with total rated power reaching 262 million kW and average power per gun of approximately 50.69 kW; private charging facilities (guns) totaled 19.063 million, up 46.3% YoY, with reported installed electricity capacity for private charging facilities reaching 163 million kVA. (Jin10 Data APP)
[SGE: Notice on Market Risk Control During the 2026 Mid-Autumn Festival and National Day Holidays]The SGE issued a notice on market risk control during the 2026 Mid-Autumn Festival and National Day holidays: During the Mid-Autumn Festival, the exchange's deferred contracts will maintain existing margin ratios and price limits unchanged; starting from the close and settlement on September 28, 2026 (Monday), the margin ratios for Au (T+D), mAu (T+D), Au (T+N1), Au (T+N2), NYAuTN06, NYAuTN12 and other contracts will be adjusted from 15% to 18%, and from the next trading day, the price limit will be adjusted from 14% to 17%; the margin ratio for the Ag (T+D) contract will be adjusted from 21% to 24%, and from the next trading day, the price limit will be adjusted from 20% to 23%. (Shanghai Gold Exchange)
[PBOC Reverse Repo Operations Achieve Net Withdrawal of 102 Billion Yuan on the Day]The PBOC conducted 8 billion yuan of 7-day reverse repo operations today. With 110 billion yuan of 7-day reverse repos maturing today, the day saw a net withdrawal of 102 billion yuan. (Jin10 Data APP)
US dollar:
As of 11:41, the US dollar index rose 0.16% to 100.7. According to the CME "FedWatch": The probability of the US Fed keeping rates unchanged at 3.75%-4.00% at its October meeting is 45.8%, while the probability of a 25 bp hike is 54.2%. The probability of the Fed keeping rates unchanged at 3.75%-4.00% through December is 10.8%, the probability of a cumulative 25 bp hike is 47.8%, and the probability of a cumulative 50 bp hike is 41.4%. (Jin10 Data APP)
Shenwan Hongyuan Research recently released a research report stating that the US dollar index is positively correlated with oil prices in the short term. During supply shock phases, safe-haven demand and relative fundamental advantages often cause the US dollar to strengthen alongside oil prices; if the US-Iran conflict expands, the US dollar index will still face upward pressure, and after de-escalation, the core fluctuation range may return to 97-103. A trend-based strengthening of the US dollar index typically occurs during a phase of sustained rate hikes by the US Fed. The September hike has already landed, but if future hikes are merely sporadic rather than part of a trend-based tightening cycle, the risk of a trend appreciation in the US dollar remains relatively manageable. Looking ahead to H2, the core fluctuation range for the 10-year US Treasury yield is likely to be between 4.5% and 5%, with the linkage between inflation expectations and oil prices being the most critical variable for short-term rates; in an optimistic scenario, it could pull back to 4.3%, while in a pessimistic scenario, it could break above 5%. Over the medium term, the term premium on US Treasuries is prone to rise but difficult to fall, and the risks in US Treasuries have escalated from cyclical fluctuations to a "gray rhino" comprising concerns over US fiscal sustainability, the US Fed's triple dilemma of "sticky inflation, weak employment, and automatic tightening of long-term bonds," and imbalances in the global savings cycle. Current US equity valuations are not low, and the stronger and longer-lasting the shock, the greater the damage to stock prices.
Fed's Williams on Tuesday defended the system through which the US Fed implements monetary policy, while also stating that the system can be adjusted and optimized as financial markets evolve. Williams said that using the current set of tools to manage short-term rates and provide "ample" reserves to the financial system "has proven to be very effective in achieving interest rate control and supporting the smooth functioning of core financial markets." Williams' remarks that day did not touch on monetary policy or the rate outlook, and he was not scheduled to take questions after his speech. The New York Fed president said that although the Fed's rate control framework works well, it is not set in stone and can be adjusted in response to changes in the market environment. Williams said, "As markets continue to evolve, we must ensure that our policy tools can meet their objectives to fulfill their necessary functions. Simply put, the evolution of financial market structure will also drive the evolution of how we effectively implement monetary policy." (Jin10 Data APP)
Fed's Barkin warned that inflation shocks may take some time to ease and that there is a risk of inflation pressures staying high and becoming entrenched. Barkin said the Fed's rate hike last week helped slow inflation, but he did not explicitly say whether further policy tightening is needed. Instead, the Fed official stressed that supply shocks are no longer merely sporadic or temporary phenomena, but rather persistent price pressures affecting the entire economy. "These conditions may fade over time, but I expect it will still take some time," Barkin said. "During this period, the current high level of inflation could have an impact on future inflation." Barkin noted, "What do we do next? We are committed to sustainably bringing inflation down to our 2% target."Last week's rate hike will help with this. Whether further hikes are needed, and how many? We'll wait and see." The US Fed official also laid out two inflation scenarios: the first is that recent shocks gradually fade and price pressures cool rapidly; the second is that inflationary pressures persist. "I'm open to the possibility that inflation could pull back soon. Some of the recent shocks may reverse," Barkin said, adding that consumers may "hit their limits," investment growth may slow down, and employment may also "fluctuate." "On the other hand, inflation could prove harder to tame than expected. Temporary shocks could persist," he said. "New cost pressures could emerge. Stronger demand could feed through to prices, and the impact of today's inflation could do the same." (Jinshi Data APP)
Data-wise:
Today will see the release of the US S&P Global Manufacturing PMI flash for September, the US S&P Global Services PMI flash for September, France's Manufacturing PMI flash for September, Germany's Manufacturing PMI flash for September, the Eurozone Manufacturing PMI flash for September, the UK Manufacturing PMI flash for September, the UK Services PMI flash for September, and other data.
In addition, attention should be paid to: President Xi Jinping's state visit to the US from September 23 to 25. 2027 FOMC voting member and Richmond Fed President Barkin is scheduled to speak, and Fed Governor Barr will speak on the theme of "housing." In France, the OECD will release its interim Global Economic Outlook report. Vice Premier He Lifeng will lead a delegation to the US from September 19 to 23 for economic and trade consultations, and Iranian President Pezeshkian will address the UN General Assembly. Due to contract rollover, the NYMEX WTI crude oil October futures contract will complete its final floor trading at 2:30 on September 23 and final electronic trading at 5:00 a.m. Please note the expiration and rollover announcements from trading venues to manage risk. In addition, some trading platforms' US oil contract expiration times are typically one day earlier than the official NYMEX schedule, so please pay extra attention.
Crude oil:
As of 11:41, oil prices on both sides of the Atlantic extended their declines from the previous five trading sessions, with WTI down 1.04% and Brent down 0.62%.
According to Iran's Fars News Agency, Iranian sources said that reports from Reuters and Kyodo News about the opening of the Strait of Hormuz are unreliable and untrue. Earlier, positive news about Iran-US negotiations and the possible reopening of the Strait of Hormuz emerged simultaneously, once again affecting the oil market and pushing oil prices lower. (Jinshi Data APP)
According to three people familiar with the matter, Saudi Arabia has restarted operations of its east-west oil pipeline and may resume oil exports from the Red Sea port of Yanbu later on Tuesday. Two of the sources said the pipeline is currently transporting at a low volume. (Jin10 Data APP)
Preliminary shipping data showed three commodity vessels passed through the Strait of Hormuz on Tuesday, down from four a day earlier and below the 10-day moving average of about 15. According to data from shipping tracker Kpler, the three vessels, including a Panamax tanker, were all exiting the strait. However, according to the data, an empty LNG tanker Al Mafyar reappeared inside the strait on Tuesday after it was last seen outside the waterway on September 19. Meanwhile, 22 commodity vessels passed through the Bab el-Mandeb Strait on Tuesday. The data showed 14 of them were heading toward the Red Sea and eight toward the Gulf of Aden. They included five Panamax tankers, six Supramax vessels, four Aframax tankers, one Suezmax tanker and one very large crude carrier. The figure was down from the 10-day average of 26 vessels. (Jin10 Data APP)