[SMM Analysis] Steel Billet Drives Growth, ASEAN and Africa Absorb Supply, Middle East Weakens
According to data from the General Administration of Customs, China's cumulative exports of steel products and steel billets from January to August 2026 totaled approximately 89.21 million mt, up about 2.85% from 86.74 million mt in the same period of 2025. The 17 categories combined reached approximately 89.22 million mt (+2.9%), but the +4.81 million mt increase in steel billets was nearly double the net growth (+2.48 million mt). Excluding steel billets, finished steel products still posted approximately -3.0%, confirming that the "steel billet as the main growth driver" pattern remains unchanged.
- By product:
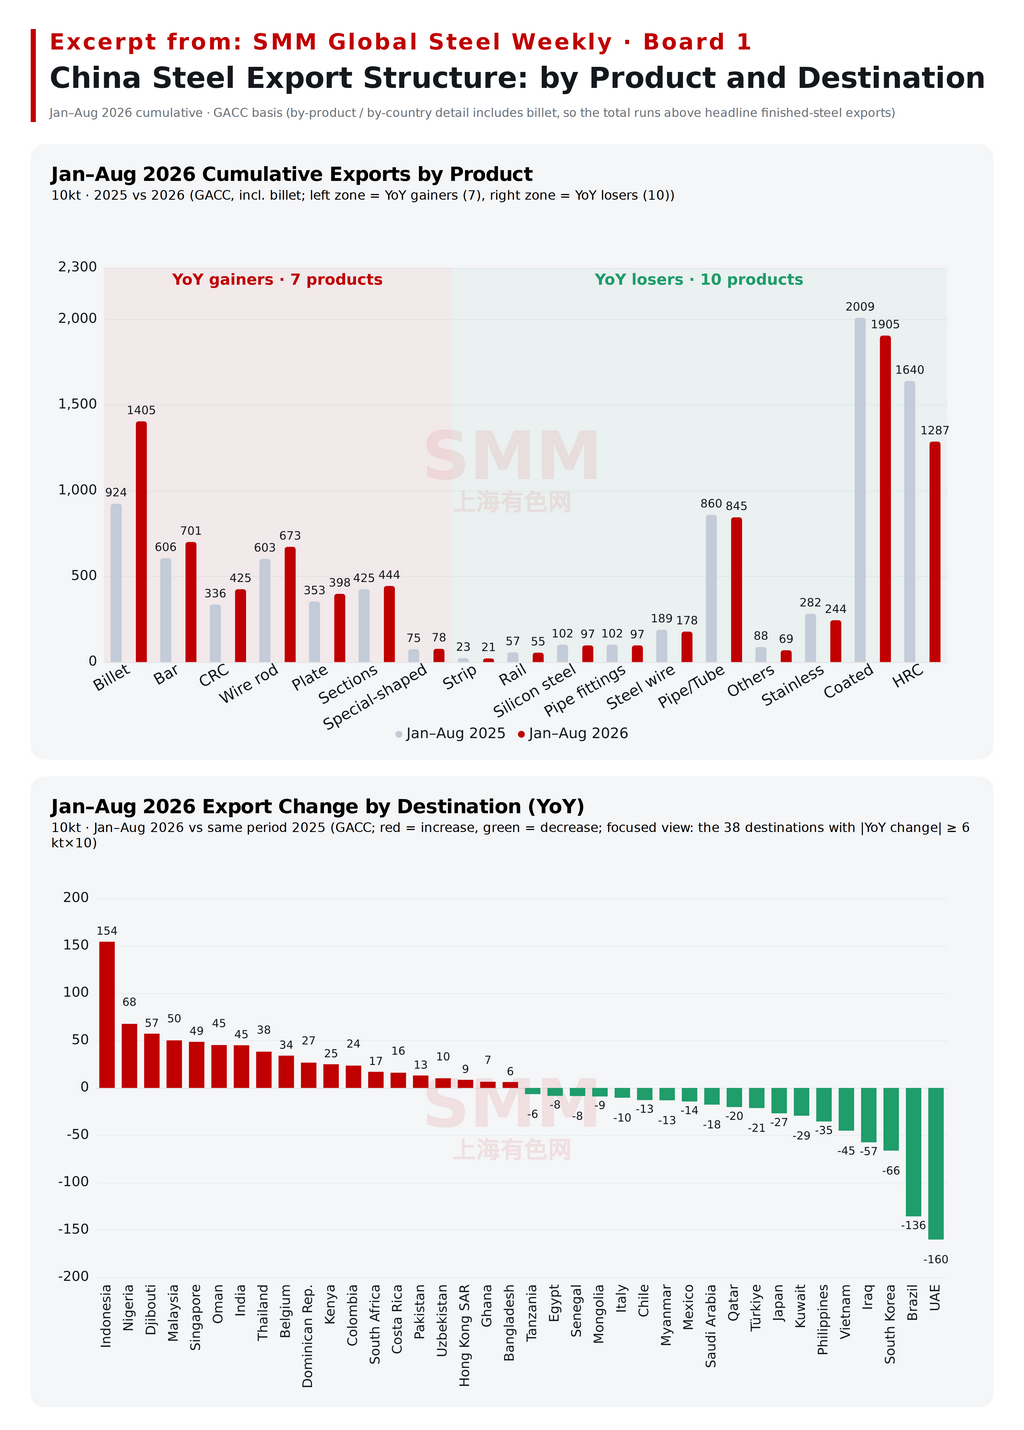
Steel billet (+4.81 million mt/+52.1%): August single-month volume was approximately 1.93 million mt, pulling back MoM. The earlier judgment that "the high base creates expectations for a pullback" is now materializing (Southeast Asia destocking + narrowing price spreads), but supply disruption substitution is providing a floor, and overall performance has not lost momentum.
Hot-rolled coil (-3.53 million mt/-21.5%): The decline narrowed compared with January-July. August single-month volume of approximately 1.99 million mt turned positive YoY (the August base last year was only about 1.76 million mt), suggesting that the most severe phase of anti-dumping impact may have passed.
Cold-rolled coil (+890,000 mt/+26.5%) posted the fastest growth: product shifting after hot-rolled restrictions + ASEAN manufacturing demand. The three long steel products combined increased by 1.84 million mt at a steady pace.
Coated steel (-1.04 million mt): August volume of 2.31 million mt was down 2.6% MoM, weighed down by the concentrated implementation of new trade barriers from South Korea (provisional galvanizing duties of 22.34%-33.67%) and Turkey (final rulings of 22.37%-32.40%), with overall performance remaining weak.
Data Source: SMM, General Administration of Customs
- By country:
Indonesia (+1.54 million mt): Its position as the top destination for steel billets remains solid. The core logic of Chinese semi-finished products filling the ASEAN supply gap after Iran's supply disruption remains unchanged. This is further supported by infrastructure ramp-up including the new capital Nusantara, and the stable channel formed by Chinese-invested rolling mills' "import billet → local rolling" model, with August single-month volume increasing by another 140,000 mt. It is also particularly noteworthy that Indonesia's dry season peaked in August 2026. According to BMKG, the number of Seasonal Zones (ZOM) at peak dry conditions was 83 in July (approximately 12.26% of the country's land area), surged to 369 in August (48.84%), and pulled back to 169 in September (25.41%), with relief only arriving after the rainy season begins in mid-October. Java, Bali, Sulawesi, and other regions were all in peak dry zones in August, and Cilegon (West Java), one of Indonesia's major steel billet production sites, was among the areas most severely affected by drought. As a result, the absence of local supply combined with the increased attractiveness of low-priced Chinese resources jointly drove the upward shift in incremental volumes.
Nigeria (+680,000 mt) + Africa sector: infrastructure boost, entrepot hub. Nigeria is the largest growth market in Africa this period, with urbanization and local undersupply driving imports; Djibouti continues to function as an East African entrepot hub, absorbing demand from hinterlands such as Ethiopia and Somalia, with port and infrastructure projects continuing to expand. However, divergence within Africa is evident, with Tanzania, Senegal, and others contracting simultaneously, highlighting significant differences in regional demand and payment capacity.
Copyright and Intellectual Property Statement:
This report is independently created or compiled by SMM Information & Technology Co., Ltd. (hereinafter referred to as "SMM"), and SMM legally enjoys complete copyright and related intellectual property rights.
The copyright, trademark rights, domain name rights, commercial data information property rights, and other related intellectual property rights of all content contained in this report (including but not limited to information, articles, data, charts, pictures, audio, video, logos, advertisements, trademarks, trade names, domain names, layout designs, etc.) are owned or held by SMM or its related right holders.
The above rights are strictly protected by relevant laws and regulations of the People's Republic of China, such as the Copyright Law of the People's Republic of China, the Trademark Law of the People's Republic of China, and the Anti-Unfair Competition Law of the People's Republic of China, as well as applicable international treaties.
Without prior written authorization from SMM, no institution or individual may:
1. Use all or part of this report in any form (including but not limited to reprinting, modifying, selling, transferring, displaying, translating, compiling, disseminating);
2. Disclose the content of this report to any third party;
3. License or authorize any third party to use the content of this report;
4. For any unauthorized use, SMM will legally pursue the legal responsibilities of the infringer, demanding that they bear legal responsibilities including but not limited to contractual breach liability, returning unjust enrichment, and compensating for direct and indirect economic losses.
Data Source Statement:
(Except for publicly available information, other data in this report are derived from publicly available information (including but not limited to industry news, seminars, exhibitions, corporate financial reports, brokerage reports, data from the National Bureau of Statistics, customs import and export data, various data published by major associations and institutions, etc.), market exchanges, and comprehensive analysis and reasonable inferences made by the research team based on SMM's internal database models. This information is for reference only and does not constitute decision-making advice.
SMM reserves the final interpretation right of the terms in this statement and the right to adjust and modify the content of the statement according to actual circumstances.