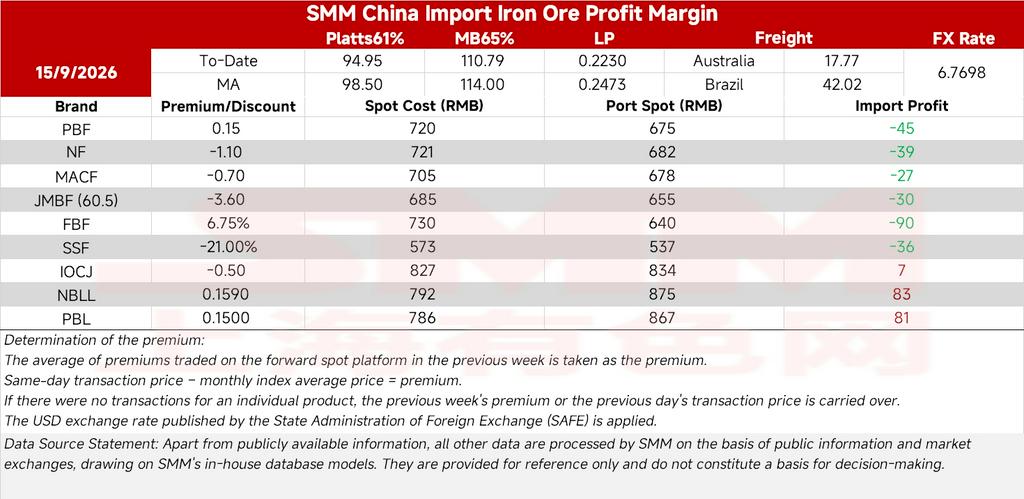
The average imported iron ore margin narrowed further this period, from -9.15 yuan/mt to -10.61 yuan/mt, dragged down by continued declines in spot prices.
Coke prices remain high and some mills have entered maintenance on tight coke supply, weakening rigid demand for iron ore. On supply, SMM data showed port inventories holding a pattern of high stocks with limited draws and limited builds, little changed from the previous week. SMM put global iron ore shipments at 37.41 million mt, up 9% week on week and flat on a cumulative year-on-year basis. Shipments from Australia and non-mainstream origins rose, while Brazil edged lower. Arrivals at Chinese ports came to 26.91 million mt last week, steady week on week and up 4.2% year to date.
With demand contracting and supply holding, iron ore prices are likely to stay weak in the near term, and imported margins are likely to remain around current levels.