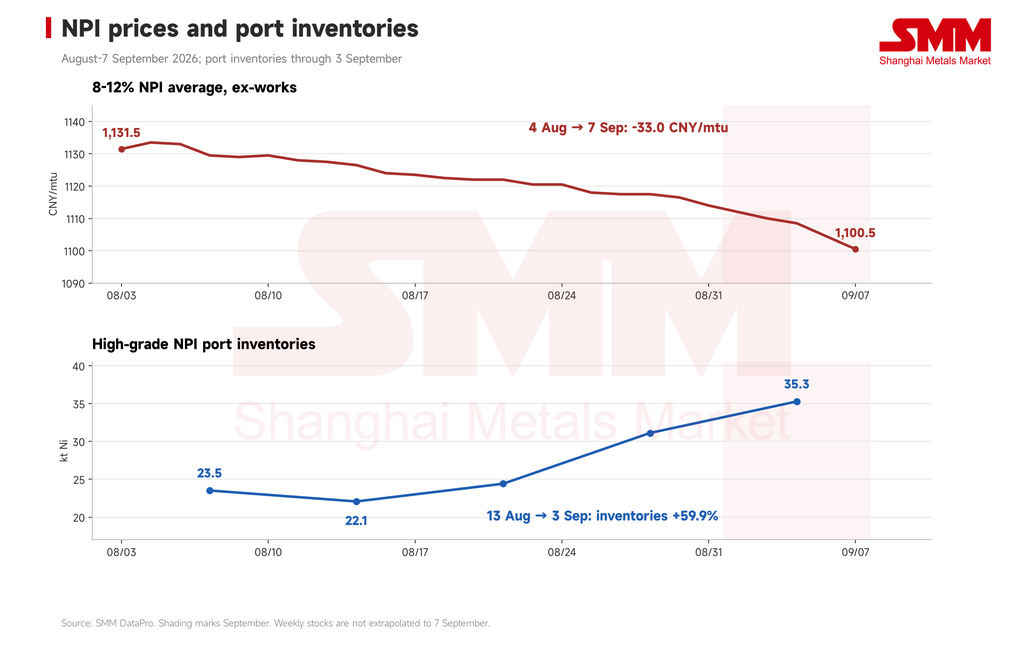
NPI prices fell again as September entered its second week. On 7 September, SMM’s assessment for 8–12% NPI, ex-works, dropped to CNY 1,100.5/mtu, down 4 from the previous Friday and 13.5 from the end of August. One major stainless mill lowered its buying indication to CNY 1,090/mtu while reporting ample inventories and no immediate plans for large-volume purchases. A trader said its offer at CNY 1,100/mtu still attracted no buying from mills.
Prices have reached a level the market had repeatedly discussed, but buyers have not returned in force. That says more about the strength of China’s traditional September peak season than another small price decline.
At first glance, lower-priced transactions should help establish support. Inventory positions explain why that has yet to happen. Mills that need material are buying at lower prices; those with sufficient stocks can keep waiting. Transactions are setting fresh price references without triggering a broad restocking cycle.
The procurement weakness visible in mid-August has carried into September. Sellers are cutting prices faster than mills are rebuilding demand.
Chinese NPI prices are quoted in CNY/mtu, inclusive of 13% VAT unless otherwise stated. One mtu represents 1% nickel in a tonne of alloy, or 10 kg of nickel. Delivery terms are specified where available.
Lower-priced deals have not brought mills back in force
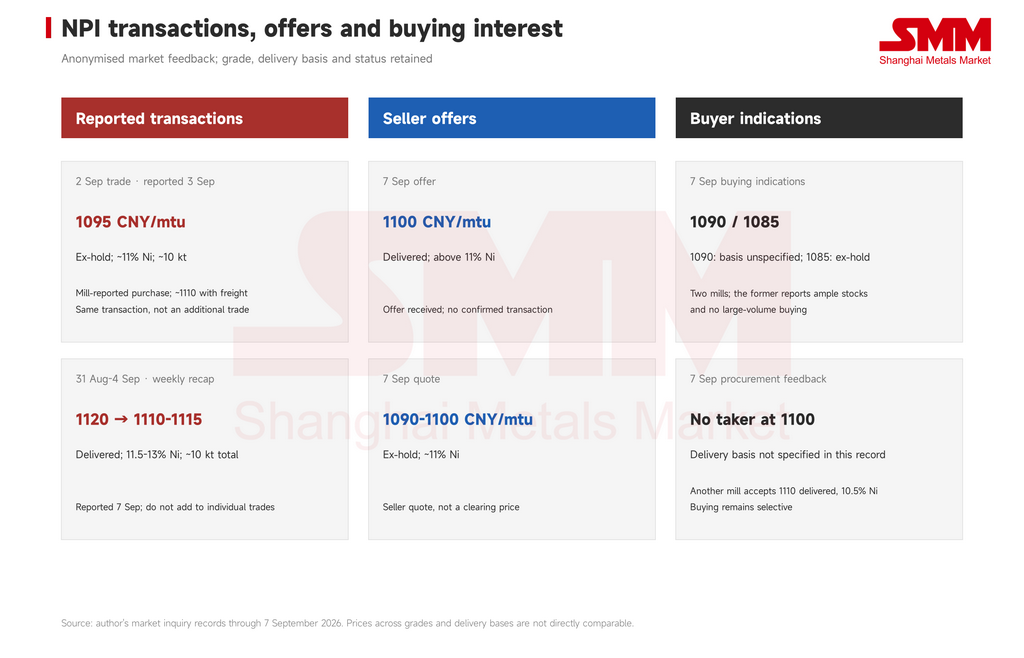
One mill bought approximately 10 kt of NPI containing around 11% nickel last week at CNY 1,095/mtu ex-hold. A trader separately reported roughly 10 kt of sales over the week, with delivered prices for 11.5–13% material declining from CNY 1,120/mtu early in the week to 1,110–1,115. Lower prices have generated business, but the market has not seen a widespread return to procurement.
By 7 September, a trader had received an offer for material above 11% nickel at CNY 1,100/mtu delivered. Another reported that mills declined its offer at 1,100. Sellers continued to concede without a corresponding acceleration in buying.
One major mill lowered its indication to CNY 1,090/mtu while reiterating that its inventories were sufficient and large purchases were unnecessary. Another maintained an indication of CNY 1,085/mtu ex-hold. A trader reported that several mills would only consider buying around CNY 1,080/mtu ex-hold, suggesting that buyers’ targets were still moving lower.
Some mills remain willing to buy near current levels. One said it had lowered its minimum nickel-grade requirement to 10.5% and could accept CNY 1,110/mtu delivered. Demand has not disappeared, but purchasing remains tied to individual inventory positions, feed specifications and production needs.
Mills with stocks can wait. Sellers seeking an outlet must keep adjusting their terms. Whether 1,100 holds depends on whether purchases continue after the initial lower-priced deals.
Premiums are shrinking, with differences across grades
Buyers’ willingness to wait is also squeezing premiums.
On 19 August, a trader reported that some mills had lowered their buying indications from a premium of CNY 15/mtu to plus 5 or flat, with some showing little urgency even at flat terms. By 27 August, market feedback placed material around 10% nickel close to SMM’s average assessment, with much of the material below 11% also trading near flat. Lower-grade premiums weakened first.
Higher-grade material retained some support. On 3 September, a supplier was still offering 11% material at a premium of CNY 10/mtu. The following day, another participant reported that 11% material continued to trade at a premium. A falling market has not eliminated differences in availability across grades.
Mills are also adjusting their requirements. A buyer lowering its minimum grade to 10.5% gains access to a wider pool of material. Where mills have flexibility in their feed mix, higher-grade suppliers need sufficient operating value to justify the premium.
The underlying issue remains inventory and procurement urgency. A well-stocked mill has little reason to pay extra to secure material ahead of need. Premiums may survive for some grades without lifting the broader market.
Rebuilding inventories give mills little reason to chase cargoes
Procurement caution was already evident in mid-August. On 19 August, a major mill reported sufficient NPI and stainless scrap inventories and suspended purchasing. On 7 September, ample stocks remained its reason for avoiding large purchases. That continuity matters more than the seasonal label.
Port availability has also increased. SMM’s high-grade NPI port inventory rose from 22.1 kt of nickel on 13 August to 35.3 kt on 3 September, an increase of approximately 60%. The rebuilding buffer has weakened support from earlier spot tightness and given mills more room to choose and wait.
On 4 September, a mill reported a noticeable increase in sellers approaching it to ask whether it needed NPI. The pressure to move material was becoming visible in sellers’ behaviour.
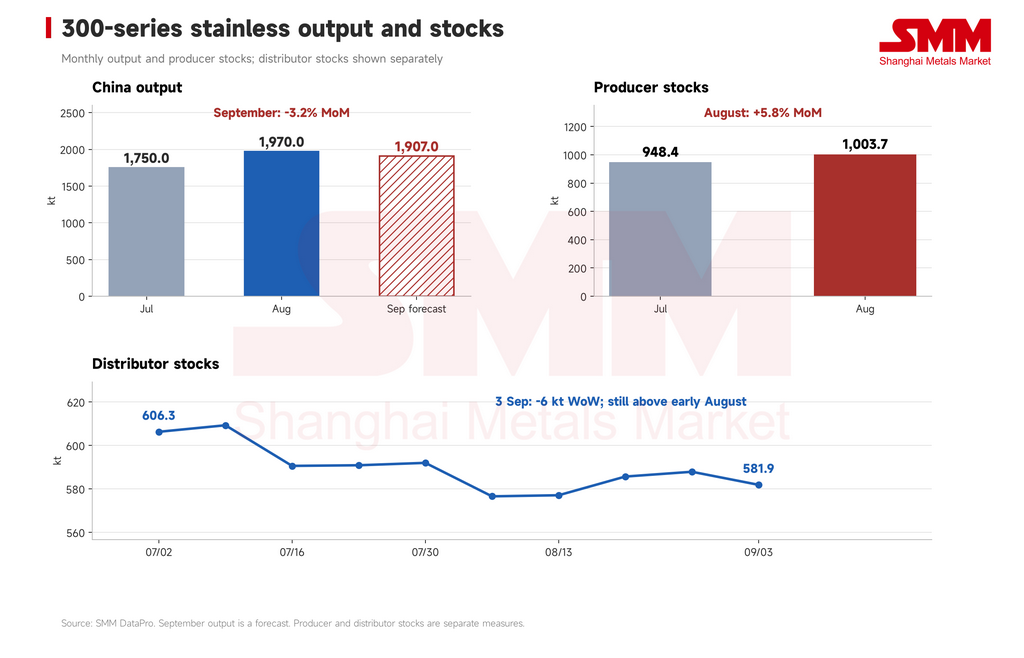
Finished stainless inventories provide little encouragement for aggressive raw-material buying. China produced 1.97 Mt of 300-series stainless in August. September’s production forecast stands at 1.907 Mt, down 63 kt, or about 3.2%, month on month. Producer inventories increased from 948.4 kt in July to 1,003.7 kt in August, leaving mills with more finished material to sell.
There are signs of improvement. Distributor inventories stood at 581.9 kt on 3 September, down 6 kt from the previous week, although still above early August. SMM’s 304 cold-rolled margin improved from -0.95% on the previous Friday to -0.76% on 7 September. Losses narrowed, but production remained unprofitable on that measure.
Weekly destocking and a modest margin recovery are welcome developments. They have not yet created a compelling reason to buy raw materials ahead of requirements. The seasonal pickup needs to translate into sustained stainless sales and inventory drawdowns before mills have reason to increase external purchases.
Cheaper ore offers a buffer, but Indonesian margins are still narrowing
Indonesian prices are adjusting alongside lower Chinese buying levels. On 7 September, SMM’s Indonesia NPI FOB index fell to USD 142.7/mtu, down 0.7 from the previous Friday. The assessment for Indonesian 10–12% NPI landed in China, inclusive of tax, declined by CNY 4/mtu to 1,110.
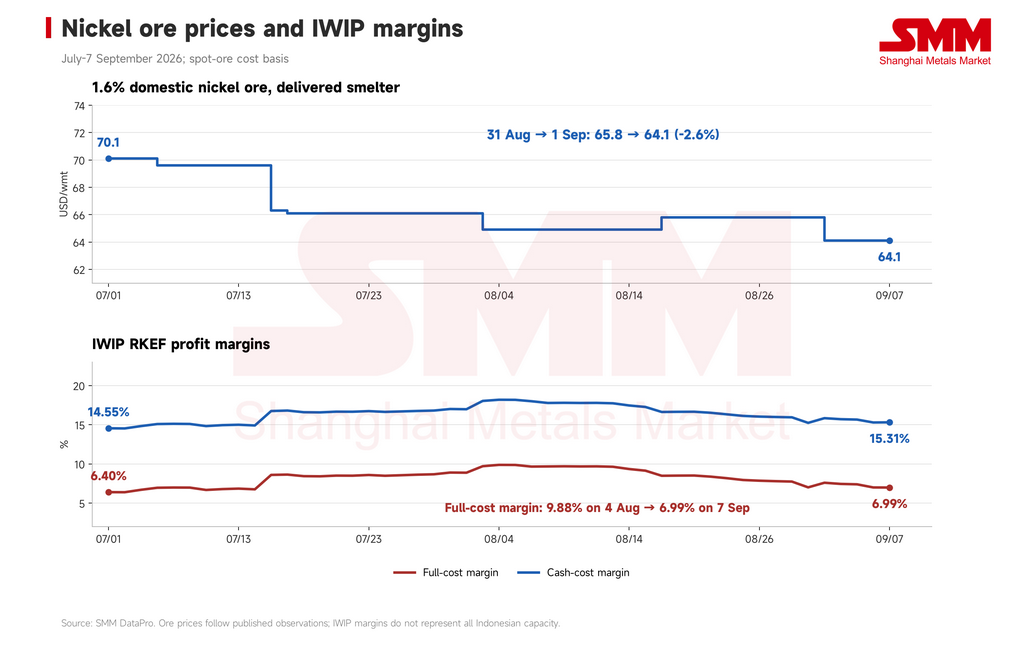
Cheaper ore has provided some relief. At the start of September, the assessment for Indonesian domestic 1.6% nickel ore delivered to smelters fell from USD 65.8/wmt at the end of August to 64.1, a decline of approximately 2.6%. Against USD 79.3/wmt in late May, the cumulative fall was close to 20%. Earlier ore-price reductions have helped smelters preserve margins.
They have not prevented those margins from narrowing. On 7 September, SMM’s IWIP spot-ore full-cost margin stood at 6.99%, down 2.89 percentage points from 9.88% on 4 August. The cash-cost margin remained at 15.31%. Lower ore prices have eased operating pressure, but falling NPI selling prices continue to erode profitability.
A supplier on 7 September cited market reports of drought in parts of Indonesia and highlighted pressure on sellers. Further deterioration in power, water or ore conditions could affect production at some facilities.
For now, however, the available output data show an expanding supply base. Indonesian NPI production rose from 127.5 kt of nickel in June to 135.1 kt in August, an increase of approximately 6%. Narrower margins would need to translate into actual production cuts or lower shipments to provide stronger price support. The relief from cheaper ore also leaves some producers with room to keep operating.
As September enters its second week, inventory absorption remains central to the market. Lower spot prices can prompt individual purchases without shortening the waiting time of well-stocked mills. Upstream margins are contracting, but a sufficiently clear supply response has yet to emerge.
For sellers seeking stability around 1,100, the test is whether buyers keep buying after the first lower-priced transactions. Otherwise, today’s acceptable discussion level may simply become the starting point for another round of concessions.
Written by Bruce Chew
Nickel & Stainless Steel Analyst, Shanghai Metals Market
Email: bruce.chew@metal.com
Tel: +601167087088