A Sharper Break From June's Flat Reading
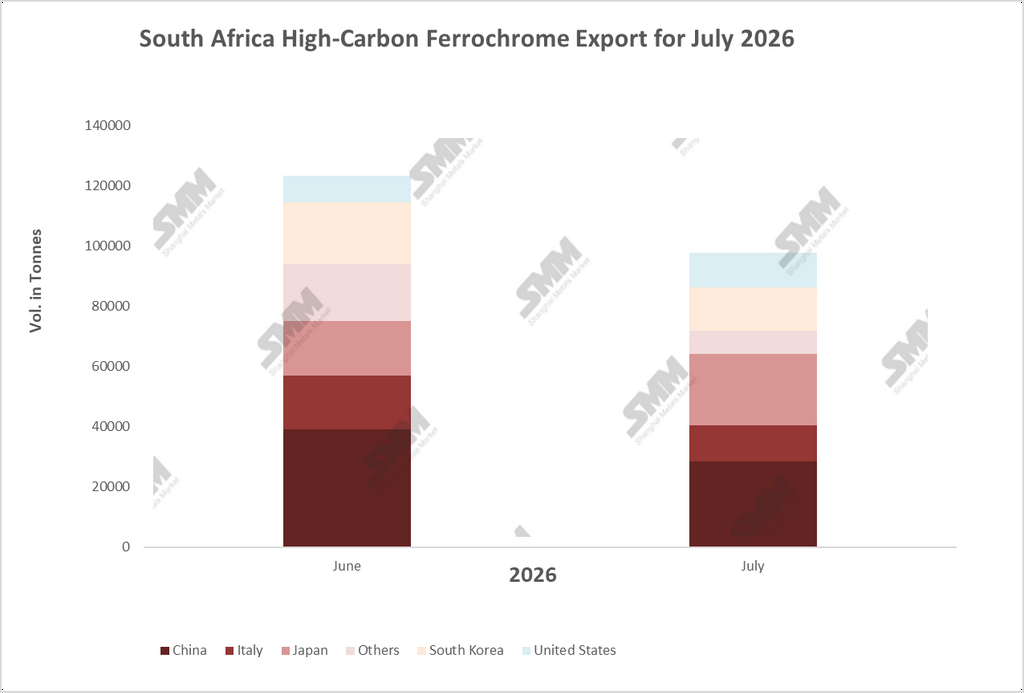
South Africa's high-carbon ferrochrome (HC FeCr) exports fell to 97,656 mt in July 2026, down 20.8% month-on-month from June's 123,310 mt. The decline marks a clear break from June, which had come in essentially flat against May's 123,795 mt — a pattern consistent with a market that had stabilized after its 2025 collapse. July's data shows that stabilization was not the same as recovery: the sector's underlying fragility remains, even as chrome ore exports continue setting fresh highs.
China Pulls Back as a Glut Warning Lands
China remained the largest single destination for South African ferrochrome, but its purchases fell 27.2% month-on-month, from 38,921 mt to 28,337 mt, pulling its share of total exports down from 31.6% to 29.0%. The pullback lines up closely with Merafe Resources' half-year results, released on August 11, which flagged a potential ferrochrome glut heading into the second half of 2026, driven by rising Chinese domestic output and weak global stainless steel demand. China has spent the past two years expanding its own ferrochrome smelting capacity even as it remains the top buyer of South African ore, effectively competing with South African alloy in its own downstream market. The timing — a softer China print in the same month Merafe warned of a Chinese-driven glut — points to the same underlying dynamic.
Japan and the US Move the Other Way
Japan moved in the opposite direction. Its imports of South African ferrochrome rose 31.8% month-on-month, from 17,988 mt to 23,716 mt, overtaking both Italy and South Korea to become the second-largest destination and lifting its share of total exports from 14.6% to 24.3%. The United States posted a similar gain, up 29.0% to 11,415 mt. Both markets have structural reasons to behave differently from China: Japan's stainless steel sector is a longstanding, quality-focused buyer of South African high-carbon ferrochrome, while the United States sources roughly 41% of its ferrochromium imports from South Africa and holds ferrochromium within its National Defense Stockpile as part of a critical-minerals posture that has kept chromium on every U.S. critical minerals list since 2018. The volumes involved remain small — 11,000 to 24,000 mt — so a single large shipment or a shift in vessel scheduling could account for much of July's swing in either market; one month of data confirms a gain, not yet a reversal in either country's underlying import pattern.
A Broadly Softer Month Beyond China
The declines across the remaining destinations were broader-based and less attributable to any single buyer. Italy fell 33.3% to 12,000 mt, South Korea fell 29.3% to 14,504 mt, and the “Others” category — likely the most diffuse, and therefore the most exposed to any pullback in general trading appetite — fell 59.7% to 7,684 mt, its steepest decline of any destination in the dataset. Four of the six tracked destinations moved lower in July, pointing to a broadly softer month for South African ferrochrome demand rather than one explained by any single buyer's behavior.
A Restart Still Early in Its Ramp-Up
The supply-side backdrop explains why a stronger July was unlikely regardless of demand conditions. Merafe's H1 2026 results show attributable ferrochrome production from the Glencore-Merafe Chrome Venture collapsed 75% to just 28,000 mt over the six months to June, a consequence of the extended suspension of the Wonderkop and Boshoek smelters and a partial suspension at Lion. Wonderkop and Boshoek's restart was confirmed only in late June, once Eskom and the venture finalized the detailed terms of the 62 cents/kWh negotiated pricing agreement NERSA had approved in May — making July effectively the first month in which incremental output from those two smelters could reach the export market. Furnace restarts do not translate into shipping volumes overnight. Lion's own recovery offers a timeline guide: after its first production tap on February 16, the smelter was not expected to reach full operating capacity until the end of March — five to six weeks for a single furnace complex. Wonderkop and Boshoek, restarting three months later, are almost certainly still early in the same ramp-up curve, consistent with July's export data showing no sign yet of a production-driven rebound.
The Ore-Ferrochrome Divergence Widens
The divergence between the two halves of South Africa's chromium trade has grown starker through 2026: chrome ore exports are climbing to fresh highs while ferrochrome exports move lower, with more raw ore leaving the country and comparatively less of it converted into higher-value alloy domestically before export. Tariff relief and the phased smelter restarts have arrested ferrochrome's free-fall, but July's data confirms they have not yet reversed the decline.
|
Outlook: South Africa's ferrochrome exports remain caught between a slow, capital- and time-intensive domestic recovery and a global demand environment Merafe itself has flagged as at risk of oversupply. The Wonderkop and Boshoek restarts should begin contributing incremental volume over the coming months, but the ramp-up curve seen at Lion suggests that process will likely extend well into the fourth quarter before it shows up meaningfully in export data. China remains both the largest buyer of South African ferrochrome and an increasingly capable competitor to it — a genuine two-sided risk. Further growth in Chinese domestic output could keep pressuring China's offtake, even as the rest of the market — Japan and the U.S. in particular — offers only partial and currently thin compensation. |