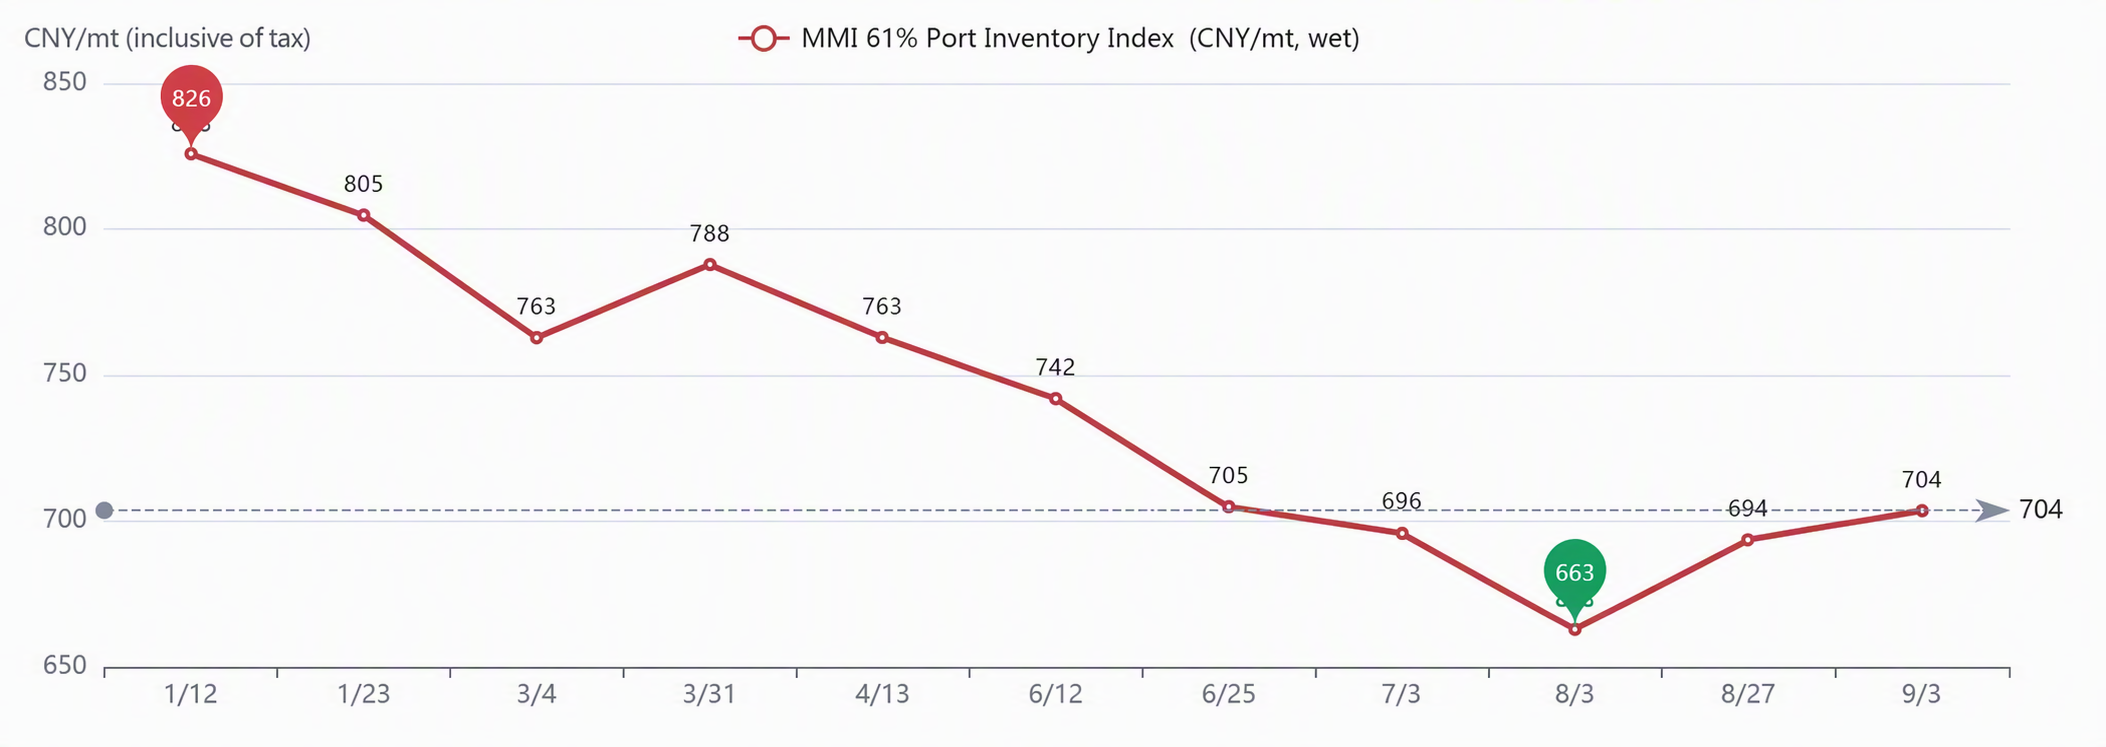
Iron ore prices consolidated on a strong note this week, with the most-traded I2701 contract hitting an intraday high of 730 yuan/mt and prices remaining within the year's low range of 700-730 yuan/mt. This rebound was driven by a confluence of factors rather than a single catalyst. First, BHP's labor negotiations at Port Hedland reached an impasse (on August 25, the union rejected the wage proposal, involving approximately 450 port workers, with the next round of talks scheduled for September 8), creating supply tightening expectations in sentiment; meanwhile, ocean freight rates on major routes remained elevated amid Middle East disruptions, and higher import costs further reinforced price floor support. Second, with the traditional September-October peak season approaching, coupled with a significant drawdown in port inventories this week (35-port inventories -1.7 million mt) but steel mill inventories falling by more than 1 million mt, the market held expectations for a September restocking rally, boosting sentiment. Third, coking coal and coke prices rose sharply this week—the fourth round of coke price increases was fully implemented on September 2 (coke wet quenching +100 yuan/mt, coke dry quenching +110 yuan/mt), driving finished steel prices higher, and iron ore, as a raw material, followed the rally passively, providing some boost to ore prices. Overall, this rebound in iron ore was strongly supported by sentiment and the cost side, but the drivers were largely "follow-through" in nature, and the fundamental pattern of strong supply and weak demand has not fundamentally reversed, limiting the rebound's upside. Future trends will hinge on the pace of end-use demand release and developments on the supply side.
Chart: MMI 61% Port Spot Index
Source: SMM
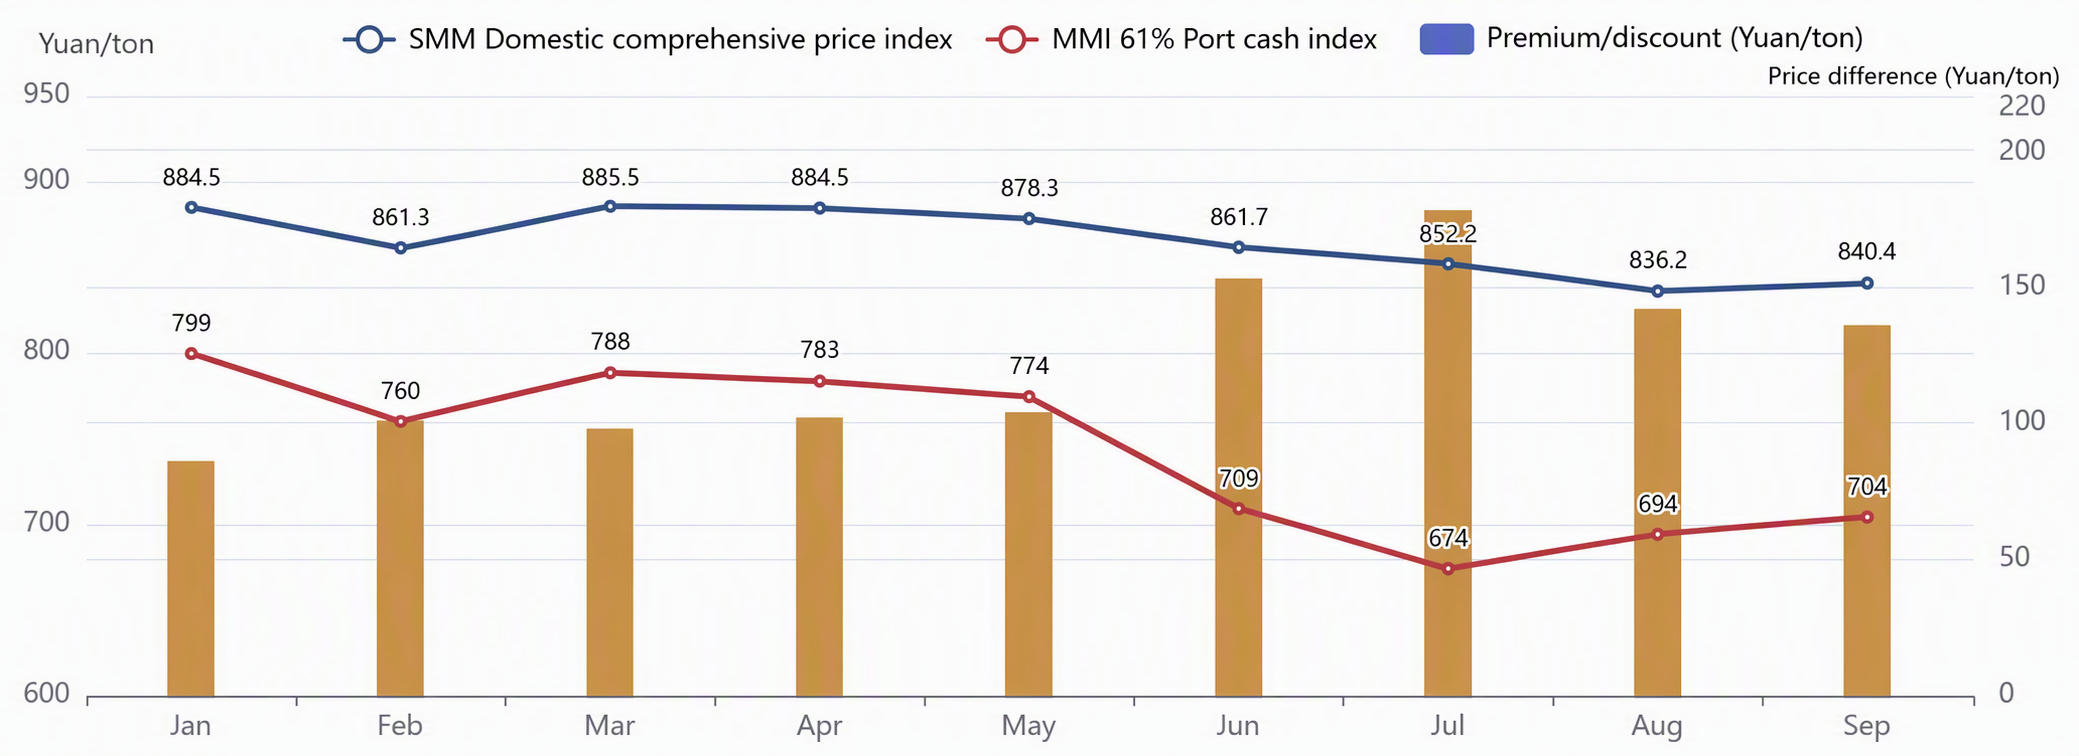
Chart: Domestic and Imported Ore Price Spread Narrowed Further This Week; Expected to Remain Relatively Stable Next Week
Next Week Outlook
Looking ahead to next week,on the supply side, as port maintenance in Australia and Brazil winds down, coupled with the usual Q3-end shipment push by overseas mines, shipments are expected to accelerate; meanwhile, steel mills have already begun pre-National Day holiday stockpiling, and forward spot transaction volumes have expanded, with overall supply-side growth accelerating. On the demand side, four consecutive rounds of coke price increases have significantly compressed steel mill profits, pushing the industry to near-total losses, with some high-cost mills facing cash flow distress and increasing blast furnace maintenance and production halt plans, exerting clear pressure on iron ore demand. Under the strong supply and weak demand pattern, upside resistance for iron ore prices is mounting, but downside support remains: BHP's Port Hedland labor negotiations are set to resume on September 8, and another impasse would reinforce supply tightening expectations, while elevated ocean freight rates also lift the ore price floor from the cost side. Additionally, the market still holds expectations for the September-October peak season; combined with pre-National Day stocking demand and recent macro tailwinds, ore prices still have upward drivers. In summary, the tug-of-war between longs and shorts is expected to intensify significantly next week, and iron ore prices are likely to show a repeated consolidation pattern.