

SMM News, September 4:

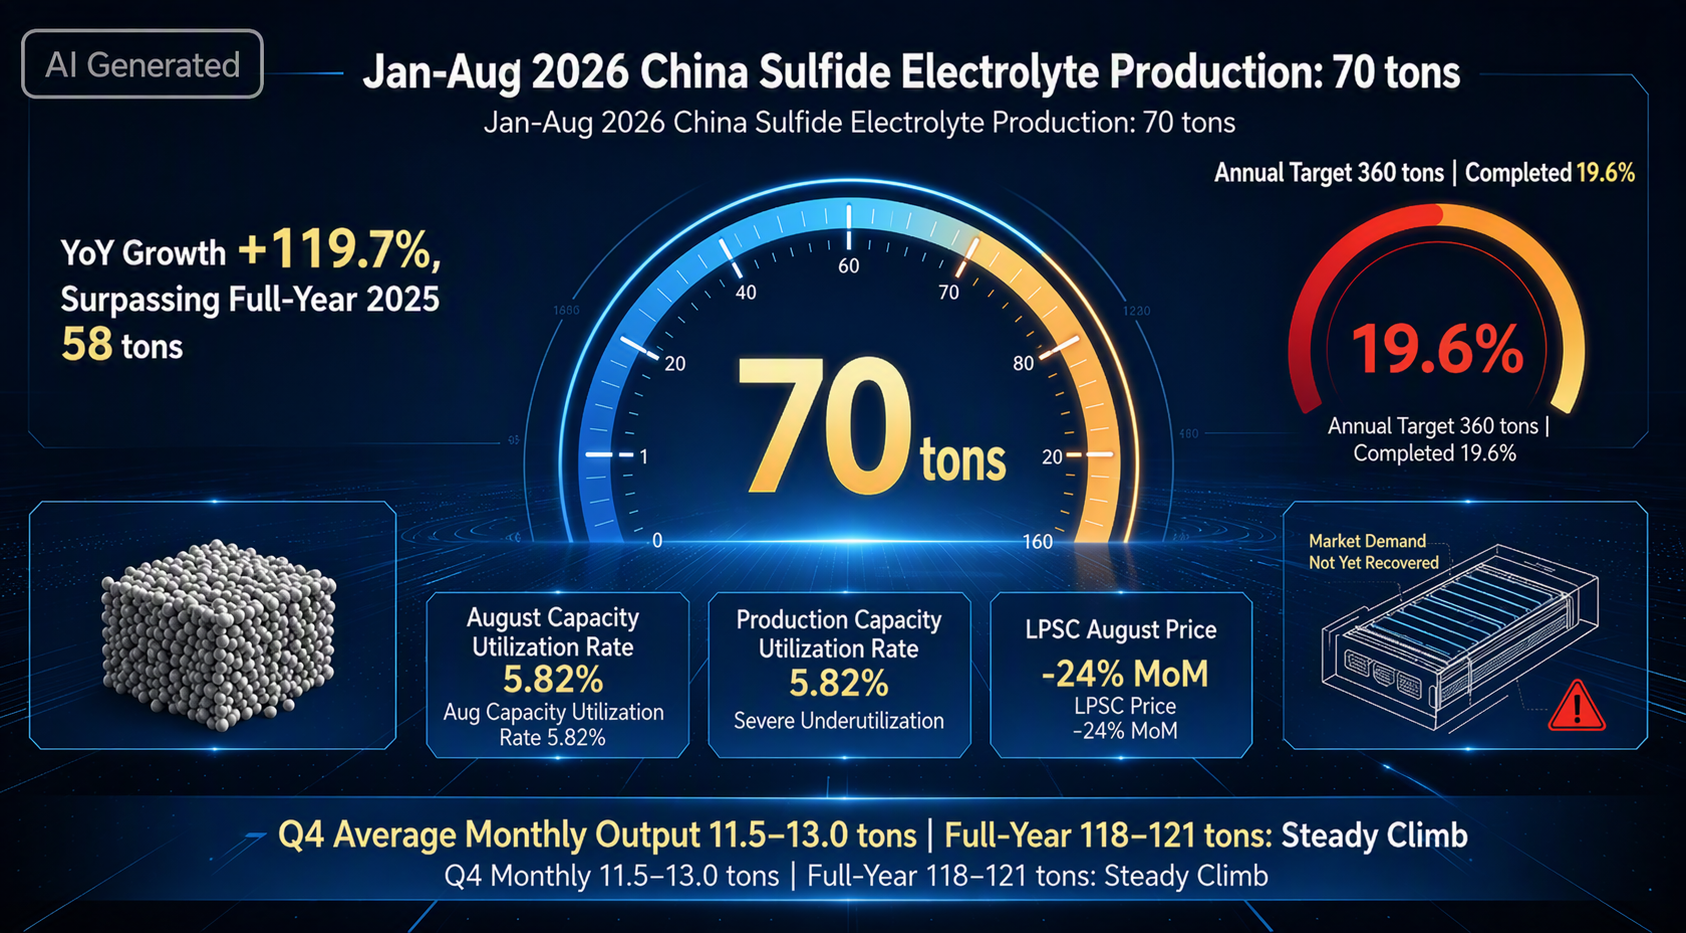
Key points: In August 2026 and cumulatively from January to August 2026, China’s cumulative sulphide electrolyte production reached 70 mt, surging 119.7% YoY and already exceeding the full-year 2025 total (58 mt). However, this eye-catching growth masks three harsh realities: (1) only 19.6% of the annual forecast target (360 mt) has been achieved; (2) the August capacity utilization rate was only 5.82%, indicating severe idle capacity; (3) product prices continued to plunge (LPSC fell by more than 24% in a single month). Average monthly production in Q4 is highly likely to fall within the 11.5-13 mt range, with the full-year total at around 118-121 mt—“a solid ramp-up.” With an annual forecast of 360 mt, only 70 mt was completed in the first eight months: the “mild volume release” of China’s sulphide electrolyte and the reality gap.
I. Production Review
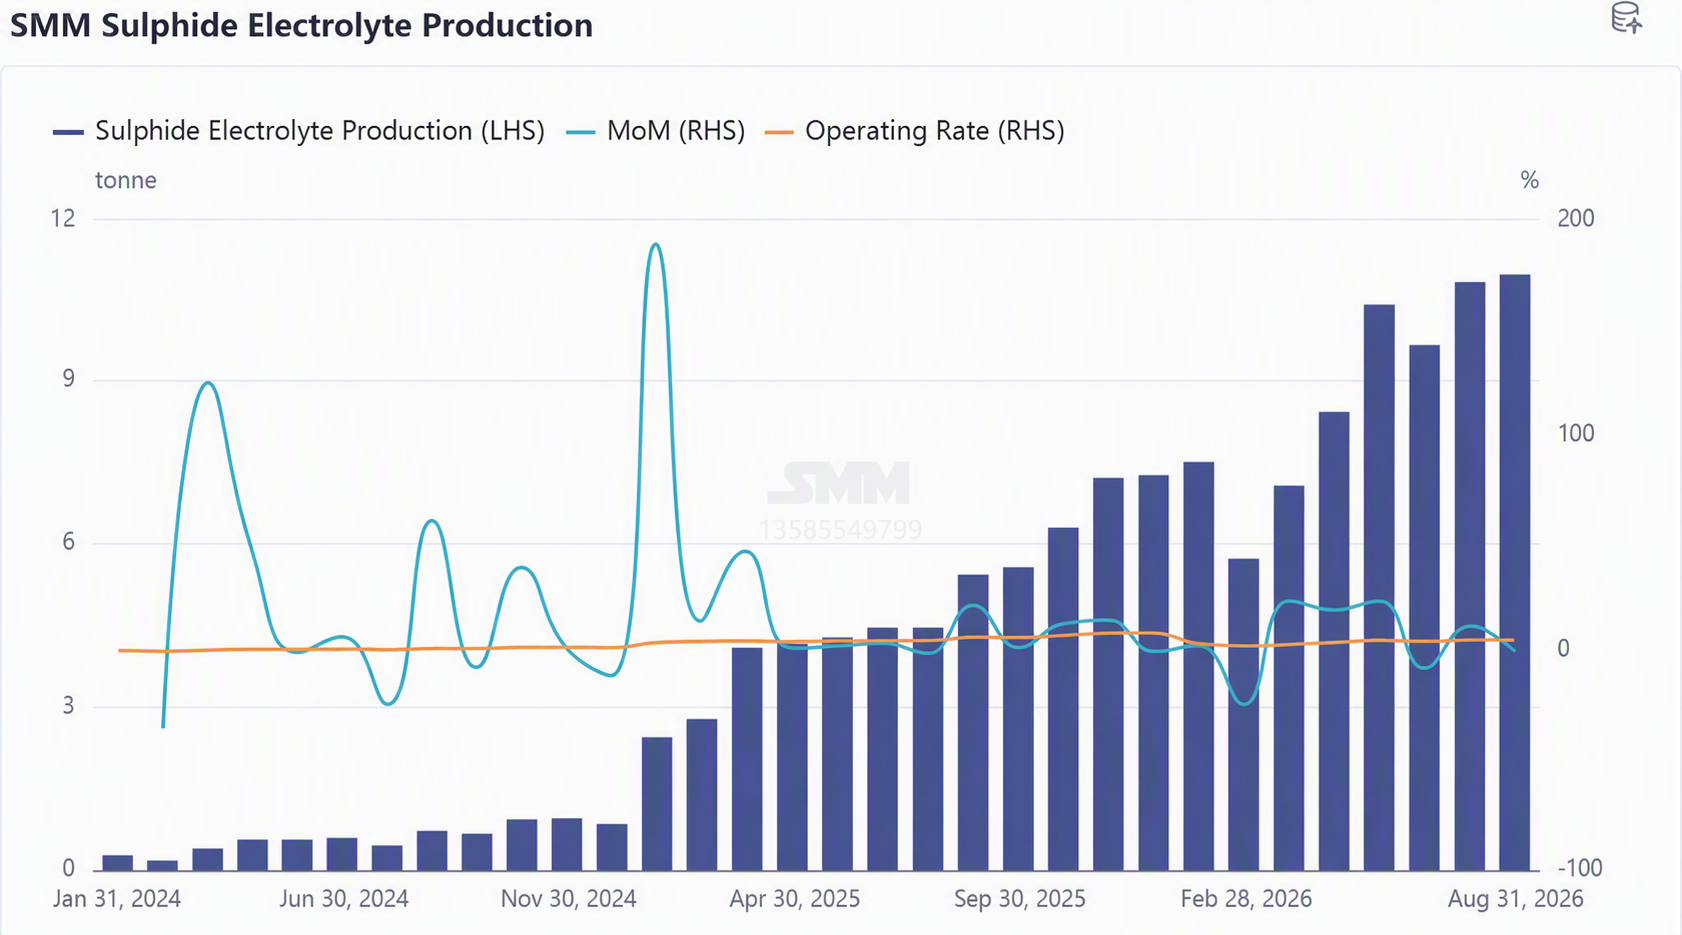
From a cumulative perspective over the first eight months, total sulphide electrolyte production from January to August 2026 was about 70 mt, up about 120% from the same period in 2025 (about 32 mt). This scale is close to 75% of full-year 2025 production (94 mt), while full-year 2024 production was only about 7 mt, meaning the outline of the industry’s “mt-level volume release” has begun to take shape. In August, production reached a record high of nearly 11 mt. Despite setting a new record, the MoM growth rate pulled back from double digits in May–July to single digits (May up 23.5% MoM from April, July up 12.1% MoM, and August only up 1.2% MoM), indicating that actual output in August was in a “platform period during the ramp-up.” This fully aligns with the industry pace: in H1, the industry chain mainly focused on “line construction, commissioning, and sample delivery.”
But bringing the perspective back to reality: what does 70 mt mean? It is only equivalent to the daily output of basic chemical products at a mid-sized chemical enterprise. As the most core material for solid-state batteries, this absolute scale clearly indicates that the industry is still in the early stage of “sample validation and small-batch procurement,” far from large-scale application. Even with 70 mt of production, shipments were only just over half; product yield and consistency need to improve, and downstream battery cell enterprises’ customized procurement also makes it difficult for sulphide electrolytes to serve multiple clients with a single product.
But bringing the perspective back to reality: what does 70 mt mean? It is only equivalent to the daily output of basic chemical products at a mid-sized chemical enterprise. As the most core material for solid-state batteries, this absolute scale alone is sufficient to show that the industry is still at a very early stage of commercialization.
More critically: this 70 mt is “production,” not “effective supply.” According to SMM data, actual sulphide electrolyte shipments were only around 60%, and there is a significant gap between production and shipments: a considerable portion of products are still in production-line commissioning, process validation, or the ramp-up stage of quality improvement, and have not yet been recognized and accepted by downstream clients. In other words, not only is the “volume” small, but the “effective output” that can truly flow into end-use applications is even smaller.
The root causes lie in two hard constraints:
First, bottlenecks in yield and consistency. Sulphide electrolytes are extremely sensitive to moisture and oxygen content, and batch stability in scaled production is a widely recognized industry challenge. There remains a huge gap between being able to “make samples” and being able to “deliver qualified products in batches.”
Second, the customized procurement model prevents supply from being replicated at scale. Currently, downstream battery cell enterprises mostly adopt a one-to-one joint development model, and each has customized requirements for electrolyte composition, particle size, ionic conductivity, and other metrics. This means that each time a materials producer serves a client, it often needs to adjust formulations and process parameters separately, making it difficult to achieve standardized, large-scale production and sales like mature lithium battery materials. Production is small to begin with, and it must also be split into multiple “custom batches”—a severe test for both cost control and delivery efficiency.
Overall, 70 mt of production, 49 mt of shipments, a capacity utilization rate below 6%, and persistently plunging product prices—these data points together paint an industry picture: sulphide electrolytes have indeed crossed the "0 to 1" laboratory threshold, but the "1 to 100" journey toward large-scale commercialization has only just begun.
II. Three forces keeping August production high
2.1 Supply side: production lines coming online in concentrated fashion.
On 5 August, Sinocera announced the completion of its automated sulphide electrolyte production line, with initial mass-production capability established, seen as an important period in China's sulphide electrolyte transition from "laboratory samples" to "batch supply from production lines"; Tinci's 100 mt/year lithium sulphide and sulphide electrolyte pilot line is expected to be completed and put into production in Q3; Tianshi Kefeng completed tens of millions of yuan in new financing, accelerating sulphide electrolyte capacity expansion; Ronbay Technology also plans to complete a ten-mt-class sulphide electrolyte production line within the year.
2.2 Demand side: stockpiling momentum continues.
In July, a major new energy company completed a 1 mt-class sulphide electrolyte tender, with the winning price below 2 million yuan/mt, marking the industry's formal move from "kg-level transactions" to "mt-level transactions". Downstream battery cell enterprises are ramping up procurement and stockpiling willingness in preparation for the 2027 vehicle installation period. August saw intensive industrial validation events: Zhongke Yuanben completed China's first sulphide all-solid-state real-vehicle road test, and Gaoneng Shuzao's 20Ah sulphide all-solid-state battery cell passed a 4mm steel needle puncture test, both boosting confidence in the sulphide route.
2.3 Raw material side: falling costs lower the barrier to capacity expansion.
Battery-grade lithium sulphide prices have fallen to around 1,300 yuan/kg (down more than 50% from the beginning of the year). High-purity lithium sulphide accounts for 70%–80% of total sulphide electrolyte costs, and the raw material price decline directly reduces the cost of large-scale electrolyte production.
III. Capacity review
But what deserves even closer review is capacity. Sulphide electrolyte capacity is relatively large. Currently in production are Guyan, Guolian, Saike, Ruigu, Firm-Lithium, Sinocera, Yinshi, Tianshi Kefeng, Jiangfeng, LionGo, and Guneng, among others, with Tinci and others yet to commence production.
Monthly effective capacity rose from 39.17 mt/month in 2024, to 80 mt/month in March 2025, then jumped to 187.6 mt/month in January 2026, and was slightly adjusted to 188.1 mt/month in August—in two years, capacity expanded to 4.8 times its original level (annualized at approximately 2,257 mt), while production only roughly doubled.
The result was a dilution of the operating rate: in December 2025, the operating rate once climbed to 9.0%, then plunged to 4.0% in January 2026 after a jump in capacity, hit a low of 3.0% in February (Chinese New Year + capacity ramp-up), and only recovered to 5.8% by August.
Sulphide electrolyte capacity is already in place, but will Q4 production accelerate? This is a major question for the industry, and upstream raw material enterprises for sulphide electrolytes are also extremely concerned about it. In Q4, average monthly production is expected to reach the 12-13 mt range, with the full-year total landing at 115-125 mt. The real jump will have to wait until after demonstration vehicle orders are placed in 2027.
IV. Price analysis: the "luxury" pricing of 4 million yuan/mt must move towards affordability
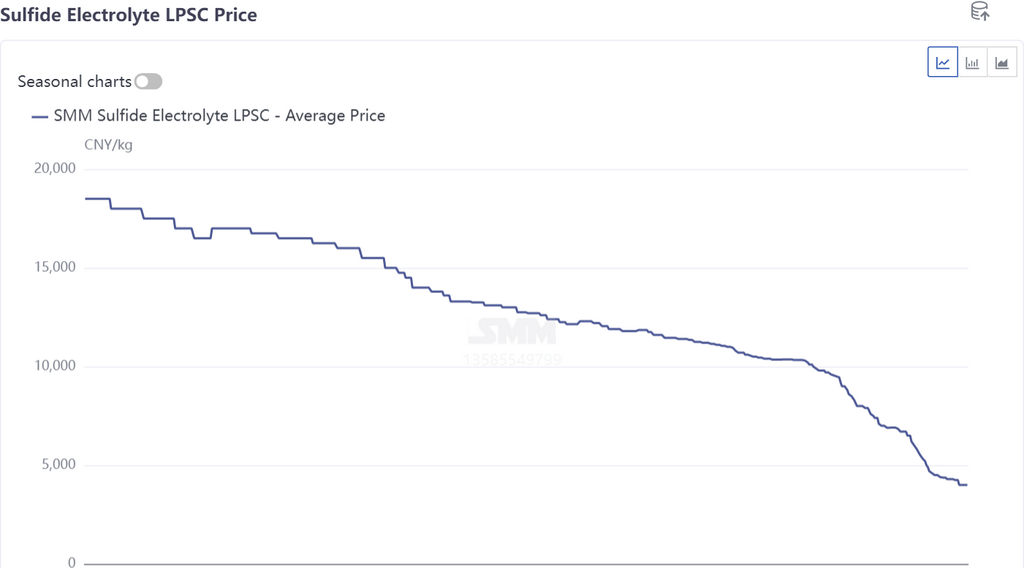
The current sulphide electrolyte market is still in a typical "early industrialisation pricing" stage, with LPSC prices at around 4 million yuan/mt (i.e., 4,000 yuan/kg). For the power battery industry, which is extremely cost-sensitive, this price is at a "luxury" level.
In contrast to the mild growth in production, sulphide electrolyte prices continued to decline at an accelerating pace in August. The average price of LPSC (Li₆PS₅Cl type, powder D50 ≤3μm) fell from 4,500 yuan/kg in early August all the way to 4,000 yuan/kg on 26 August, a single-month decline of about 11%; compared with 6,700 yuan/kg in early July, the cumulative decline was about 40%, and YoY (around 11,800 yuan/kg in the same period of 2025) the decline was about 66%.
Downstream battery enterprises have a clear understanding of this and are exerting pressure for cost reduction:
Short-term threshold (within 1-2 years) : the expected price should contract to within 2 million yuan/mt, so as to initially establish the economic basis for small-batch demonstration applications;
Long-term target (after 3-5 years): anchored at a price range of 500,000-1 million yuan/mt. Only in this way can sulphide solid-state batteries compete substantively with conventional liquid batteries and semi-solid-state batteries on the cost dimension.
The significance of this price expectation lies not in "bargaining", but in forcing material manufacturers to shift their cost models from laboratory-scale small-batch preparation (gram-level, kilogram-level) to industrial-scale mass production (mt-level, tens of mt-level), spreading fixed asset depreciation through economies of scale, reducing raw material procurement costs, and improving yield rates, so as to potentially bring per-mt costs down from the millions to below the one-million level.
By comparison, the price of lithium sulphide, a key upstream raw material for sulphide electrolytes, has already pulled back sharply from its high at the beginning of the year, falling by more than 50% over the past six months to around 1,300 yuan/kg; the rapid decline in upstream raw material prices is opening up room for the final product price of sulphide electrolytes to fall, but there is still nearly half of the cost-reduction gap to be closed before reaching the short-term threshold of 2 million yuan/mt set by battery enterprises.
Note: If you have any additional details to share regarding the points mentioned in this article, or if you are following the development of solid-state batteries, please feel free to contact us at:
Tel: 021-20707860 (or add WeChat 13585549799) Yang Chaoxing, thank you!
Related reading



