As August began, the magnesium market appeared trapped in a prolonged stalemate.
The production-cut tailwinds from July faded, and primary magnesium supply steadily recovered. Meanwhile, overlapping with the overseas summer lull and the domestic die-casting off-season, downstream orders were scarce and purchasing sentiment hit rock bottom. Amid weak supply and weak demand, magnesium prices were firmly locked in the narrow range of RMB 15,800–15,950 per ton, with neither upward nor downward momentum. In mid-to-late August, prices even dipped to RMB 15,750 per ton. The market watched and waited broadly—when this two-month-long bottom consolidation would see a turnaround remained anyone's guess.
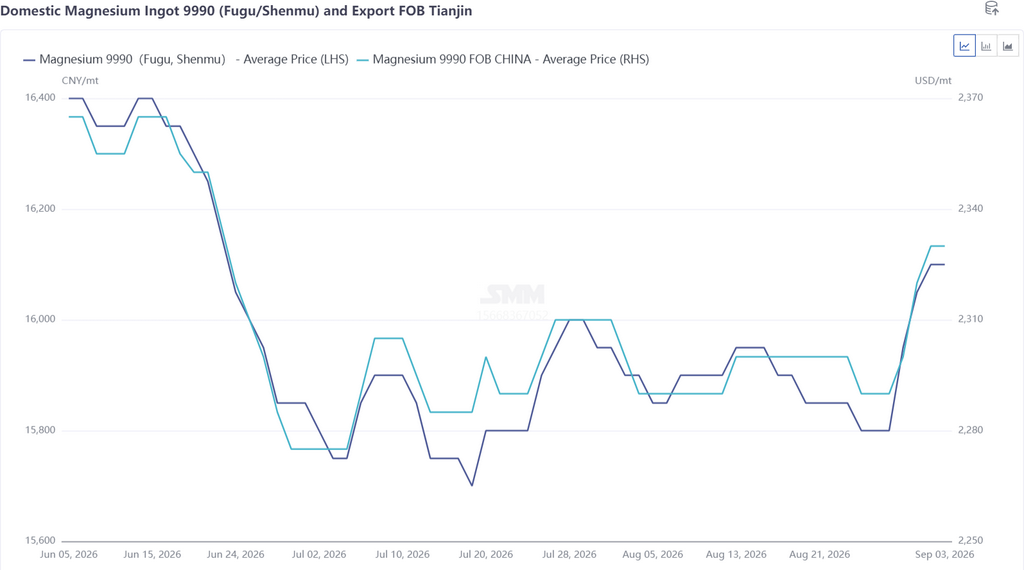
Then came the turning point, quietly but decisively. Coal prices climbed steadily, and semi coke and ferrosilicon followed suit, rapidly driving up primary magnesium smelting costs. Faced with the red line of profitability, magnesium producers collectively held prices firm and raised offers. Within just a few days, magnesium prices broke through the RMB 15,900 and RMB 16,000 per ton thresholds in succession, surging above RMB 16,100 per ton. This rally not only reversed the downtrend since early August but also drew a close to the two-month bottom consolidation from July through August. The previous range-bound pattern was shattered, and the magnesium market officially entered a new price trading range.
| SMM Hongliulin Lump Coal Auction Price Tracker | ||||||||
| Period: Jul 9, 2026 — Sep 3, 2026 | ||||||||
| Date | Starting Price (RMB/ton) |
WoW Change | Auction Volume (10k tons) |
WoW Change | Avg Transaction Price (RMB/ton) |
WoW Change | Lowest Price (RMB/ton) |
Highest Price (RMB/ton) |
| Jul 9 | 710 | ↓10 | 9.4 | ↑0.5 | 723.83 | ↓1.92 | 715 | 731 |
| Aug 5 | 750 | ↑10 | 13.1 | ↑2.7 | 763.47 | ↑8.85 | 758 | 769 |
| Aug 13 | 765 | ↑15 | 9.4 | ↓3.7 | 784.59 | ↑21.12 | 779 | 791 |
| Aug 20 | 780 | ↑15 | 9.1 | ↓0.3 | 815.18 | ↑30.59 | 811 | 823 |
| Aug 27 | 800 | ↑20 | 7.75 | ↓1.35 | 896 | ↑80.82 | 894 | 902 |
| Sep 3 | 990 | ↑190 | 8.1 | ↑0.45 | 1184 | ↑288.00 | 1184 | 1184 |
| ■ Up (Red, Bold) ■ Down (Gray) | ||||||||
| Cumulative Avg Price Increase: RMB 461/ton (723.83 → 1184.00) | ||||||||
The relentless climb in coal prices is now rapidly transmitting along the industrial chain to the primary magnesium smelting sector. The average transaction price of Hongliulin lump coal surged from RMB 723 per ton to RMB 1,184 per ton, a cumulative increase of RMB 461 per ton. As coal rose, semi coke prices followed higher—though this offset a portion of energy cost pressure, ferrosilicon prices also climbed in tandem, driven by coal's upward momentum. The average price of 75# ferrosilicon rose from RMB 5,950 per ton to RMB 6,150 per ton, up RMB 200 per ton. Pushed higher by both energy costs and auxiliary material costs such as ferrosilicon, the production costs of primary magnesium smelters have risen sharply, significantly increasing operational pressure. Within one week of the news of coal's dramatic surge, a total of seven primary magnesium producers have already been affected or have planned production cuts, and the impact is expected to persist.
In August, domestic primary magnesium output rose 3.28% month-on-month, showing a clear upward trend overall. The main driver was the concentrated resumption of production among Shaanxi smelters following their July maintenance. Although Xinjiang and other provinces also saw new maintenance shutdowns, the overall output increase outweighed the decrease, pushing national primary magnesium production higher. By province, Shaanxi's primary magnesium output increased by more than 7,000 tons, yet the national increment was only about 3,000 tons—mainly because maintenance-related production cuts in Xinjiang and other provinces offset most of the gain.
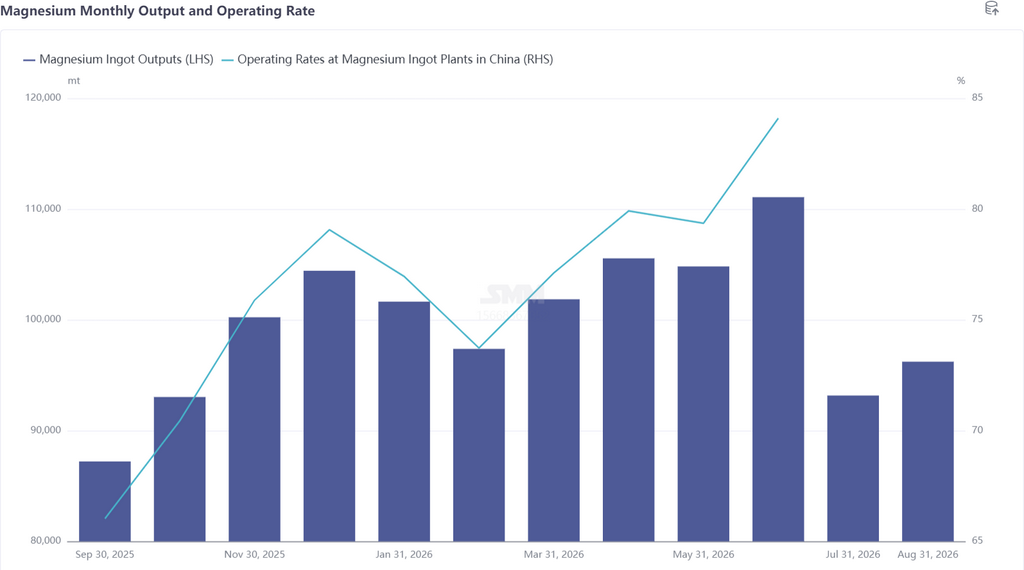
Affected by rising raw material prices of coal and ferrosilicon, the number of primary magnesium producers conducting maintenance in September has increased. A total of 11 producers have seen their output affected in September. Nevertheless, primary magnesium output in September is still expected to rise 2.81% month-on-month versus August, an increment of more than 2,000 tons.
In summary, while this round of coal price increases has pushed up primary magnesium offer prices, it has not translated into profit margins for smelters. Under high-supply and demand-weak pattern,magnesium prices face strong headwinds to the upside, and producers struggle to fully pass through cost increases via price hikes—loss pressure has instead intensified. Rising coal prices are acting as an accelerator for resetting the magnesium supply-demand balance: amid sharply mounting survival pressure, some primary magnesium producers may cut or even halt production in the near term, and the magnesium market is expected to enter a destocking phase. However, it should be noted that on-site inventories and social stocks combined remain conservatively estimated at over 120,000 tons, and destocking will take time. Only after inventories are digested to a reasonable range can the magnesium market truly usher in the next wave of upside.