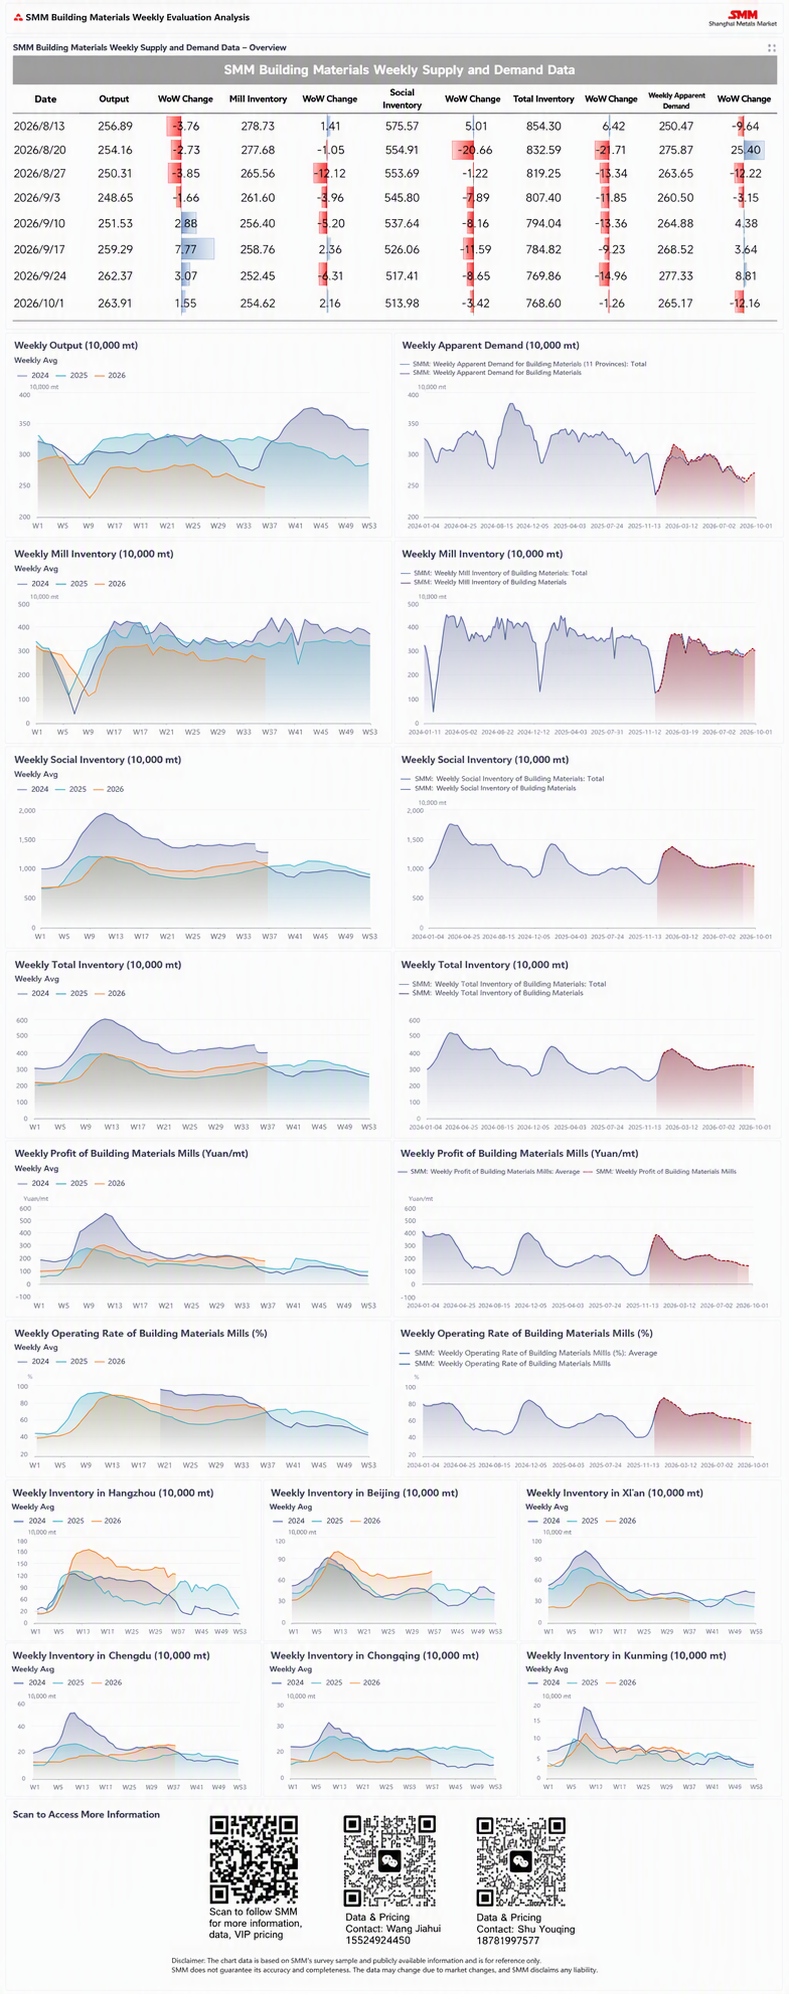
Supply side, long-process and short-process production diverged this period. As the third round of coke price increases took effect, cost pressure at blast furnace mills intensified further, with per-mt steel profit falling below the break-even line and production enthusiasm weakening. In contrast, as reserved steel scrap prices were low, real-time profit continued to recover after finished steel prices rose, prompting some electric furnace mills to raise operating hours or resume production. Demand side, building materials prices fluctuated sharply this period, boosting speculative demand, but rigid demand release remained constrained by typhoons and heavy rain in south China, limiting end-user procurement volumes and causing apparent demand to decline further MoM. According to SMM statistics, building materials inventories at mills and social inventories both destocked to varying degrees this period. Total building materials inventory stood at 8.074 million mt, down 118,500 mt MoM, or -1.45% MoM.