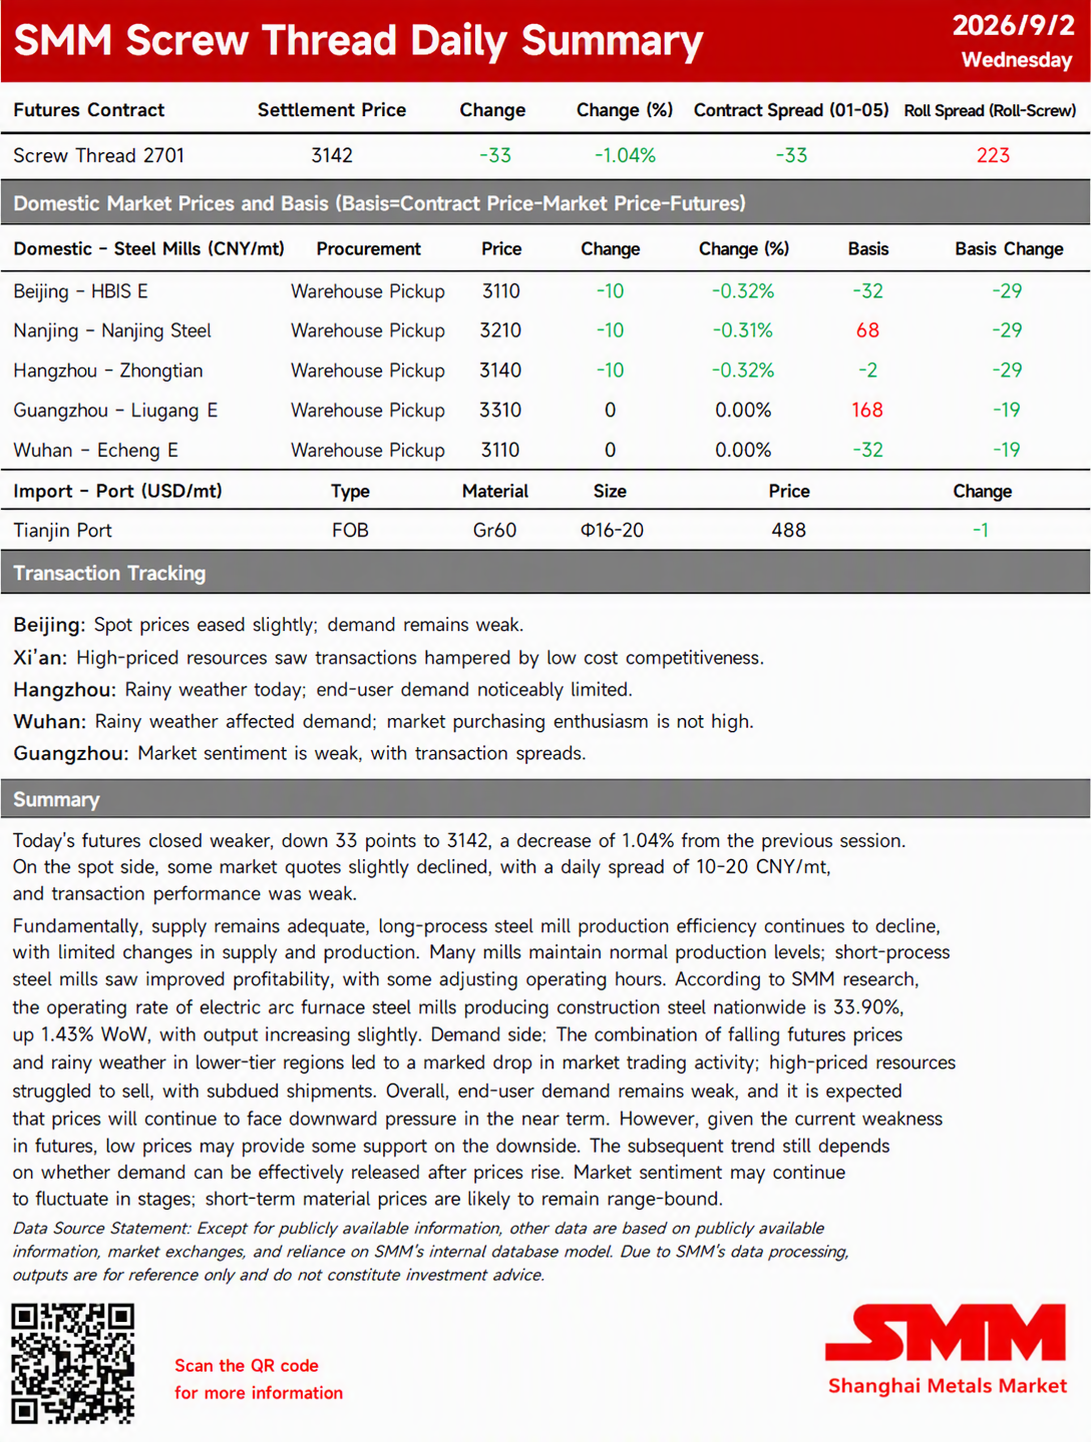
Futures were in the doldrums today, closing at 3,142, down 1.04% from the previous trading day. In the spot market, some regional quotes followed lower slightly, with full-day declines of 10-20 yuan/mt, and transactions were relatively weak.
Fundamentals side, supply side, blast furnace steel mills continued to incur losses, with little change in production enthusiasm, and most maintained previous production levels. EAF steel mills saw improved per-mt margins, and some raised operating hours. According to an SMM survey, the operating rate of 50 electric furnace steel mills nationwide that mainly produce construction materials stood at 33.90%, up 1.43% WoW, with supply edging up slightly. Demand side, the decline in futures, coupled with rainfall in some regions, significantly dampened market trading activity. High-priced resources generally saw sluggish transactions, and full-day shipments were subdued. Overall, actual market demand fell short of expectations, and with weakening sentiment, bottom-side price support shifted lower. However, considering that the tight coking coal supply issue has not been effectively resolved, news may still periodically boost market sentiment. Short-term construction material prices are expected to still have upside potential after a period of pullback.