SMM, September 2:
In the metals market:
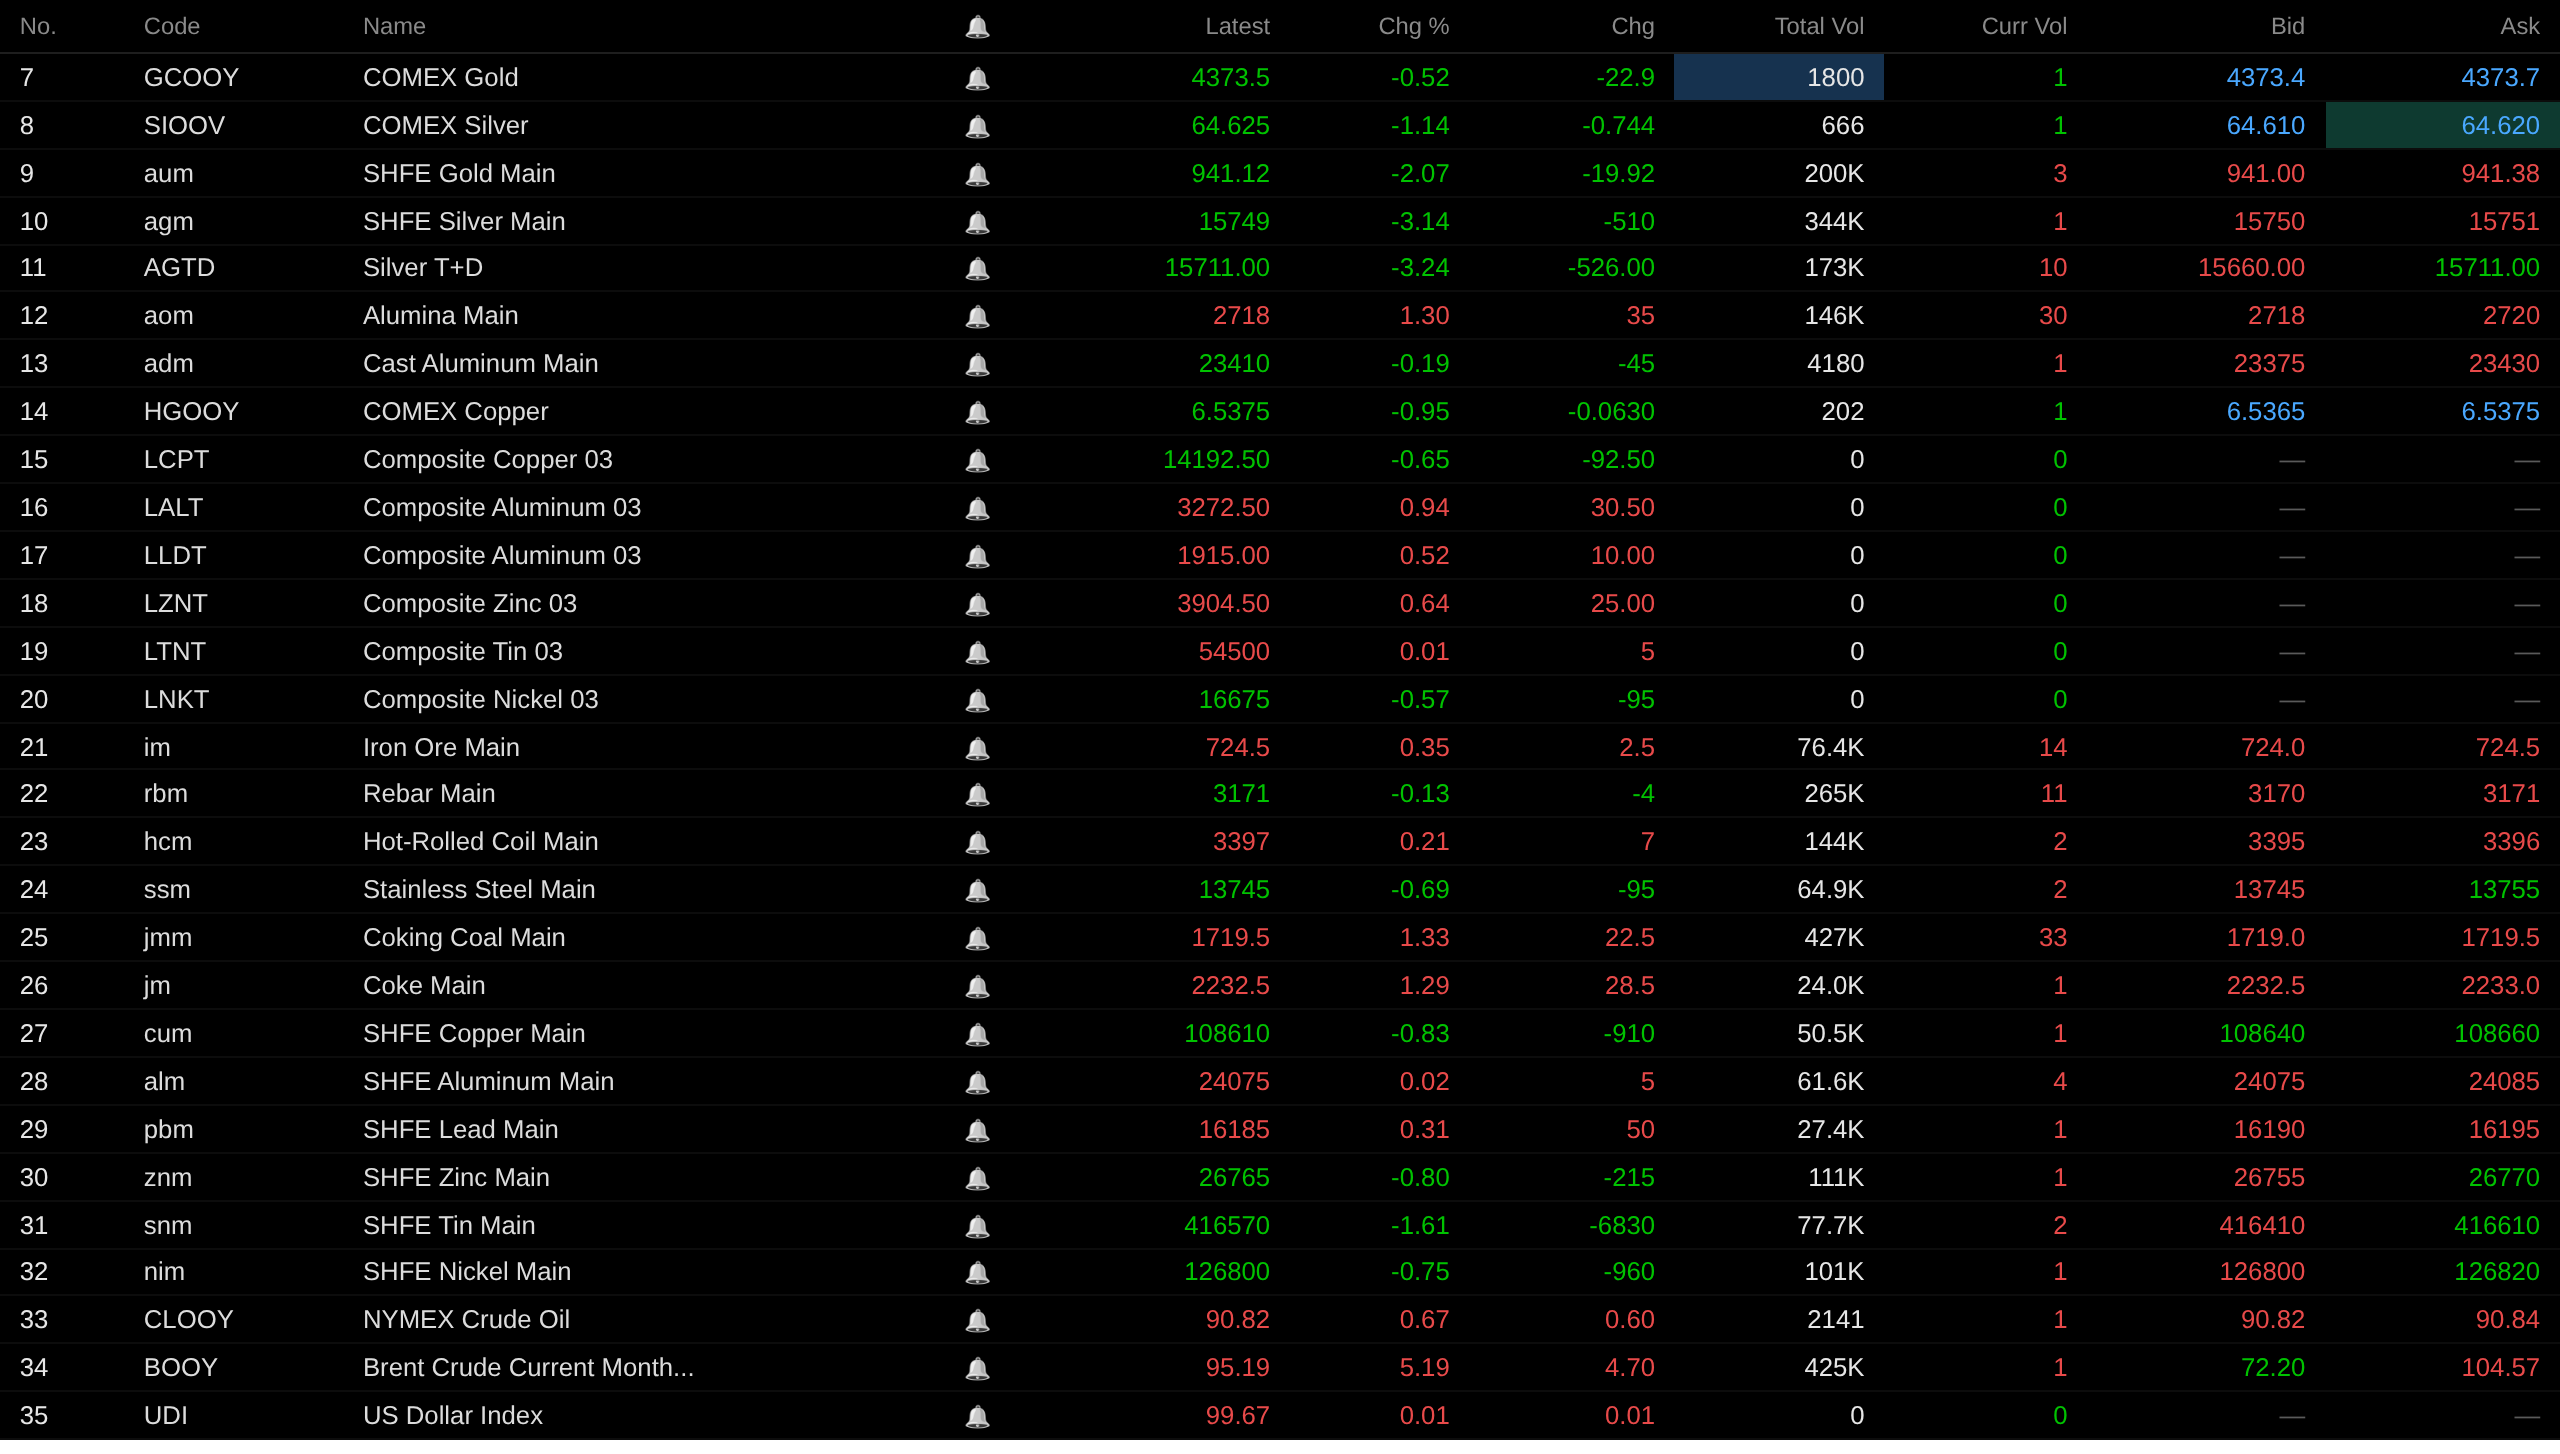
Overnight, base metals on the domestic market mostly fell. SHFE copper fell 0.83%, SHFE aluminum rose 0.02%, and SHFE lead rose 0.31%. SHFE zinc fell 0.8%, and SHFE tin fell 1.61%. SHFE nickel fell 0.75%. In addition, the most-traded alumina futures rose 1.3%, while the most-traded cast aluminum contract fell 0.19%.
Overnight, ferrous metals mostly rose. Stainless steel fell 0.69%. Iron ore rose 0.35%, rebar fell 0.13%, and hot-rolled coil rose 0.21%. For coking coal and coke: the most-traded coking coal contract rose 1.33%, and the most-traded coke contract rose 1.29%.
Overnight on the overseas market, LME base metals mostly rose. LME copper fell 0.65%, and LME aluminum rose 0.94%. LME lead rose 0.52%. LME zinc rose 0.64%. LME tin rose 0.01%. LME nickel fell 0.57%.
Overnight in precious metals : COMEX gold fell 2.36% to settle at $4,375.7/oz; COMEX silver fell 3.48%. Overnight, the most-traded SHFE gold contract fell 2.07%, and the most-traded SHFE silver contract fell 3.14%.
As of 7:12 on September 2, overnight closing prices:
Macro front
Domestically:
[The Ministry of Commerce and other departments issued the Guidelines for Overseas Competition Conduct and Compliance Development in the Automotive Industry] Automotive enterprises shall follow the basic principles of lawful compliance, fair competition, and mutual benefit in their overseas production and operations, strictly abide by China's relevant laws, regulations, and policies on outbound investment, foreign economic cooperation, and foreign trade, and actively implement the Guidelines for Fulfilling Social Responsibilities Overseas, the Guidelines for Integrity and Compliance Overseas, and the Guidelines for Antitrust Compliance Overseas. When setting suggested retail prices for complete vehicles in overseas markets, enterprises shall establish clear price gradients for different vehicle configurations in accordance with the laws and regulations of the host country (region), market principles, and business practices, so as to avoid harming the interests of overseas consumers and brand image through frequent and large price fluctuations. (Xinhua News Agency)
[Two departments: Starting September 1, dividend income of foreign individuals will no longer be exempt from individual income tax] The Ministry of Finance and the State Taxation Administration jointly issued an announcement today (the 1st), stating that starting September 1, dividend income received by foreign individuals from foreign-invested enterprises will no longer be exempt from individual income tax. After the policy adjustment, according to China's Individual Income Tax Law, dividend income received by foreign individuals from foreign-invested enterprises shall be subject to individual income tax under the item of "interest, dividends, and bonus income," at a rate of 20%. Experts noted that major Western countries tax their residents on worldwide income. When foreign individual shareholders receive dividends from foreign-invested enterprises in China, even if they enjoy a tax exemption in China, they still need to pay the corresponding tax to their home countries. After the removal of this exemption policy, the individual income tax paid by foreign individuals in China can be credited against the tax they owe to their home countries, so their actual tax burden will not increase. (CCTV)
[CPCA's Cui Dongshu: World auto sales reached 56.11 million units in January-July] Cui Dongshu, Secretary General of the CPCA, wrote that world auto sales reached 56.11 million units in January-July 2026, with NEVs reaching 13.52 million units. The NEV share reached 24.1% in January-July 2026, with pure EVs accounting for 16.8% and plug-in hybrids accounting for 7.3% of the auto market. Hybrids performed well at 8.1%. (From Wallstreetcn APP)
On the US dollar front:
The overnight US dollar index rose 0.24% to 99.66. Fed Governor Michael Barr said the Fed should be prepared to raise rates if inflation fails to pull back. He warned that inflation has exceeded the target for more than five years, and there is a risk that price pressures have become entrenched. Barr said policymakers can be patient if upcoming data show inflation is cooling. In the text of a speech at an event in Washington on Tuesday, Barr said: "If the trend in the data gives me confidence that inflation is moderating toward the 2% target, then I think we can take some more time to assess the stance of policy. But if inflation does not appear to be cooling by enough, then I think we should act decisively and raise rates." (Jin10 Data)
On the US data front: The US ISM manufacturing index for August was 54.6, below expectations of 55.2 and the prior reading of 55.6, but the prices paid index held at 71.1, with cost pressures not fading. July JOLTS job openings were 7.271 million, below the expected 7.3 million. July construction spending fell 0.5%. The short end rose faster than the long end, and the yield curve moved in a bear flattening pattern. The options market is already positioning for rates to continue rising. Nomura cross-asset strategist Charlie McElligott said hedgers have been aggressively buying options with high strike prices that bet on rates moving higher, and volatility of volatility has risen to extreme levels. (Wallstreetcn)
According to CME "FedWatch": The probability that the Fed will keep rates unchanged by September is 33.1%, and the probability of a cumulative 25 basis point hike is 66.9%. The probability of the US Fed keeping rates unchanged through October is 22.5%, the probability of a cumulative 25 bp hike is 56.0%, and the probability of a cumulative 50 bp hike is 21.5%. (Jin10 Data)
On the macro front:
Data due today include Australia's Q2 GDP annual rate, the Reserve Bank of New Zealand's rate decision through September 2, US August ADP employment change, the Bank of Canada's rate decision through September 2, and US July factory orders monthly rate. Also in focus: the RBNZ will release its rate decision and monetary policy statement; the Bank of Canada will release its rate decision; BOC Governor Macklem and Senior Deputy Governor Rogers will hold a monetary policy press conference.
On the crude oil front:
Both oil futures rose overnight, with WTI up 5.74% and Brent up 5.19%. Escalating US-Iran tensions sent oil prices jumping.
The refined products market is even tighter than crude. The price spread between US heating oil futures and crude surged above $106 per barrel, a record high, while retail diesel prices approached $5.63 per gallon. Wholesale-side shortages will pass down layer by layer, with freight and logistics first to receive the bill. (Wall Street Journal)
Ole Hansen, senior commodity strategist at Saxo Bank, said the strike raises concerns about a prolonged disruption to energy flows through the Strait of Hormuz. Rich Privorotsky, head of first-order derivatives trading at Goldman Sachs, said diesel is the center of this rally, with global refined product wholesale prices up $40 per barrel since February, and diesel accounting for more than 40% of that increase. (Wall Street Journal)