Key points: Qinghai Weixiang has filed a project for 3,000 t/y lithium sulfide, crossing over into the upstream solid-state battery space. Leveraging its technical homology in lithium reagents, the company adopts a high-temperature low-pressure process developed with the Qinghai Institute of Salt Lakes, CAS, achieving 99.9% purity. Current average lithium sulfide price is around RMB 1.5 million/ton, accounting for 88% of the BOM cost of sulfide electrolytes. Weixiang's planned capacity far exceeds the hundred-tonne pilot scales of most players, but mass-production validation will still take 1–2 years. In the short term, its strategic positioning is more about early-mover advantage than actual supply impact.
On August 10, 2026, a project filing on the Qinghai Provincial Investment Project Online Approval and Supervision Platform brought Qinghai Weixiang Technology Co., Ltd. – a lithium reagent company not previously prominent in the lithium battery circle – into the spotlight of solid‑state battery upstream materials competition. The company's 3,000 t/y lithium sulfide project has officially completed filing, with a total investment of RMB 81.319 million, to be located in the Golmud Kunlun Economic Development Zone, and built in two phases (Phase I: 500 t/y, Phase II: 2,500 t/y), with compatibility to produce 10,000 t/y of lithium sulfate, and is scheduled to be put into operation in July 2027.
I. From Lithium Reagents to Lithium Sulfide: A "Natural" Cross-Border Move
Qinghai Weixiang is no newcomer to the lithium battery materials sector. The company was established in November 2019 and relocated from Jiangsu to Golmud, Qinghai in 2021, leveraging the local salt‑lake lithium resources. Its main business includes R&D and production of alkyl lithium, Grignard reagents, lithium carbonate, and other products. Its 3,100 t/y alkyl lithium series products and supporting new materials construction project is a key ongoing project in the park, with a total investment of RMB 173 million.
In June 2026, the company's general manager, Huang Lei, revealed in an interview that Weixiang Technology "is currently working on solid‑state battery pilot projects" and has established cooperation with East China Normal University, the Salt Lake Research Institute, and other academic institutions. The logic for Weixiang's move from lithium reagents to lithium sulfide is not hard to understand – products such as alkyl lithium and butyl lithium are themselves highly reactive lithium compounds, and their synthesis and purification processes share technical homology with lithium sulfide. The company already has processing capabilities for basic lithium salts like lithium carbonate and lithium chloride, so extending to lithium sulfide is a natural industrial chain extension.
II. Technical Route: Can the High‑Temperature Low‑Pressure Method Break the Scale‑Up Bottleneck?
The biggest pain point for large‑scale production of lithium sulfide lies in the process. Traditional processes suffer from high reaction risks, difficult purification, and difficulty in scaling up. Weixiang Technology's core asset is the "high‑temperature low‑pressure preparation of high‑purity lithium sulfide" technology jointly developed with the Qinghai Institute of Salt Lakes, Chinese Academy of Sciences. This technology applied for and received a national invention patent in January 2026 (application No. 202610015644.0).
According to public information, this process uses staged temperature control under high vacuum, combined with a ball‑milling secondary reaction process, which not only reduces the explosion and impact risks during the lithium‑sulfur reaction but also improves product purity to the 99.9% level. In addition, the relevant technical scheme also involves an electronic‑grade lithium sulfide preparation method, which directly reduces lithium sulfate with hydrogen gas, producing no waste gas or wastewater. Note that many companies are switching from ball‑milling to jet‑milling processes.
From a technical specification perspective, 99.9% purity already meets the threshold requirement for lithium sulfide used in sulfide solid‑state electrolytes (industry group standards clearly require lithium sulfide purity ≥99.9%). However, it should be noted that moving from patented technology to thousand‑tonne industrial scale‑up still faces multiple hurdles, including pilot validation, process scale‑up, and cost control. Phase I capacity of 500 t/y is expected to be completed by July 2027, which is not an aggressive timeline.
III. Supply Landscape: Scarcity and Strategic Value of Thousand‑Tonne Capacity
Currently, domestic high‑purity lithium sulfide is still largely in pilot or small‑scale shipment stages, with most companies stuck at hundred‑tonne pilot lines, making large‑scale production capacity extremely scarce. Below is a summary of capacity plans from some listed players, though some are still at the PPT stage:
-
Gotion High‑tech: 300 t/y lithium sulfide capacity to be landed in 2026, expanding to 20,000 t/y in 2027, and reaching 50,000 t/y by 2030; Gotion Holding launched a 20,000 t/y solid‑state battery key materials project in July 2026, the industry's first 10,000‑tonne‑scale high‑purity lithium sulfide production line.
-
Tinci Materials: A hundred‑tonne‑scale pilot line for lithium sulfide and solid‑state electrolytes has been completed, and trial production is expected to begin in Q3 2026.
-
Guanghua Technology: Lithium sulfide capacity of 300 t/y, with mass‑production capability already in place.
-
Enjie Co., Ltd.: A high‑purity lithium sulfide pilot line has been set up.
-
Tianqi Lithium: Has completed process and equipment development for lithium sulfide industrialisation.
-
Yahua Group: Successfully developed a new gas‑solid method for synthesising lithium sulfide.
Among the above players, Weixiang Technology's planned 3,000 tonnes – while smaller than Gotion's 10,000‑tonne scale – is significantly larger than the hundred‑tonne pilot scales of Tinci and Guanghua, giving it a certain scarcity in domestic lithium sulfide supply. Once fully built, the project could meet the raw material needs of many solid‑state battery companies for sample delivery and pilot‑line trials.
IV. Cost Logic: Supply‑Demand Dynamics and Market Demand for Cost Reduction
4.1 Current Price Situation
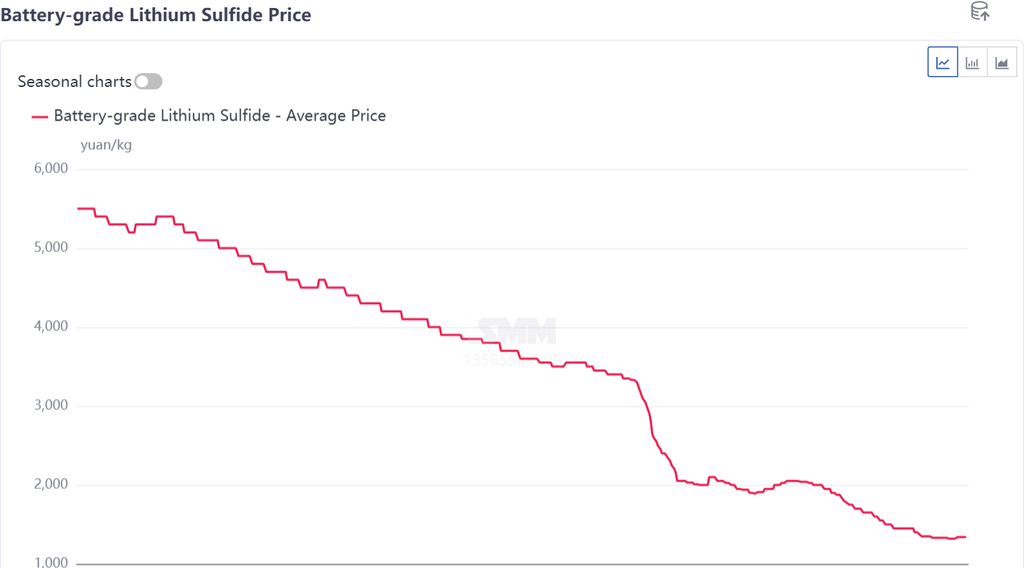
The price of lithium sulfide has been on a downward trend; except for Youyan Xiba, which remains at a high level, other companies' prices are around RMB 1.5 million/ton. Even at this price, lithium sulfide accounts for over 80% of the material cost of sulfide electrolytes. Based on tonne‑level prices of RMB 1.5 million for lithium sulfide, RMB 300,000 for lithium chloride, and RMB 70,000 for phosphorus pentasulfide, lithium sulfide accounts for 88% of the BOM cost. According to SMM estimates, 1 GWh of sulfide all‑solid‑state battery requires about 700 tonnes of electrolyte, and each tonne of electrolyte needs about 400 kg of lithium sulfide.
4.2 Current Production Situation
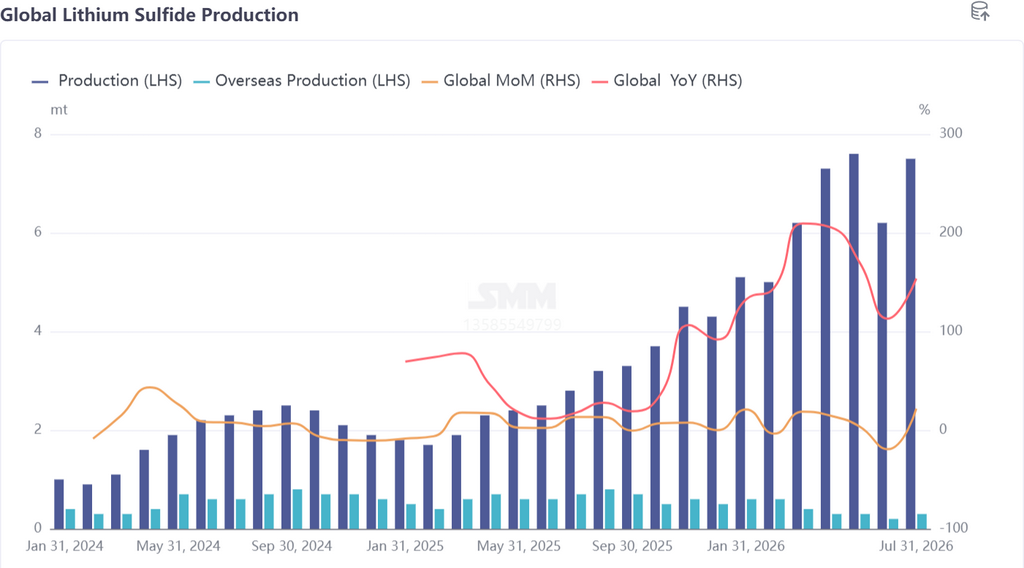
If Weixiang Technology's 3,000 tonnes of capacity is smoothly released, the scale effect is expected to drive down the cost of high‑purity lithium sulfide. However, it must also be noted that the high cost of lithium sulfide is fundamentally due to complex processes, the need for expensive metallic lithium, and extremely high environmental requirements for production and transportation. Capacity expansion alone may not solve the cost problem; the cost‑reduction potential of the technical route is the key.
SMM believes that Weixiang Technology has its advantages, but capacity release may be delayed by 1‑2 years.
First, the cross‑border advantage of a lithium reagent company. Weixiang's core business – alkyl lithium, butyl lithium, etc. – involves highly reactive and high‑purity lithium compounds that demand strict control over moisture and oxygen. This technical accumulation has natural transfer value to lithium sulfide production. Compared with cross‑border entrants starting from scratch, they need time for technical maturation.
Second, the timing. 2026 is a critical turning point as solid‑state batteries move from R&D to pilot validation. Sulfide all‑solid‑state batteries are seen by the industry as the mainstream technical direction. CATL's world‑first sulfide all‑solid‑state battery pilot line has already started production in Hefei, and EVE Energy has completed Ah‑level pouch cell sample development. Weixiang Technology has chosen to enter at this node, aligning with the pace of industrialisation. However, product sampling and validation are more complex than for other lithium‑battery materials.
In the short term, the strategic significance of Weixiang Technology's lithium sulfide project lies in early positioning. In the medium to long term, the capacity release schedule depends on the progress of sulfide solid‑state battery projects.
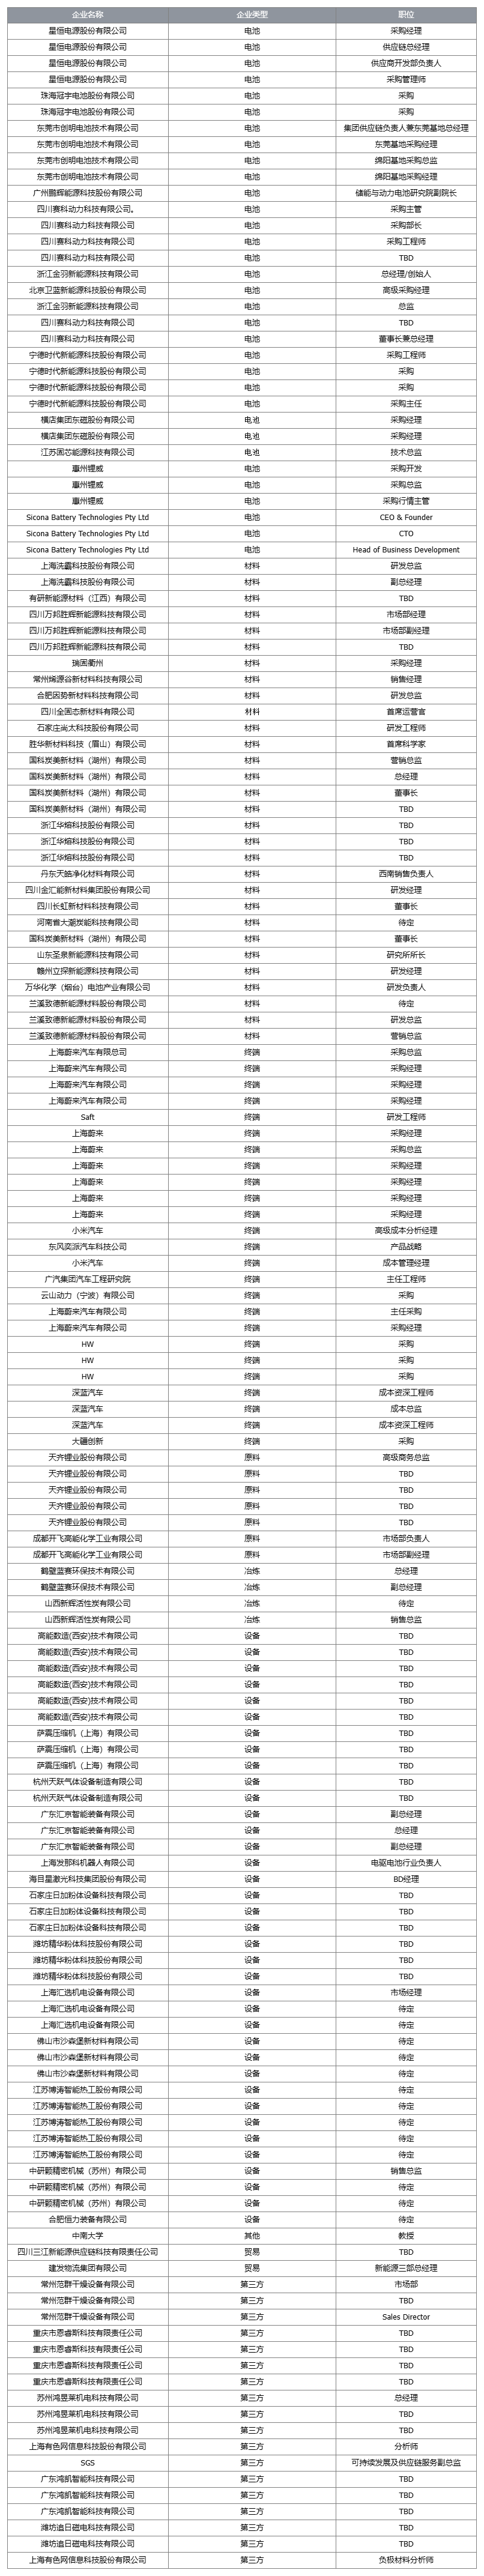
最后推荐一下SMM的精品会议,目前进展和部分参会企业及代表:
**Note:** For further details or inquiries regarding solid-state battery development, please contact:
Phone: 021-20707860 (or WeChat: 13585549799)
Contact: Chaoxing Yang. Thank you!