South Africa's chrome ore exports totalled 2,403.95kt in June 2026, easing a marginal 0.90% month-on-month but still standing 38.86% higher than a year earlier — the latest data point in a trend that has defined the country's chromium sector for well over a year: raw ore volumes holding firm or growing, even as the health of domestic ferrochrome smelting remains under separate and distinct pressure.
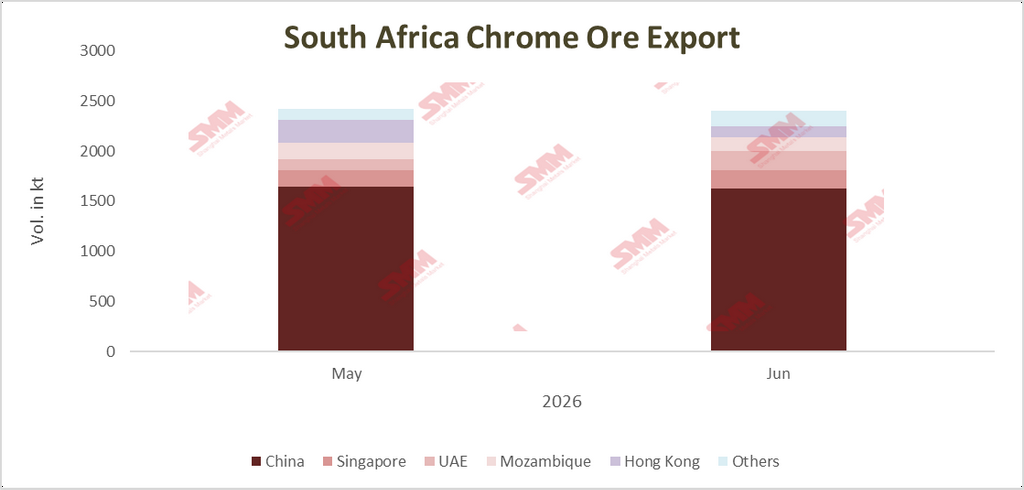
Figure 1: South Africa chrome ore export volume and destination breakdown, June 2026
A Moderating, but Still Elevated, Trend
June's figure sits within a narrow band that has now persisted for three consecutive months. Exports measured 2.47 million tonnes in April and 2.43 million tonnes in May, before easing further to 2.404 million tonnes in June — a gentle, incremental decline of roughly 2.7% across the quarter. Read in isolation, that could look like softening demand. Read against the year-on-year comparison, it looks more like a plateau at an unusually high level: April, May and June 2026 volumes have all come in well above 2025's equivalent months, with year-on-year growth running as high as 43% in May and still near 39% in June. In other words, the market has not cooled — it has simply stopped accelerating after an extended period of outsized growth.
China's Grip on the Trade Tightens Further
China absorbed 67.61% of South Africa's total June export volume, reaffirming its position as by far the largest buyer of South African chrome ore. That concentration is consistent with — and arguably an intensification of — the pattern seen through 2025, when China absorbed a record 12.5 million tonnes of South African chrome ore across the full year, up 23.8% year-on-year, driven by high operating rates at Chinese ferrochrome smelters feeding the country's stainless steel industry. With Chinese buyers taking more than two-thirds of a single month's exports, South Africa's chrome ore trade is now more dependent than ever on the health of one downstream market: Chinese ferrochrome production and, by extension, Chinese stainless steel demand. That concentration cuts both ways — it has underpinned South Africa's export volumes through a period of domestic smelting weakness, but it also leaves the country's ore exporters unusually exposed to any slowdown in Chinese furnace utilisation or stainless steel output.
Singapore and the UAE: Trading Gateways, Not End-Use Markets
Singapore (7.85%) and the UAE (7.82%) rounded out the top three destinations in June, together accounting for close to a sixth of total export volume. Neither country is a meaningful chrome ore consumer or ferrochrome producer in its own right; both are established global commodity trading and logistics hubs. The UAE in particular is widely positioned — including in the government's own economic development literature — as a re-export and re-distribution gateway to the wider Middle East and African markets, leveraging its logistics infrastructure rather than domestic industrial demand. Singapore plays a broadly similar role in Asian commodity trading flows. Their appearance in the top three is therefore best read as a signal of trading and blending activity — ore passing through intermediary hubs before final delivery — rather than genuine new demand centres competing with China for South African tonnage.
The Structural Story Underneath the Numbers
The persistence of strong ore exports alongside continued weakness in South Africa's own ferrochrome smelting capacity reflects a structural realignment in the country's chromium value chain rather than a short-term fluctuation. High grid electricity costs, an ageing domestic furnace fleet, and persistent logistics bottlenecks have steadily eroded the competitiveness of local beneficiation, encouraging producers to route an increasing share of mined chrome toward raw-ore export instead. That dynamic was starkly illustrated at the company level in Merafe Resources' H1 2026 production report, released in late July, which showed attributable ferrochrome production collapsing 75% to just 28,000 tonnes on extended smelter suspensions at Wonderkop and Boshoek, while chrome ore production held almost steady at 425,000 tonnes — the ore side of the business continuing to perform even as the alloy side went largely idle.
At the same time, South Africa's supply base for chrome ore is arguably broadening rather than narrowing, even as dedicated ferrochrome capacity struggles. Several major platinum group metals producers — Sibanye-Stillwater, Northam Platinum, Eastplats, and project developer Southern Palladium at its Bengwenyama development — have all disclosed plans or results this year showing deliberate growth in chromite by-product recovery from their UG2 orebodies, treating chrome increasingly as a strategic parallel revenue stream rather than an incidental credit. That PGM-sector diversification adds a further source of tonnage to the ore-export pool, reinforcing the same pattern visible in the national trade data: more ore reaching the market, less of it being converted to ferrochrome domestically before it leaves the country.
A Policy Response Still Working Through the System
This is not an unnoticed trend within South Africa. In June 2025, Cabinet approved a coordinated set of interventions specifically aimed at curbing this shift — including realigning electricity tariffs for the ferrochrome industry, placing chrome ore under export control requiring an ITAC-administered export permit, and developing a chrome ore export tax alongside expanded Special Economic Zone incentives for smelters. The Department of Trade, Industry and Competition subsequently opened the export-tax and permitting framework for public comment in November 2025. More than six months on, June's trade data — still showing raw ore exports running nearly 39% above year-ago levels — suggests that whatever combination of permitting and tariff relief has been implemented so far has not yet meaningfully redirected material away from export and back into domestic beneficiation. Whether the fuller export tax framework, once finalised, changes that balance is likely to be one of the more consequential open questions for South Africa's chrome value chain over the remainder of 2026.
Bottom Line
June's export data confirms that South Africa's chrome ore trade remains structurally tilted toward raw shipments rather than domestic beneficiation, with China's share of that trade deepening rather than diversifying, and Singapore and the UAE functioning as trading conduits rather than genuine alternative markets. With PGM producers adding to the ore supply base even as ferrochrome smelters remain constrained, and government's export-control measures still working through implementation, the divergence between chrome ore and ferrochrome trade flows looks set to remain a defining feature of South Africa's chromium sector through the rest of 2026.