In July, the sodium-ion battery materials market sustained strong momentum, with both cathode and anode segments showing clear signs of “robust demand, strained capacity.” Orders from downstream battery cell manufacturers continued to surge, particularly as the penetration rate of the polyanion route in energy storage applications accelerated, pushing upstream material enterprises to near-full-capacity operations. Hard carbon anodes, meanwhile, faced mounting delivery pressure as capacity utilization rates hit their ceiling. Overall, the sodium-ion battery industry chain is shifting from “small-batch trial shipments” to “large-scale readiness,” with capacity expansion becoming an industry-wide consensus.
Cathode side: NFPP operates at full capacity, new and old players race to expand capacity
In July, China’s sodium-ion battery cathode material production rose 13% MoM and jumped 55% YoY, with polyanion-type materials further increasing their share to 88%, cementing their dominant position. Mainstream NFPP (sodium iron pyrophosphate) enterprises largely shifted to full-capacity production this month, driven primarily by ample orders from downstream top-tier battery cell manufacturers—some clients had already communicated their overall H2 demand plans to suppliers, showing strong willingness to lock in volume and price. Currently, the NFPP market is tight on supply, with major players’ finished product inventories at low levels; this tightness is expected to persist until early Q4.
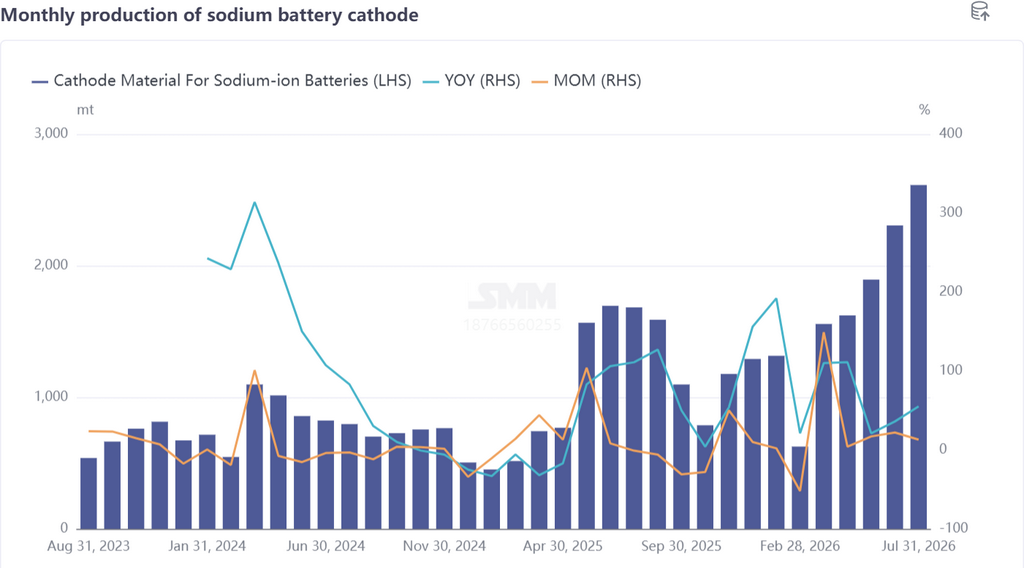
Products that have undergone long-term validation have gained deep recognition from long-established downstream sodium-ion battery clients and now account for the bulk of shipments. Another group consists of traditional lithium battery cathode giants actively entering the sodium-ion battery track; although their products are still in the client validation stage, their deep capital reserves and low reliance on external financing will allow a much faster pace of capacity build-out, positioning them to quickly meet explosive downstream demand. It is worth noting that even though top-tier players clearly intend to expand capacity, only a handful will have genuine large-scale, stable shipment capability in Q3. To date, no single enterprise has achieved a monthly production breakthrough of 1 kt, and the industry as a whole remains in the early stage of “ramp-up.”
The layered oxide cathode market performed relatively mediocre in July, with its main application scenarios still concentrated in high-power, high-C-rate applications, contributing limited near-term growth.
Anode side: Hard carbon capacity utilization rate nearing ceiling, high-end product supply structurally tight
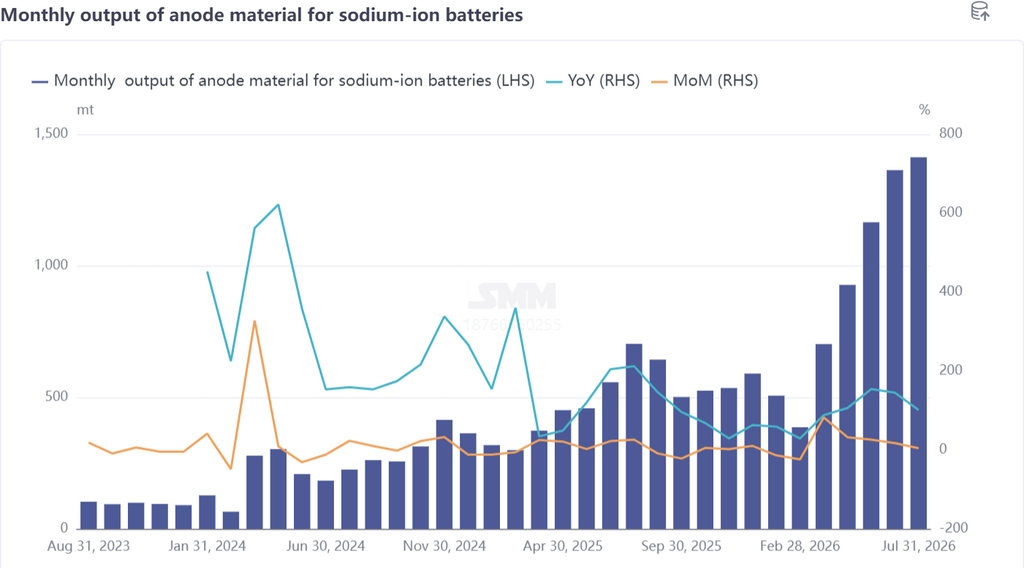
In July, sodium-ion battery hard carbon anode production increased 4% MoM and surged 101% YoY. The narrowing MoM growth was mainly due to mainstream enterprises' utilization rates approaching 100% under existing capacity, with further production increases dependent on substantial new capacity releases. Some enterprises attempted to ease delivery pressure through short-term toll processing, but the quality control of toll-processed products proved challenging, resulting in inconsistent output quality that required secondary processing, which in turn pushed up overall costs and was not a viable long-term solution. Currently, enterprises generally maintain low inventory operations for hard carbon finished products, shipping them immediately after production, which confirms robust demand-side pull.
Raw material side: Hard carbon precursors are diverse in type, and cost changes vary by route, but overall supply remains stable. Looking ahead to H2, significant anode procurement expectations exist downstream, and cooperation between leading battery cell manufacturers and anode enterprises is expected to achieve substantial breakthroughs in H2, potentially driving further market volume expansion. Current market demand for high-end hard carbon products suited to long-cycle application scenarios is particularly robust, while the supply elasticity for this category is weak, making the structural gap difficult to bridge in the short term.
August Outlook: Clear demand growth trajectory, supply bottleneck remains a key variable
Entering August, sodium-ion battery cathode demand is expected to continue strengthening, with clear MoM growth in orders. Some enterprises will continue capacity ramp-up, with August cathode production expected to increase another 11% MoM, expanding YoY growth to 83%. For hard carbon anodes, market volume growth expectations are clear and industry confidence is strong, but the tight supply pattern for high-end products is likely to persist, with August hard carbon production expected to grow 13% MoM and surge 149% YoY.
Overall, the sodium-ion battery industry is in a race between "demand explosion" and "capacity construction." The cathode segment's NFPP has taken the lead in achieving full production benefits, with new and existing players accelerating their market positioning; the anode segment needs to overcome high-end capacity bottlenecks as soon as possible to handle the larger-scale long-term contract demand in H2. SMM believes that the period from late Q3 to early Q4 will be a critical window for sodium-ion battery material capacity release, during which the supply-demand pattern is expected to gradually improve. However, the seller's market characteristics will persist in the short term, and enterprises with first-mover advantages and rapid capacity expansion capabilities will be the first to benefit from this upcycle.