SMM July 30:
Metals Market:
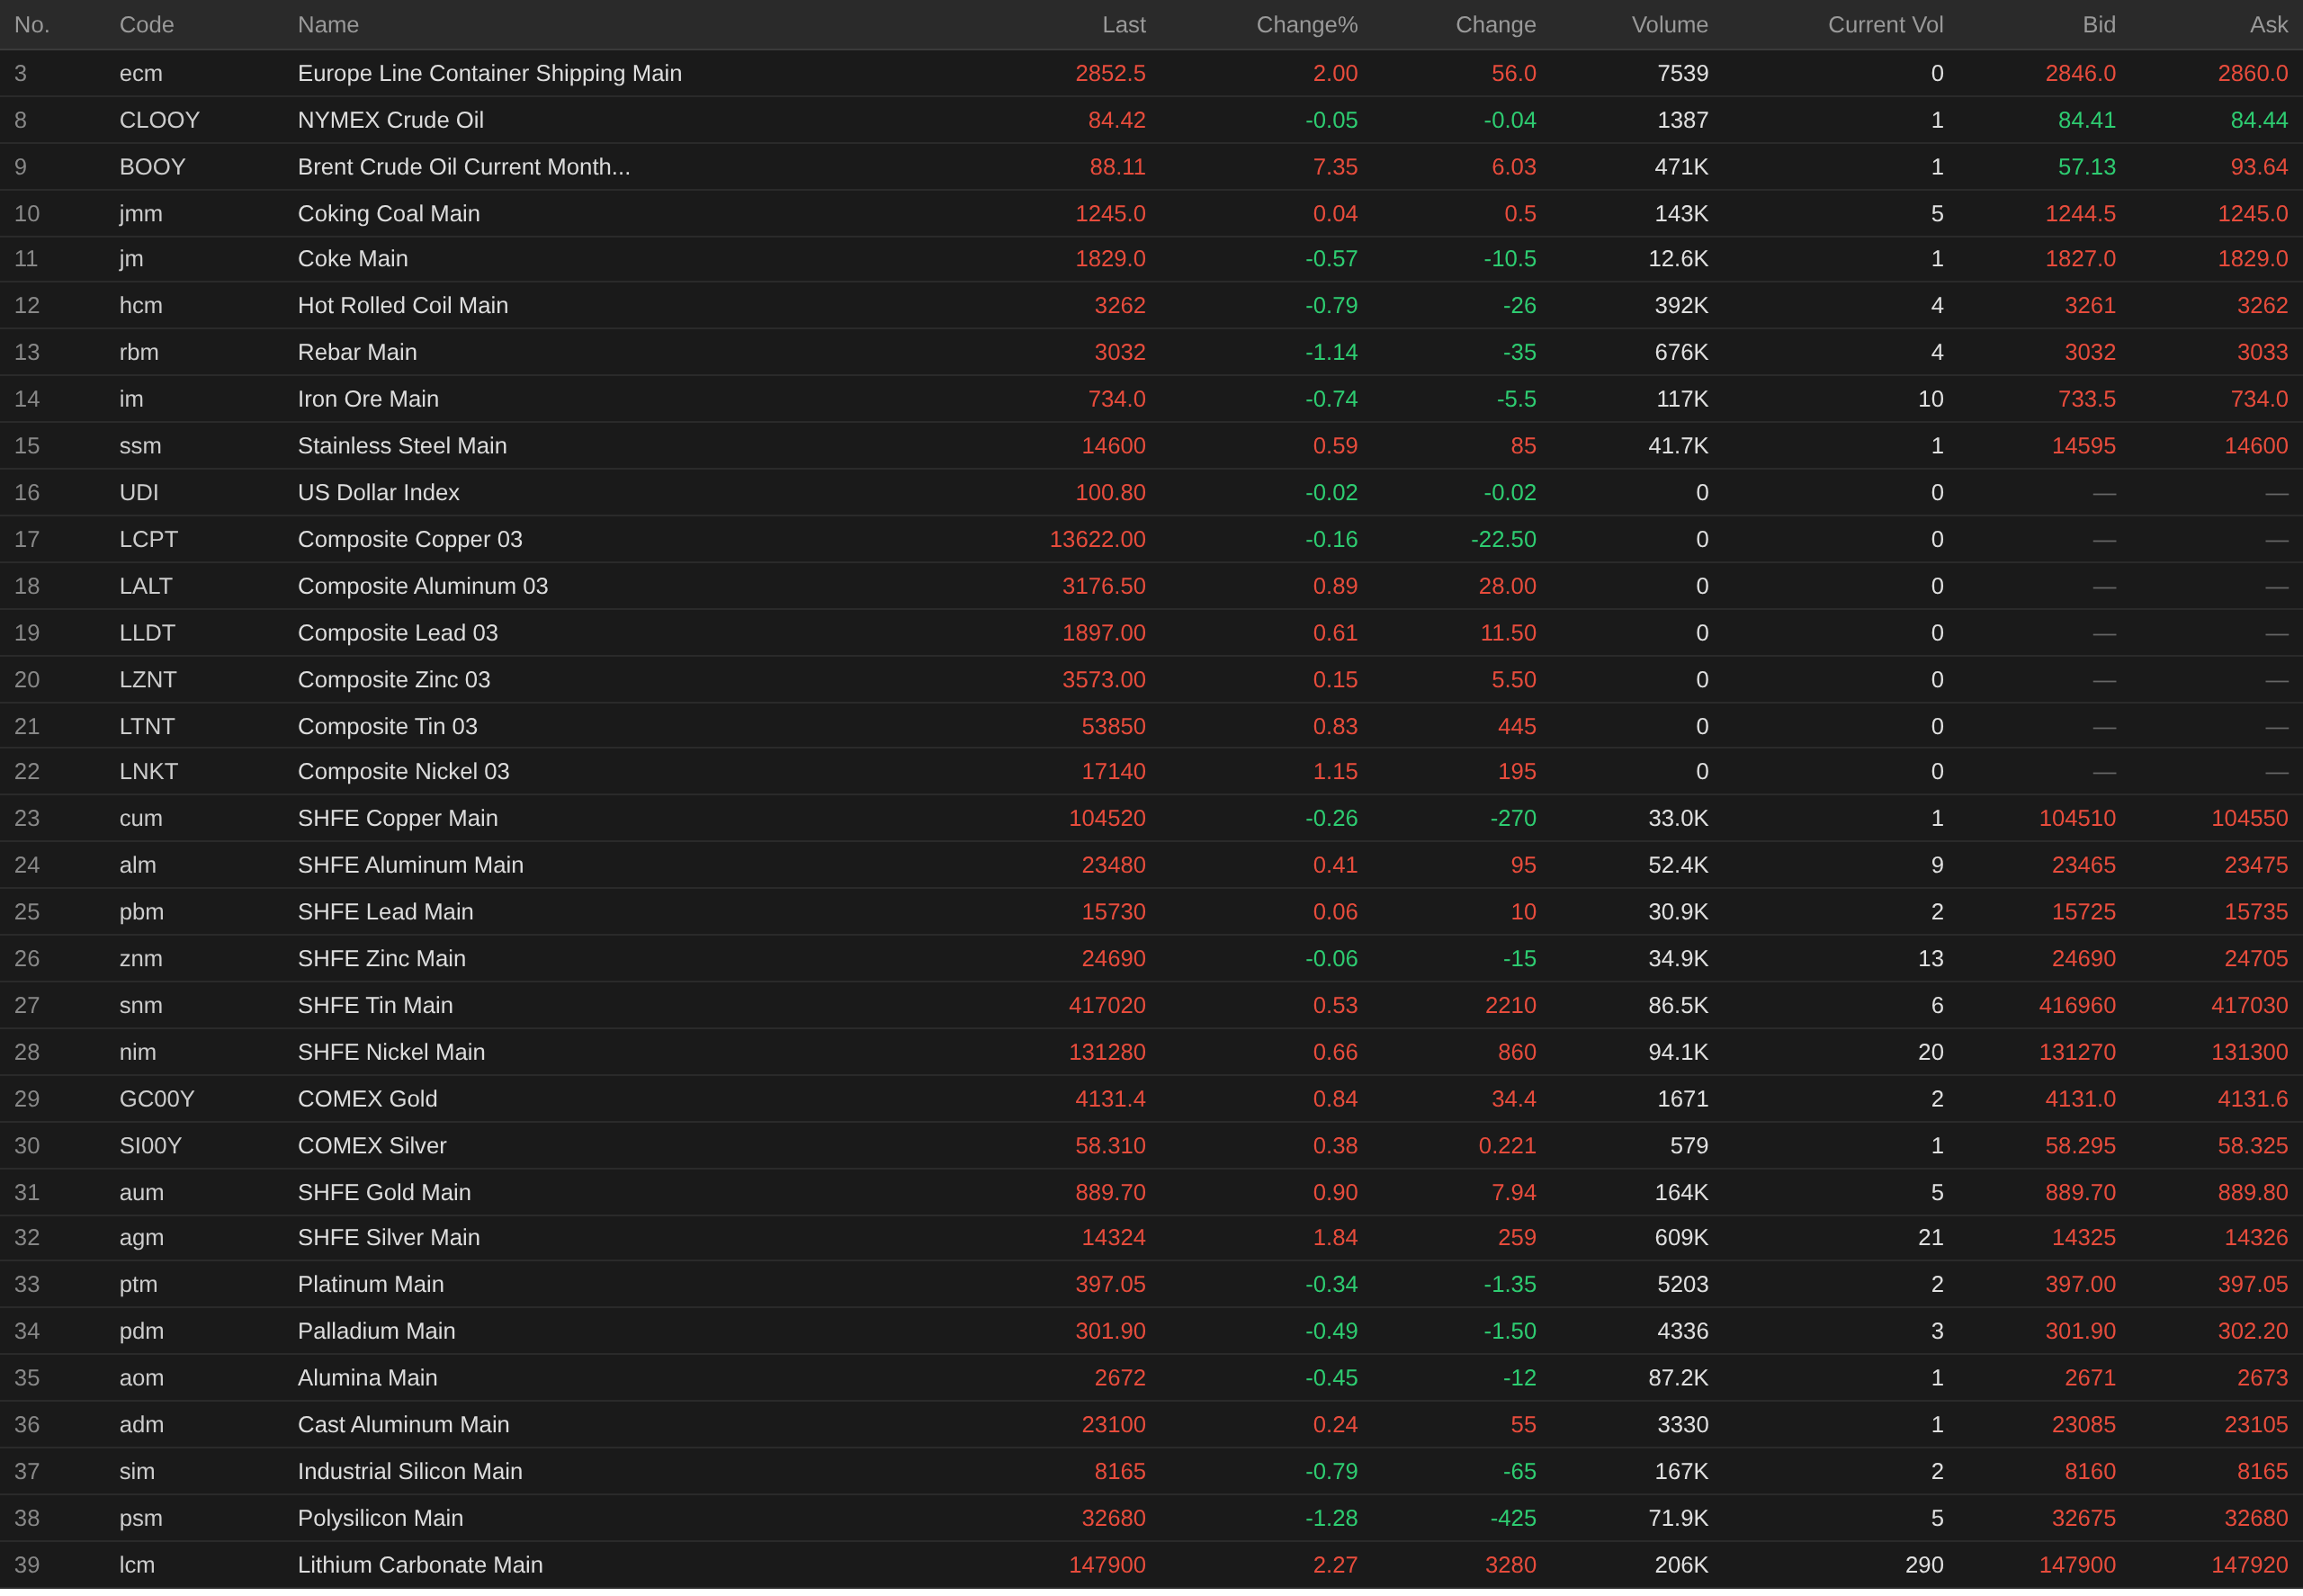
Overnight, base metals on both domestic and overseas markets mostly rose, with only SHFE copper, SHFE zinc, and LME copper falling. SHFE copper fell 0.26%, SHFE zinc fell 0.06%, LME copper fell 0.16%, LME nickel led the gains with a 1.15% rise, and the rest of the metals rose within 1%. Alumina main contract fell 0.45%, and cast aluminum main contract rose 0.24%.
Overnight, ferrous metals mostly fell. Stainless steel rose 0.59%, rebar led the declines with a 1.14% drop, hot-rolled coil and iron ore both fell around 0.7%, with hot-rolled coil down 0.79% and iron ore down 0.74%. For coking coal and coke, coking coal edged up 0.04%, while coke fell 0.57%.
Precious metals: Overnight, COMEX gold rose 0.66% and COMEX silver gained 0.64%. Domestically, SHFE gold rose 0.9% and SHFE silver surged 1.84%.
A Reuters survey showed that after gold prices pulled back sharply from their record high in January, analysts cut their gold price forecasts for the first time since end-2023, though most still expect central bank buying and concerns over fiscal sustainability to provide support. The median forecast for gold prices in 2026 from the survey of 29 analysts and traders over the past three weeks was $4,509 per ounce. That was down from $4,916 three months earlier and marked the first downgrade in 11 quarters. The average forecast for 2027 was $4,610, versus $5,100 in the previous survey. Gold prices hit an all-time high of $5,595/oz in January, then suffered a sharp pullback in Q2 as the Iran war exacerbated energy inflation and pushed up interest rate hike expectations, marking the worst quarterly performance since 2013. Since the geopolitical conflict erupted, spot gold has dropped about 22%. (Jin10 Data APP)
As of 6:42 on July 30, overnight closing prices:
Macro Front
China:
[China’s total social logistics value exceeded 180 trillion yuan in H1] The China Federation of Logistics and Purchasing (CFLP) released logistics operation data for H1 this year yesterday (July 29). In H1, logistics demand continued to expand, marked by structural optimization and momentum shift. China’s total social logistics value reached 181.1 trillion yuan in H1, up 5.1% YoY, outpacing GDP growth by 0.4 percentage points, demonstrating the logistics sector’s enhanced role in supporting and driving national economic growth. By quarter, growth was 6.2% in Q1 and 4.4% in Q2, maintaining a steady yet progressing trend. (CCTV News)
[CO2 emissions per unit of GDP will be reduced by 17% during the 15th Five-Year Plan period] The Ministry of Ecology and Environment, together with the National Development and Reform Commission (NDRC) and 17 other departments, jointly released the National Climate Change Response 15th Five-Year Plan. According to the Plan, by 2030, CO2 emissions per unit of GDP will be reduced by 17% from 2025, and CO2 emissions per unit of product in sectors covered by the national carbon emission trading market will drop by around 3% from 2025. A national voluntary greenhouse gas emission reduction trading market that is credible, transparent, methodologically unified, broadly participatory and aligned with international standards will be established; a product carbon footprint management system will be largely in place; monitoring and control of non-CO2 greenhouse gases will be strengthened, with a reduction capacity of 30 million tonnes of CO2e; the climate adaptation work system will be refined; climate-adaptive society construction will achieve phased progress; and awareness and capabilities in tackling climate change will continue to improve. China’s influence, guidance, shaping power and moral appeal in global climate governance will significantly increase. (from Wall Street CN APP)
US Dollar:
As of the overnight close, the US dollar index fell 0.59% to 100.82. The US Fed held rates at 3.50%-3.75% for the fifth consecutive meeting, with a 9-3 vote, as three regional Fed bank presidents voted for a rate hike. Fed Chairman Warsh said the Fed’s reduced forward guidance on policy intentions has given the central bank more opportunity to listen to the market rather than unilaterally guide market expectations. Warsh noted that US Treasury yields had risen over the past few months, which he believed reflected solid economic fundamentals. He said: “Economic output has been robust. Capital spending and productivity have performed strongly. The labor market is stable and remains resilient. The bond market is sending many of the same messages.” (Jin10 Data)
Fed Chairman Warsh said that since the June meeting, financial markets have already priced in much of the Fed’s tightening effects, so he disagreed with describing this decision to hold rates as a “pause.” Warsh said: “I would not characterize today’s decision as a pause in any sense. If you had to label it a pause, then the market’s performance says the exact opposite.” Since the Fed’s mid-June meeting, US 2-year and 10-year Treasury yields have each risen about 20bp. Warsh noted that during this period, financial markets did not “pause” adjustments; instead, they continuously repriced based on inflation data and economic growth: on the one hand, inflation data influenced expectations; on the other, strong growth pushed both nominal and real rates higher. He said: “The Fed today did not explicitly adjust the policy rate—that’s correct. But I think this is just the beginning of the policy story, not the end.” (Jin10 Data APP)
According to the CME FedWatch Tool: The probability of the Fed keeping rates unchanged by September is 36.8%, while the probability of a cumulative 25bp rate hike is 63.2% and a cumulative 50bp hike is 0% (vs. 17.8%, 60.2%, and 22% respectively before the Fed decision). By October, the probability of unchanged rates is 26.2%, with a cumulative 25bp hike at 55.6%, a cumulative 50bp hike at 18.2%, and a cumulative 75bp hike at 0% (vs. 11.9%, 46.1%, 34.7%, and 7.3% before the decision). (Jin10 Data APP)
After the Fed announced it held rates steady on Wednesday, Citi still expects the Fed to cut rates later this year. Economists Andrew Hollenhorst and Veronica Clark noted in a client report that Warsh’s press conference sent two dovish signals: first, he said the Fed would assess progress on curbing inflation using a wide range of data; second, he hinted that rising real yields had already tightened financial conditions to some extent. Citi continues to expect rising unemployment in coming months, which will lead the Fed to cut rates in October, December, and January next year. (Wall Street CN)
Macro:
Today will see the release of the US Fed interest rate decision (as of July 29), US initial jobless claims for the week ended July 25, US June core PCE price index YoY, US June personal spending MoM, US Q2 advance annualized real GDP QoQ, US Q2 advance real personal consumption QoQ, US Q2 advance annualized core PCE QoQ, US June core PCE MoM; Eurozone Q2 advance GDP YoY, Eurozone June unemployment rate, Eurozone July industrial sentiment, Eurozone July economic sentiment; France Q2 advance GDP YoY; Switzerland July KOF leading indicator; UK BoE rate decision (as of July 30); Germany Q2 advance non-adjusted GDP YoY, Germany July preliminary CPI MoM, and other data.
Crude Oil:
Overnight, oil prices on both sides of the Atlantic surged, with WTI up 6.74% and Brent up 7.35%. With the resumption of major airstrikes in the Middle East, hopes that the US-Israel and Iran conflict would soon end were dashed. Meanwhile, industry data showing a decline in US crude inventories provided further support. UBS analyst Giovanni Staunovo said that the renewal of military strikes in the Middle East and renewed emphasis by Iranian officials on controlling shipping activity in the Strait of Hormuz—where oil flows are sluggish—are again pushing up oil prices. US President Trump said hours before the Fed decision that the US would carry out retaliatory strikes against Iran, driving prices higher thereafter. DBS energy research head Suvro Sarkar said that with the volatile Middle East conflict, Brent crude will continue to swing wildly in the $80-$100 per barrel range in the near term. (Jin10 Data APP)
Kpler head of commodity research Matt Smith said global fuel supplies are extremely tight, which is encouraging refiners to run at full throttle to capture unusually strong margins. After supply disruptions from the Ukraine and Iran wars, the fuel market has almost no buffer. “Super-sized refining margins continue to drive refiners to run as hard as they can, leading to significant draws in crude oil inventories.” (Wall Street CN)
US refiners are converting crude into gasoline and diesel at a pace not seen since before the COVID-19 pandemic, but amid a historic fuel shortage crisis, even running at full tilt is unlikely to curb surging prices in the near term. According to EIA data, US refiners processed an average of 17 million barrels per day of crude oil last week, running flat out to meet global and domestic fuel demand. That was the highest weekly average since September 2019. In the Midwest, refineries even set an all-time high for weekly crude processing. (Wall Street CN)