SMM July 16 News:
The most-traded SHFE copper contract surged to 105,020 yuan/mt mid-week, gaining nearly 2,000 yuan/mt over the entire week compared to the start of the week. However, copper scrap was supported by compliance costs, with suppliers holding prices firm and resisting declines. The weekly price fluctuation for copper scrap was less than 1,000 yuan/mt. The price difference between copper cathode and copper scrap widened from 2,445 yuan/mt at the start of the week to 3,923 yuan/mt, an increase of over 2,200 yuan/mt from the previous weekend. The expansion in the spread was entirely driven by the unilateral rise in copper cathode prices, while the resilience of copper scrap prices was the core feature of the supply side this week.
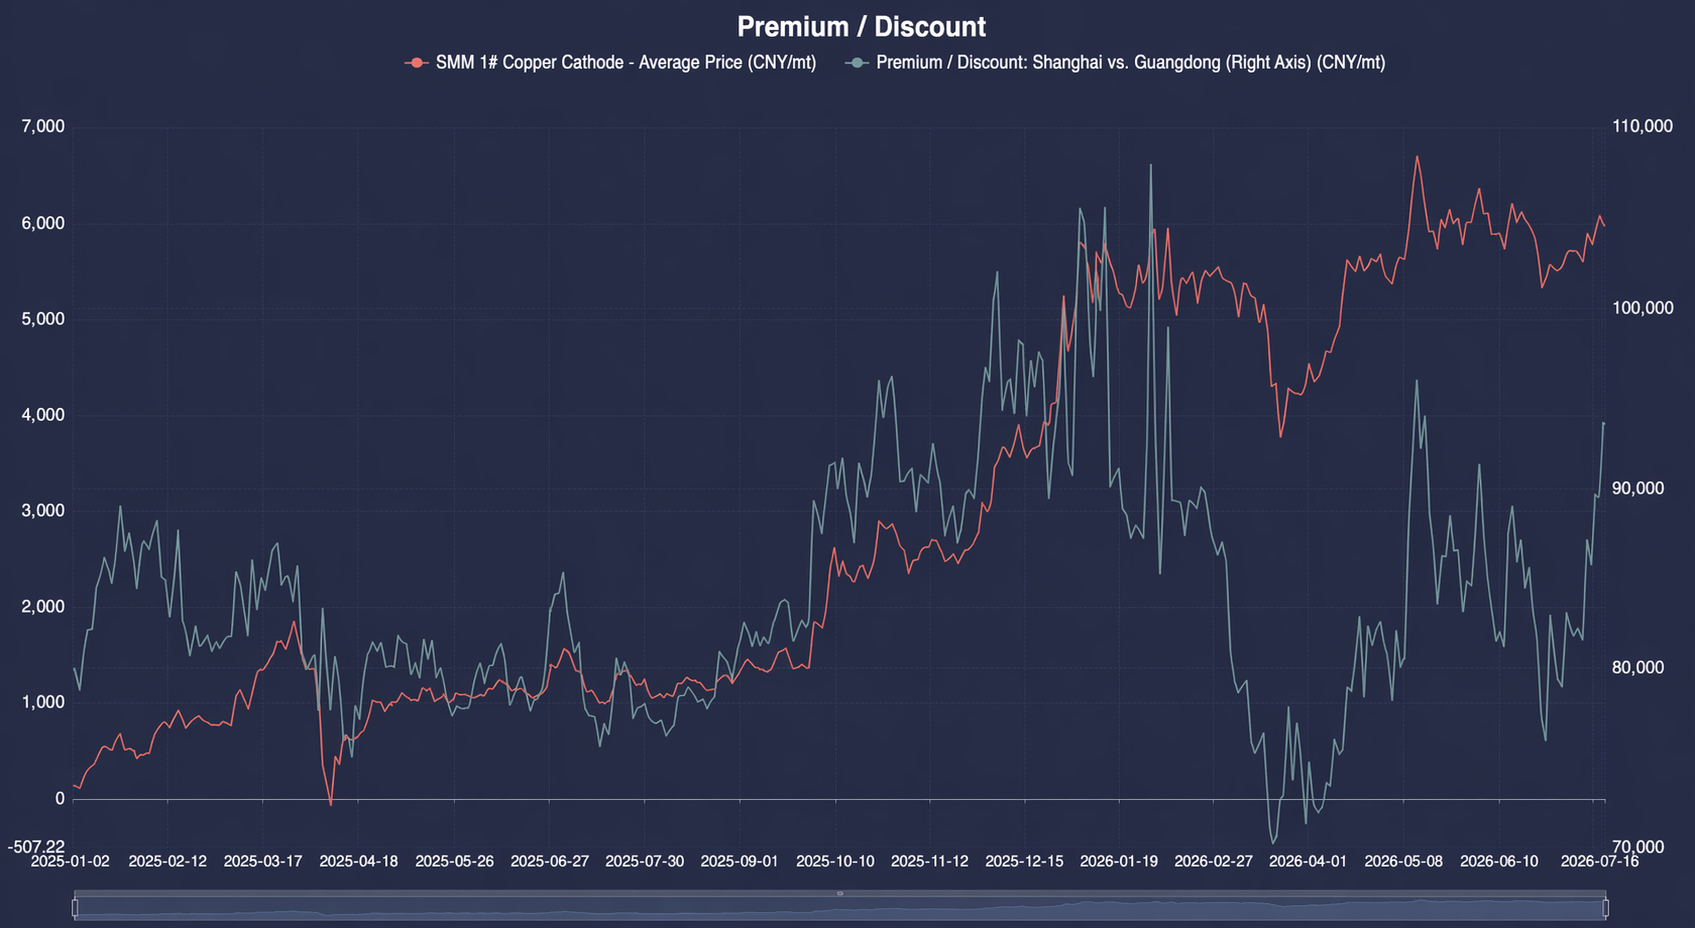
The supply side continued to show a structurally tight pattern since 2026, constrained by two underlying factors. First, reverse invoicing compliance requirements: the aftermath of compliance inspections in south China such as Jiangxi and Hubei had not subsided, and invoicing quotas in places like Shuyang, Jiangsu remained limited, keeping available compliant and deductible copper scrap persistently tight. Second, following the elimination of local illegal tax rebates through Document No. 770 at the end of 2025, the "migratory" small and medium-sized copper scrap traders that had previously relied on subsidies continued to exit the market. Overall available supplies contracted significantly compared to the same period in previous years. Additionally, suppliers generally maintained a psychological barrier of "not selling cheap before copper prices break 100,000 yuan/mt." The weekly pace of shipments closely followed copper price fluctuations: At the start of the week, when copper prices pulled back, the sales sentiment index fell to 2.37, with suppliers widely holding back from selling, market supplies contracted, and secondary copper rod enterprises found it difficult to source low-priced material. Mid-week, as copper prices surged above 105,000 yuan/mt, suppliers' willingness to sell at fixed prices increased, pushing the sales sentiment index to 2.48. However, due to weak off-season orders in downstream scrap-consuming sectors and low acceptance of high-priced material, shipments did not see significant volume. Most of the material was purchased by secondary copper rod enterprises using a hedging strategy of buying raw materials and selling futures, rather than for actual production restocking. Many rod enterprises would stop pricing once they had purchased sufficient material for the day's demand in the morning session, without chasing higher prices to purchase. Towards the end of the week, copper prices consolidated and pulled back, and suppliers once again shifted to holding back from selling, tightening market supplies again. Regional divergence persisted: due to compliance costs and slower capital turnover in south China, purchase prices for bare bright copper were 400-600 yuan/mt lower than in the north. The abnormal structure of different prices for the same material continued, with traders still maintaining a low-inventory, fast-turnover strategy and not daring to stockpile in anticipation of price rises. The issue of payment collection cycles extending to over two weeks remained unresolved, further limiting the elastic release of supply. The demand side was overall weak. Both secondary copper rod and scrap-derived copper anode enterprises were in the high-temperature off-season, with limited new orders. Coupled with expectations of further declines in copper prices, purchases were mainly driven by hedging operations and essential restocking. Even when the cathode-scrap spread surged above 3,900 yuan/mt mid-week, there was no large-scale production restocking. End-user wire and cable enterprises maintained strong wait-and-see sentiment, purchasing only to meet minimum rolling demand. Throughout the week, copper scrap transactions were largely driven by copper price fluctuations and hedging demand, with no trend-based volume increase.
Going forward, if copper prices stabilize above 105,000 yuan and the price difference between copper cathode and copper scrap remains above 3,000 yuan, arbitrage demand may continue to support the circulation of copper scrap. However, if the detailed reverse invoicing rules remain unclear and off-season orders stay sluggish, the structural tightness on the supply side and the weak reality on the demand side will continue to offset each other, making it difficult for transactions to achieve a trend breakthrough.