2026 H1 PV Glass Market Analysis and Outlook — Oversupply Suppresses Prices, Pace of Cold Repair and Market Exit Determines Recovery Space [SMM Analysis]

Published: Jul 09, 2026 14:19 (GMT+8)
[SMM Analysis: H1 2026 PV Glass Market Review and Outlook – Oversupply Weighs on Prices, Pace of Cold Repair-Induced Capacity Rationalization Determines Recovery Room] In H1 2026, the PV glass industry went through a full downward cycle marked by oversupply, weakening demand, prices hitting bottom, industry-wide losses, and accelerated capacity rationalization through cold repairs. China's new installations saw a phased pullback, demand dropped after the export tax rebate adjustment, and the release of previously expanded capacity—these three factors caused the PV glass industry to return to a downward trajectory, with the pace of capacity rationalization accelerating.


SMM, July 9:

In H1 2026, the PV glass industry completed a full downward cycle of oversupply, weakening demand, prices hitting bottom, industry-wide losses, and accelerated capacity rationalization through cold repairs. Three factors—a phased pullback in China's new installations, declining demand after the export tax rebate removal, and the release of earlier expanded capacity—drove the PV glass industry back into a downward trajectory, accelerating the pace of capacity rationalization.

Supply Side: Operating Rate Contracted Continuously; Cold Repairs Became the Industry's Only Destocking Measure

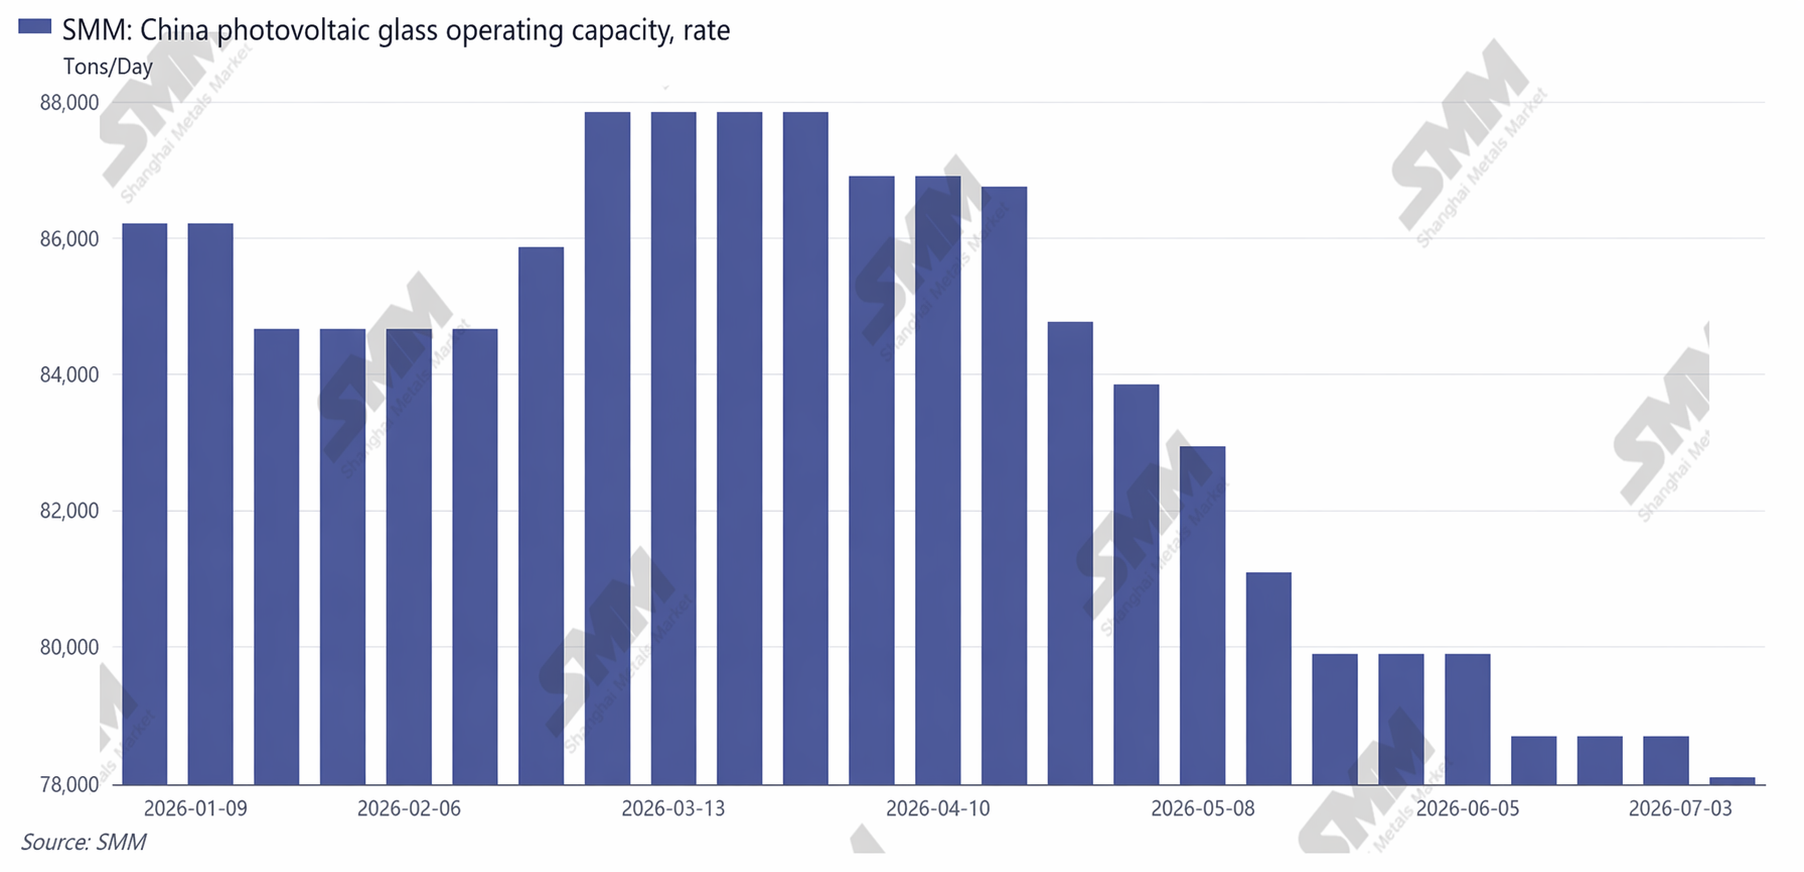
In H1 2026, China's total daily melting capacity of PV glass stayed high. At the start of the year, the industry's operating daily melting capacity reached 86,210 mt/day, theoretically matching 47 GW/month of module demand. Top-tier players ignited and started production at kilns, while some second- and third-tier glass production lines that had started production earlier began capacity ramp-up, continuously increasing China's supply. However, due to the continuous operation requirements of kilns and their high start-stop costs, enterprises initially chose to cut production by plugging outlets rather than cold repairs.

After the export tax rebate was canceled, module enterprises' production schedules declined sharply, and glass purchases contracted significantly, leading to a very severe oversupply of glass. Enterprises began cutting production, and China's operating daily melting capacity dropped to 78,685 mt/day in June.

China's PV Glass Operating Capacity
Demand Side: Domestic Installations Weakened; Overseas Markets Became the Only Demand Growth Driver

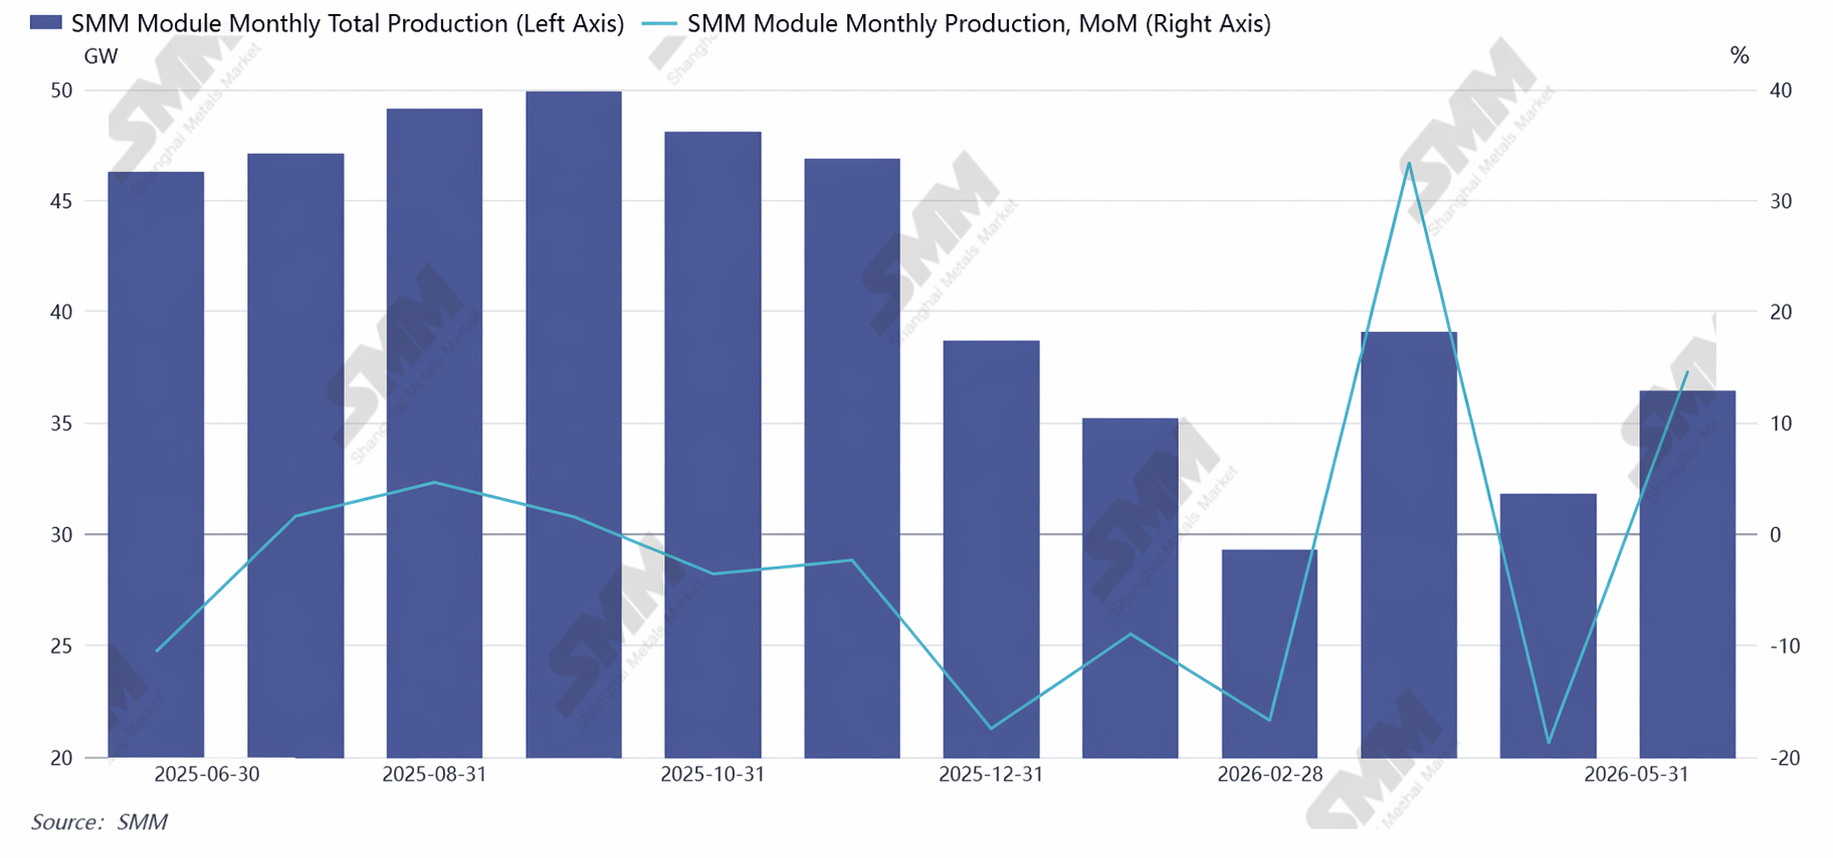
In 2026, due to China's consumption constraints, declining revenues from competitive grid pricing, and widespread delays in power station projects, H1 new installations in China fell significantly YoY, with the full-year expectation revised down to around 210 GW. Average monthly module production schedules in China dropped to around 35 GW in H1. Module factories prioritized destocking their own glass inventory, long-term contract purchases shrank substantially, and scattered rigid-demand purchases became the market mainstream, making pushing for lower prices an industry norm.

Overseas, by contrast, H1 installation expectations saw an overall increase of 30.24% from the previous year. Moreover, as overseas markets generally require localized production, local glass supply remains relatively limited, keeping their reliance on Chinese glass purchases strong.

Module Production Schedule Trend
Price Trend: H1 Prices Fell Consecutively, Stabilized Slightly After Hitting Bottom in June; The Entire Industry Incurred Losses

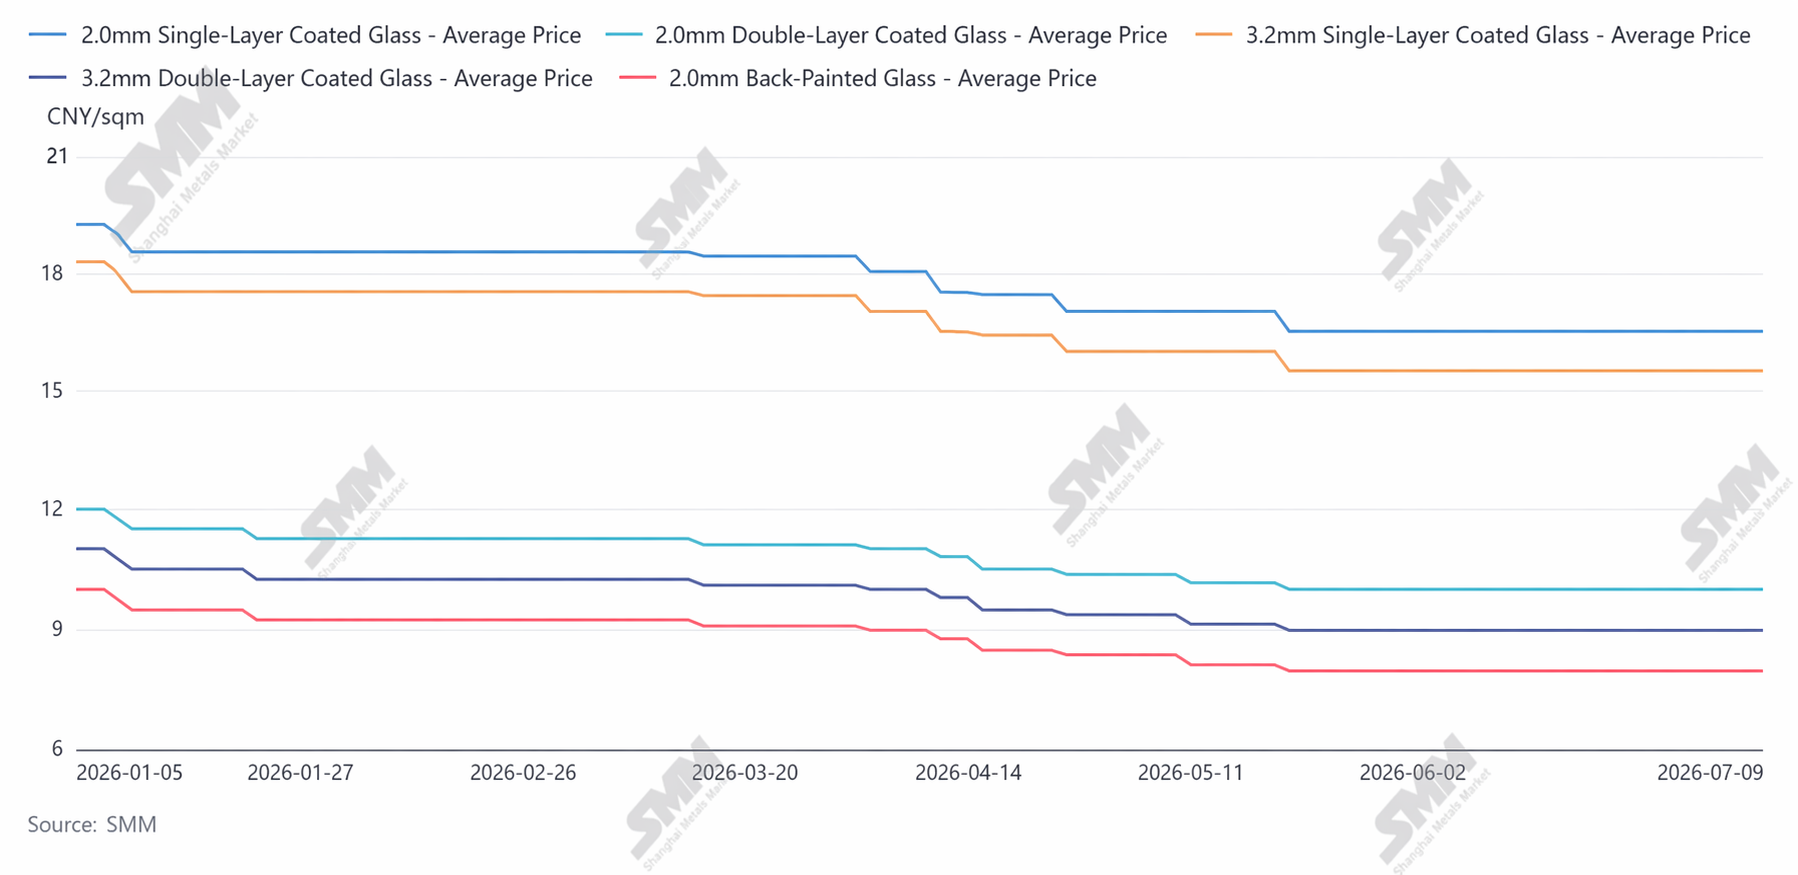
PV glass prices in H1 2026 followed a trajectory of "a slow decline in Q1, an accelerated hit bottom in Q2, and a sideways trend at low levels in June," with all product specifications dropping to historic lows over the past five years. The price of 2.0mm single-layer coated glass was 10.5 yuan/m² at the start of the year, and by the end of June, the lowest transaction price had fallen to 8.0 yuan/m², a price decline of 23.8%, with losses reaching around 2 yuan/m².

The main reasons for the price decline were, on one hand, oversupply coupled with high inventory, driving enterprises to sell at low prices to recoup funds; on the other hand, downstream module makers, facing thin profits, continuously passed cost pressure upstream, creating a strong sentiment for pushing for lower prices.

Glass Price Trend
 

Technology Aspect: H1 Industry R&D Focused Entirely on Cost Reduction, Efficiency Improvement, and Compatibility with High-Efficiency Modules

First, thinner glass was fully popularized: 2.0mm became the standard for double-glass modules, and top-tier players advanced the mass production of 1.6–1.8mm ultra-thin glass, achieving weight reduction and lower silicon consumption for compatibility with large-format modules. Second, light transmittance exceeded 92.5%, with ultra-high-transparency glass reaching 94.7%, compatible with China's current high-efficiency modules. Finally, low-carbon melting furnace technology was implemented, and integrated PV glass scrap recycling production lines gradually commenced operation, reducing enterprises' production costs.

Regarding the H2 2026 outlook: Supply side, cold repairs for China's production lines are expected to keep advancing, accelerating the exit of inefficient capacity, contracting effective industry supply, and leading to slow inventory destocking. Demand side, Q3 is expected to see the launch of overseas demand and the start of centralized projects in China, so module production schedules are likely to rebound, marginally improving glass demand. Price side, after inventory declines persistently, prices are expected to have a foundation for recovery, but a significant price surge requires substantial capacity rationalization and a moderate increase in demand.

In summary, H1 2026 marked a trough period for the PV glass industry in recent years. However, as outdated capacity exits the market and technology is upgraded and iterated, glass supply and demand conditions are expected to recover, and China's involution behavior is likely to improve. The subsequent growth logic for the PV industry remains unchanged. After navigating through the industry cycle, glass is also expected to reach a new starting point.
Data Source Statement: Except for publicly available information, all other data are processed by SMM based on publicly available information, market communication, and relying on SMM's internal database model. They are for reference only and do not constitute decision-making recommendations.

Images in this article contain AI-translated captions for reference only.

For any inquiries or for more information, please contact: lemonzhao@smm.cn
For more information on how to access our research reports, please contact:service.en@smm.cn
Related News
[SMM PV News] Yunnan: Promoting Quality Upgrades in Silicon PV
Oct 09, 2026 15:27 (GMT+8)
[SMM PV News] Yunnan: Promoting Quality Upgrades in Silicon PV
Read More
[SMM PV News] Yunnan: Promoting Quality Upgrades in Silicon PV
[SMM PV News] Yunnan: Promoting Quality Upgrades in Silicon PV
On September 29, the People's Government of Yunnan Province issued the notice on printing and distributing the 15th Five-Year Plan for Regional Coordinated Development of Yunnan Province, which proposes consolidating and enhancing the advantages of traditional industries such as tobacco and energy, strengthening and expanding advantageous resource-based industries dominated by green aluminum, coal-phosphorus chemicals, germanium, and indium in nonferrous and rare precious metals, promoting the quality improvement and upgrading of silicon PV, and fostering the growth of new energy cells, new materials, and advanced equipment manufacturing. It also calls for advancing the digital transformation of manufacturing, building smart factories, and developing intelligent manufacturing. The plan aims to improve the comprehensive transportation network, accelerate the construction of clean thermal power energy bases, optimize the layout of the power grid and natural gas pipeline networks, build key water source projects and large and medium-sized irrigation areas, coordinate the layout of new-type infrastructure, and speed up the construction of the Qujing national-level and Xuanwei provincial-level backbone cold chain logistics bases and the Malong provincial-level logistics hub. It seeks to elevate the development level of the central city cluster of Qilin, Zhanyi, and Malong, promote the coordinated development of Xuanwei with the central urban area, and enhance the comprehensive carrying capacity of surrounding county towns. The plan also aims to improve the public service system and increase the supply of high-quality education, healthcare, cultural, and sports resources. It will improve the commercial circulation system and develop integrated services of commerce, the internet, and logistics.
Oct 09, 2026 15:27 (GMT+8)
[SMM PV Flash] Power generation per watt increases by 3.05%, Tengger Desert field test reconfirms the value of Supreme TOPCon modules in desert-Gobi-wasteland scenarios
Oct 09, 2026 15:26 (GMT+8)
[SMM PV Flash] Power generation per watt increases by 3.05%, Tengger Desert field test reconfirms the value of Supreme TOPCon modules in desert-Gobi-wasteland scenarios
Read More
[SMM PV Flash] Power generation per watt increases by 3.05%, Tengger Desert field test reconfirms the value of Supreme TOPCon modules in desert-Gobi-wasteland scenarios
[SMM PV Flash] Power generation per watt increases by 3.05%, Tengger Desert field test reconfirms the value of Supreme TOPCon modules in desert-Gobi-wasteland scenarios
Recently, the semi-annual field test data from Trinasolar's desert PV outdoor empirical project in Wuwei, Gansu, was released. In a typical desert-Gobi-wasteland large-scale base scenario, Trinasolar's Vertex N-type TOPCon module, with its high bifaciality and excellent low-irradiance response, achieved a 3.05% higher power generation per watt compared to TBC modules.
Oct 09, 2026 15:26 (GMT+8)
[SMM PV News] Leapting Secures Another Major Deal in the Middle East
Oct 09, 2026 15:25 (GMT+8)
[SMM PV News] Leapting Secures Another Major Deal in the Middle East
Read More
[SMM PV News] Leapting Secures Another Major Deal in the Middle East
[SMM PV News] Leapting Secures Another Major Deal in the Middle East
On October 5, 2026, LEAPTING secured another major order in the Middle East market, successfully signing a PV module automated installation contract with an initial installed capacity of approximately 1.5GW, involving about 2.4 million PV modules. According to the project plan, LEAPTING is expected to deploy automated navigation module installation robots (MMR) and introduce new automated navigation forklift robots (AFR), further expanding the application of robotic automated construction in large-scale PV power plants.
Oct 09, 2026 15:25 (GMT+8)
Register to Continue Reading
Gain access to the latest insights in metals and new energy
Already have an account?Sign in here